A TransUnion credit report is a detailed record of your credit history and personal information used by lenders in Canada. It is distinct from your credit score, which is a three-digit number derived from the report's data. Canadians can access their TransUnion credit report for free through specific methods, which is important for monitoring financial health and identifying errors. Understanding this report helps you see what creditors see when you apply for loans, credit cards, or rentals.
What a TransUnion Credit Report Contains
A TransUnion credit report provides a complete account of your financial history as reported to that bureau. It includes personal information such as your name, address, and employer, though this data may appear out of date as it is often only updated when you apply for new credit. The core of the report details your credit usage, listing active and closed credit products like loans and credit cards along with your payment history. It also records all inquiries made into your credit file, which include credit applications, account management checks, and your own requests for your report. This information forms the basis for your TransUnion credit score, a separate three-digit number between 300 and 900 that lenders use to assess risk.
How to Get Your Free TransUnion Credit Report
Canadians have several options for obtaining their TransUnion credit report at no cost. Residents of Quebec and Ontario are entitled to a free Consumer Disclosure, which is the formal name for the complete credit report as mandated by consumer reporting legislation. Individuals in all other provinces and territories can also request their free report through TransUnion's self-service website, by mail, or by phone. The self-service website allows you to order your report online and receive it every 30 days. If online access is not possible, you can contact TransUnion directly by calling their general inquiry line at 1-800-663-9980 to request a copy be mailed to you. The process typically requires you to verify your identity with personal details, and if your initial request is not successful, it may be because the information you provided does not perfectly match the records held by TransUnion.
In such cases, you should try an alternative method, such as submitting a request by mail with copies of identification documents. It is important to note that while credit scores are often advertised, the free report itself is the foundational document you are entitled to receive. Once you have your report, you can review it for accuracy and take steps to dispute any errors you find, which is a key part of maintaining your financial health. The ability to access this report regularly allows you to stay informed and proactive about your credit standing.
Understanding Your Credit Score Versus Your Credit Report
Your TransUnion credit report and your credit score are related but distinct financial tools. The credit report is the detailed record of your credit history, while the credit score is a numerical summary derived from that data. TransUnion calculates its own credit score using its proprietary algorithm based on the information in its report. Creditors in Canada choose which credit bureau to report to and which bureau's data to use, so your TransUnion report and score may differ from those at Equifax. The credit score ranges from 300 to 900, where a higher number indicates a lower perceived risk to lenders.
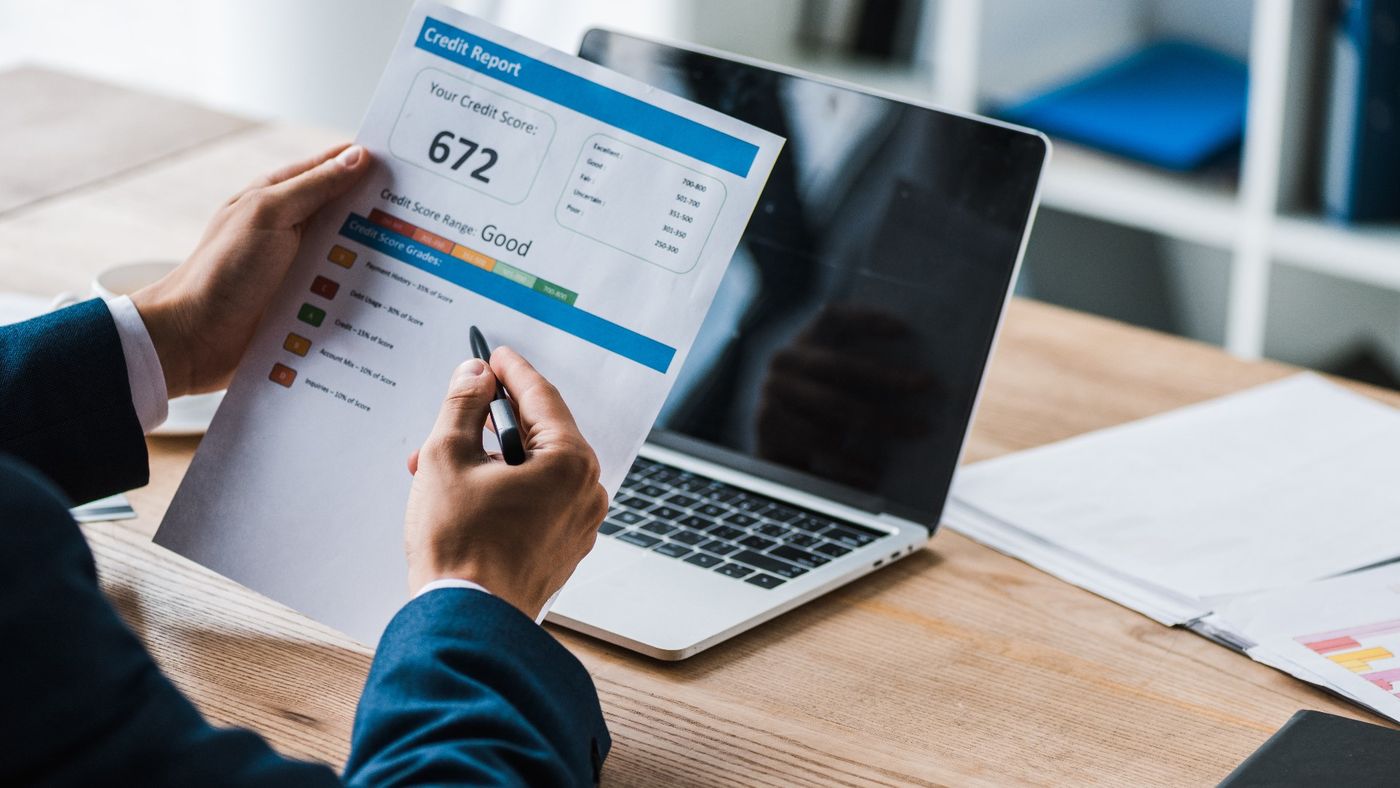
Each lender decides what score range constitutes a good or poor risk, but generally, a score in the 700 to 900 range is considered favourable. Your score is not static. It changes frequently based on updates to your credit report, such as new accounts or payments. It is also just one component a lender evaluates, as they may also consider your income, employment, and other financial information when making a lending decision. This means that even with a strong credit score, other factors in your application are still critically important.
Key Steps for Monitoring and Disputing Your Report
Regularly checking your TransUnion credit report is a critical practice for financial management. You should review it for accuracy at least once a year, or more frequently if you are planning a major credit application. Monitoring helps you catch errors or fraudulent activity early, such as accounts you did not open or incorrect payment statuses. If you find an inaccuracy, you must file a dispute with TransUnion to have it investigated and corrected.
- Gather supporting documents that prove the error on your report.
- Contact TransUnion by phone at 1-800-663-9980 to speak with a representative about your dispute.
- You can also submit a dispute in writing through TransUnion's online portal or by mail.
- TransUnion will investigate your claim with the creditor who reported the information.
- The investigation process typically takes 30 days from the date your dispute is received.
- If the information is found to be inaccurate, TransUnion will correct your report.
- You will receive the results of the investigation in writing once it is complete.
- For suspected fraud, you should contact TransUnion's fraud assistance line at 1-844-580-9978.
After disputing an error, it is wise to check your TransUnion credit report again after the investigation to confirm the correction has been made. You can request your free TransUnion credit report online, by mail, or by phone to review it. Keeping records of all your correspondence with TransUnion is recommended for your own files and for any follow-up that may be required. This diligent approach helps ensure the information that lenders see is accurate and fair. If you need further assistance, you can call TransUnion at 1-800-663-9980 for help with your inquiry.
How Credit Scores Are Used in Canada
Lenders, creditors, landlords, and sometimes employers or insurance companies use credit scores to gauge the likelihood that you will repay borrowed money. A higher score can make it easier to obtain credit products like mortgages, car loans, and credit cards, often with more favourable interest rates. The score represents a statistical probability. For example, a score of 780 suggests that 780 out of 900 individuals with that score are likely to repay their debt. Financial institutions often create their own internal scores as well, using a combination of bureau data and their own customer information. This means the score you see may not be identical to the one a specific lender calculates.
While a good score is beneficial, it is not the sole factor in financial decisions. Lenders also assess your income, debt load, and the purpose of the credit. Furthermore, your score can impact areas beyond borrowing, such as rental applications or certain employment checks, particularly in financial sectors. Therefore, maintaining a healthy credit report that supports a good score is a key part of overall financial health for Canadians.
Accessing Your Score Through Financial Institutions
Some Canadian financial institutions provide customers with free access to their TransUnion credit score as a service. For example, Scotiabank offers its online and mobile banking customers the TransUnion Credit Score tool at no additional charge. Using this service does not impact your credit score. To enroll, Scotiabank shares necessary personal information like your name, address, and date of birth with TransUnion to retrieve your score. The service allows you to track your credit history monthly, view related report information, and receive educational tips on building good credit.
This access is governed by separate terms and conditions between the bank and TransUnion. The credit score provided through such a service is for educational purposes and may not be the exact score a lender uses, as lenders may use different scoring models. It is a convenient way to monitor changes, but it does not replace your right to obtain the full credit report itself for free through the methods provided directly by TransUnion. The bank states that it and its affiliates are not responsible for the TransUnion Credit Score or the information provided through the service.
Provincial Differences in Accessing Credit Reports
The method for obtaining a free TransUnion credit report can vary depending on your province of residence. Consumer reporting legislation in Quebec and Ontario specifically entitles residents to a free Consumer Disclosure from TransUnion. In all other provinces and territories, free access is provided through TransUnion's general policies, such as the self-service website offering a report every 30 days. The following table outlines the primary free access methods by region.
| Region | Primary Free Access Method |
|---|---|
| Quebec | Consumer Disclosure (by law) |
| Ontario | Consumer Disclosure (by law) |
| All Other Provinces & Territories | Self-service website, mail, or phone request |
Regardless of location, all Canadians have the right to dispute inaccurate information on their report. The dispute process and the investigation timeline are consistent across the country. It is important to use the official channels to ensure your request is processed correctly and to protect your personal information from unauthorized access. This regional framework ensures that all consumers can monitor their credit, though the specific pathway may differ.
Frequently asked questions
How often can I get a free TransUnion credit report in Canada?
You can receive your TransUnion credit report for free every 30 days using their self-service website. Residents of Quebec and Ontario are entitled to a free Consumer Disclosure at any time as mandated by provincial consumer reporting legislation. A Consumer Disclosure is a complete account of all the information on your credit report. Equifax also offers free credit reports in all provinces and territories.
What is the difference between a credit report and a credit score?
A TransUnion credit report is a detailed record of your credit history, including accounts and payments. Your credit score is a three-digit number between 300 and 900 calculated from the data in your report, used by lenders to assess your credit risk. The credit report outlines your credit history, while the score is a numerical summary of that risk. You have more than one credit score as each credit bureau uses its own algorithm.
How do I dispute an error on my TransUnion credit report?
You can dispute an error by calling TransUnion at 1-800-663-9980 or by submitting a dispute in writing through their website or by mail. TransUnion will investigate with the reporting creditor, a process that typically takes 30 days, and will send you the results in writing. It is important to check your report again after the investigation to confirm corrections. Keeping records of all correspondence is also recommended.
Is checking my TransUnion credit score through my bank free?
Yes, some banks like Scotiabank offer customers free access to their TransUnion credit score through online banking tools. Using this service does not affect your credit score, and the bank shares necessary personal data with TransUnion to provide it. Scotiabank customers can check their TransUnion credit score as often as they want at no additional charge. The TransUnion Credit Score service is provided by TransUnion Interactive, Inc. to Scotiabank customers.
What is a good TransUnion credit score in Canada?
Credit scores range from 300 to 900. Lenders decide their own risk ranges, but generally, a score in the 700 to 900 range is considered good to excellent. A higher score indicates a lower perceived risk of default to creditors. Each lender decides which credit score range it considers a good or poor credit risk. Your credit score is only one component of the information lenders use to evaluate credit risk.
What should I do if I suspect fraud on my credit report?
If you suspect fraudulent activity, you should contact TransUnion's fraud assistance line at 1-844-580-9978. You should also review your full credit report for unauthorized accounts or inquiries and consider placing a fraud alert on your file. You can get information about fraud prevention and assistance from TransUnion. It is also important to report any errors on your account statements to TransUnion as soon as possible.
Sources and further reading
- How to Get Your Free TransUnion Credit Report in Canada nomoredebts.org
- How to check your credit score online scotiabank.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.