Super Visa insurance is a mandatory private health insurance policy required for parents and grandparents applying to visit Canada on a Super Visa. It must provide a minimum of $100,000 in emergency medical coverage and remain valid for at least one year from the date of entry. This requirement exists because visitors to Canada are not covered by provincial public healthcare plans, leaving them responsible for potentially high medical costs. Arranging compliant insurance is a critical step in the Super Visa application process for Canadian families.
What is a Super Visa and Who is Eligible
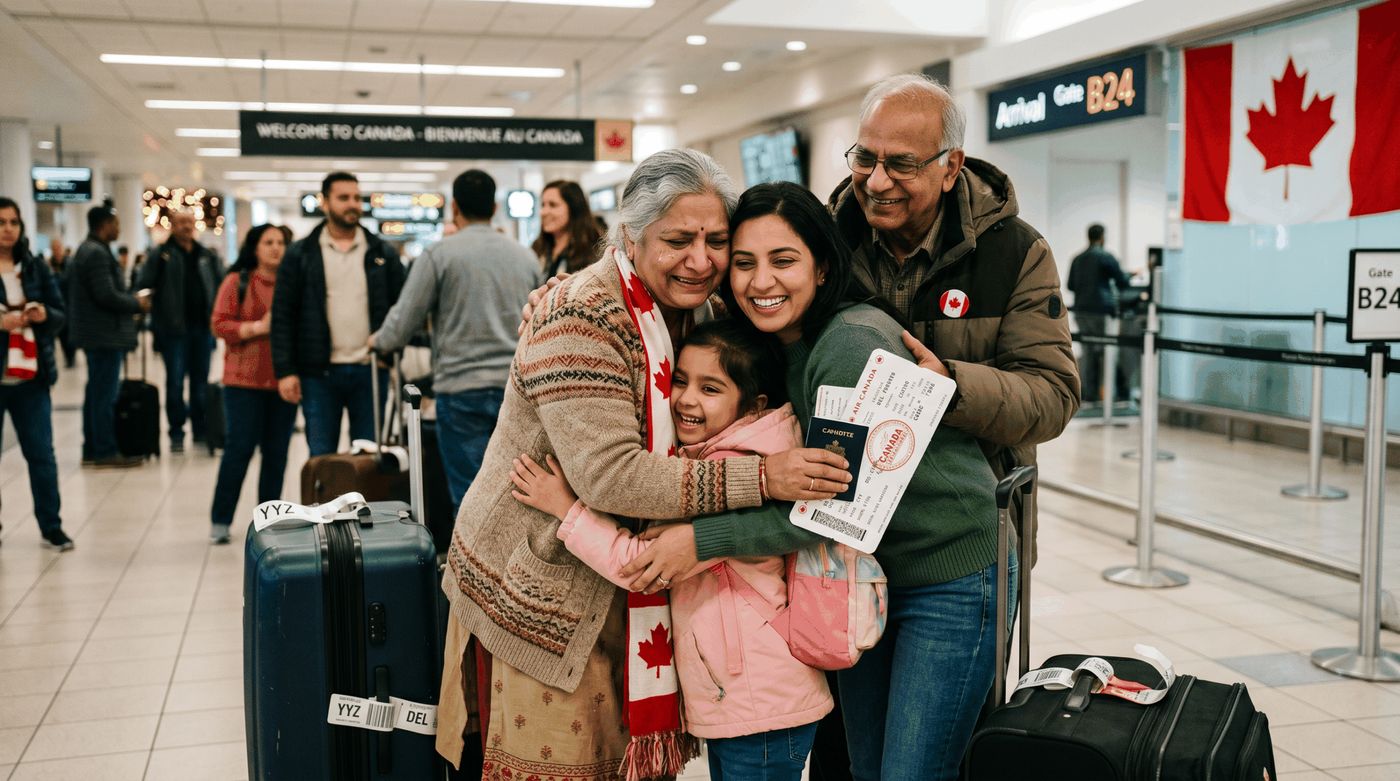
The Super Visa is a multi-entry visa specifically for parents and grandparents of Canadian citizens or permanent residents. It can be valid for up to ten years, depending on passport validity, and allows stays of up to five years per entry into Canada. This is a significant difference from a standard visitor visa, which typically permits stays of only up to six months per visit. To be eligible, applicants must be the parent or grandparent of a Canadian citizen or permanent resident. The host child or grandchild in Canada must be at least 18 years old, live in Canada, and meet a minimum income requirement. Applicants must also pass an Immigration Medical Exam conducted by a designated panel physician, provide a signed letter of invitation from their host, and demonstrate intent to return to their home country after their authorized stay. The Super Visa program was introduced by the Canadian government in 2011 to manage application backlogs from visitors seeking longer stays.
Mandatory Insurance Rules and Requirements
The Government of Canada, through Immigration, Refugees and Citizenship Canada (IRCC), sets specific rules for the health insurance policy required for a Super Visa application. This insurance is not optional. It is an absolute requirement for approval. The policy must provide a minimum of $100,000 in emergency medical coverage. This coverage must be valid for at least one year from the date the visitor enters Canada and must remain continuous for the entire duration of their stay, with no gaps in protection. The insurance must be purchased from a Canadian insurance company or an IRCC-approved foreign provider. As of January 28, 2025, IRCC rules allow for approved foreign insurers in addition to Canadian providers. The policy document must clearly state the insurance company's name and confirm it covers health care, hospitalization, and repatriation costs.
The $100,000 minimum coverage amount is set because medical costs in Canada for visitors can be extremely high. A single emergency room visit, hospital stay, or medical procedure can quickly result in bills that reach tens of thousands of dollars. Since visitors are not eligible for provincial health insurance, these costs are the responsibility of the individual or their family. The insurance requirement protects both the visitor and the Canadian healthcare system from unpaid medical debts. Proof of this insurance must be presented upon each entry to Canada and is subject to review by a border services officer if requested. The policy can be paid in full or through installments with a deposit, but it must be active and valid for the entire planned stay.
Detailed Coverage and Policy Features
Beyond the basic $100,000 emergency medical coverage, Super Visa insurance policies can include a range of other benefits that are important to review. Common covered expenses can include costs for dental emergencies, ambulance services, prescription drugs, and medical evacuation or repatriation. Repatriation coverage is specifically required by IRCC and refers to the cost of returning the insured person to their home country in case of a medical emergency or death. Some policies also offer coverage for side trips outside of Canada, which typically apply to trips of up to 30 days that originate and terminate in Canada, provided the side trip is not greater than 50 percent of the total coverage period. It is crucial to understand the policy's stance on pre-existing medical conditions, as this is a key area where plans differ. Some insurers offer coverage for stable pre-existing conditions if they have been controlled for a specified period prior to the trip, while others may exclude them entirely. The policy's deductible, which is the amount the insured pays before coverage begins, directly affects the premium cost, with higher deductibles leading to lower monthly or annual payments.
Many policies are specifically marketed as meeting and exceeding Canadian government requirements, with some offering coverage limits up to $150,000 or $200,000. Choosing a higher coverage limit can provide additional peace of mind. Policies are designed to offer 365 days of uninterrupted protection, which aligns with the one-year minimum term. The sponsoring child or grandchild in Canada should be aware that they may be liable for medical bills if the insurance is insufficient or lapses, making the choice of a robust policy a critical financial decision for the host family as well.
How to Purchase and Compare Super Visa Insurance
Super Visa insurance must be purchased before the visa application is submitted, as proof of coverage is part of the required documentation. Policies can be bought directly from a Canadian insurance company or through a licensed Canadian broker. Using a licensed broker allows for comparison of plans from multiple IRCC-approved insurers in one place, providing a clear view of prices, deductible options, and specific coverage details. There is no obligation to buy when getting a quote, and broker advice is typically free. Some brokers and insurers offer monthly payment plans, which IRCC accepts for the application, making it easier to manage the cost of the annual premium. It is crucial to ensure the policy you purchase explicitly states it meets the IRCC requirements for Super Visa applications. Comparison services can evaluate plans from over a dozen Canadian insurers, filtering by age, health, and budget to find suitable options.
When obtaining quotes, you will need to provide information about the applicant's age, travel dates, and any pre-existing medical conditions. The cost is influenced heavily by the applicant's age, with premiums for grandparents in their 70s and 80s typically being higher than for younger parents. All policies available through reputable Canadian brokers are from Canadian or IRCC-approved insurers and meet current government requirements. The process of buying a policy is generally straightforward and can be completed online, with the policy documents issued immediately for use in the visa application. It is the responsibility of the sponsoring child or grandchild to arrange this insurance before their parent or grandparent travels to Canada.
Common Mistakes and Refund Policies
A common concern for families is purchasing insurance before the Super Visa is approved, as the application can be refused. Many insurers and brokers have a refund policy for visa refusals. Typically, to receive a full refund, the applicant must submit a written request along with a copy of the IRCC refusal letter and proof, such as passport stamps, that they never entered Canada. The refund is usually only granted if the policy has not yet reached its effective start date and has not been used as proof for any other purpose. Another frequent mistake is purchasing a policy with a term that is too short. The insurance must be valid for a full year from the date of entry, not just for the intended length of stay. Letting coverage lapse while in Canada is a serious error that could affect immigration status. Families should also avoid assuming all travel medical policies meet Super Visa rules. It is essential to verify that the policy explicitly complies with IRCC's $100,000 minimum coverage, one-year minimum term, and approved provider requirements.
Other pitfalls include not reviewing the exclusions in the policy wording, which can lead to denied claims for specific situations or activities. Failing to declare pre-existing conditions accurately during the application can also void coverage. It is important to choose a policy that offers flexibility, such as options for early return refunds or the ability to extend coverage, given that Super Visa stays can be long and plans may change. The sponsoring family member should keep a copy of the insurance certificate and the insurer's emergency contact information readily available throughout the visitor's stay in Canada.
Super Visa Versus Regular Visitor Visa
Understanding the difference between a Super Visa and a regular visitor visa is important for choosing the right path. A regular visitor visa, or Temporary Resident Visa (TRV), is for citizens of foreign countries who are not visa-exempt and are visiting Canada for tourism, business, or family visits. It typically allows stays of up to six months per visit and is valid for up to ten years. In contrast, the Super Visa is exclusively for parents and grandparents of Canadian citizens or permanent residents. The most significant differences are the length of permitted stay per entry and the mandatory insurance requirement.
| Feature | Regular Visitor Visa (TRV) | Super Visa |
|---|---|---|
| Primary Applicants | General visitors for tourism, business, family | Parents/grandparents of Canadian citizens/PRs |
| Maximum Stay Per Entry | Up to 6 months | Up to 5 years |
| Visa Validity | Up to 10 years | Up to 10 years |
| Medical Insurance | Not mandatory for application | Mandatory ($100,000+, 1 year term) |
| Medical Exam | Usually not required | Required (Immigration Medical Exam) |
| Letter of Invitation | May be required | Required from child/grandchild meeting income criteria |
| Proof of Relationship | Generally not required | Required (e.g., birth certificate) |
The Super Visa is designed for longer, more stable visits, which is why the insurance requirement is so stringent. For visits shorter than six months, a regular visitor visa may be more appropriate as it does not carry the same insurance obligation. However, for families seeking extended multi-year visits, the Super Visa provides a valuable option despite the upfront cost and planning involved with securing the required insurance. The Super Visa also allows applicants to apply for an extension of their stay while they are in Canada, adding to its flexibility for long-term family visits.
Steps to Apply for a Super Visa
The application process for a Super Visa involves several specific steps that must be completed in order. First, the applicant must ensure they are eligible as a parent or grandparent of a Canadian citizen or permanent resident. The host in Canada must then prepare a signed letter of invitation that includes a promise of financial support and proof they meet the minimum income requirement. The applicant must obtain a private health insurance policy that meets all IRCC requirements, including the $100,000 minimum coverage and one-year validity from a Canadian or approved insurer. The applicant must complete an Immigration Medical Exam with a designated panel physician, which is a mandatory part of the process. The applicant must gather all required supporting documents, including proof of the relationship, a valid passport, and the insurance policy certificate. The application is then submitted, either online or on paper, to IRCC for processing, which includes security and criminality checks. It is important to apply well in advance of the planned travel date to account for processing times. The final step is presenting the visa and proof of valid insurance to a border services officer upon arrival in Canada.
Frequently asked questions
How much does Super Visa insurance cost?
Super Visa insurance policies typically cost between $1,000 and $3,000 per year. The average monthly cost is between $100 and $200, but this varies significantly. The cost depends on the applicant's age, health, chosen deductible, and specific coverage benefits. Premiums are generally higher for older applicants, such as grandparents in their 70s or 80s.
Can I pay for Super Visa insurance monthly?
Yes, many Canadian insurers and brokers offer monthly payment plans for Super Visa insurance. Immigration, Refugees and Citizenship Canada accepts policies paid in installments for Super Visa applications. This makes the annual premium more manageable for families. Some brokers specifically highlight monthly payment options to assist with budgeting.
What happens if the Super Visa application is refused?
Many insurance providers offer a refund if the Super Visa application is refused. To qualify, you must submit proof of the refusal from IRCC. You must also show that the insured person never entered Canada. The refund is typically issued only if the policy has not yet started and has not been used for any other purpose.
Does Super Visa insurance cover pre-existing conditions?
Coverage for pre-existing conditions varies by policy. Some Super Visa insurance plans include stability clauses that cover pre-existing conditions if they have been stable for a defined period before the trip. Other plans may exclude them. It is essential to review the policy wording carefully to understand the specific terms, as this is a key factor when comparing plans for applicants with medical histories.
How long must the Super Visa insurance be valid for?
The insurance policy must be valid for a minimum of one year from the date of entry into Canada. The coverage must be continuous with no breaks or gaps for the entire stay. Proof of valid insurance is required on each entry to Canada. If the insurance will expire before the planned departure, the visitor must obtain a new policy.
Can I buy Super Visa insurance from a foreign company?
As of January 28, 2025, Immigration, Refugees and Citizenship Canada (IRCC) updated its rules to allow Super Visa insurance from approved foreign insurers in addition to Canadian providers. The policy must come from a Canadian company or an IRCC approved provider. All insurance policies available through licensed Canadian brokers like BestQuote meet the current 2026 government requirements. Choosing a Canadian insurance provider may offer advantages including familiarity with Canada's healthcare system and access to local support. It is essential to ensure the insurer is on IRCC's approved list to meet the visa application criteria.
Sources and further reading
- Super Visa for Parents and Grandparents: Travel Insurance ... rbcinsurance.com
- Super Visa Insurance for Visitors to Canada gms.ca
- Travel insurance for long-term visitors to Canada cooperators.ca
- Super Visa Insurance for Canada 2026: Compare Policies ... bestquotetravelinsurance.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.