In Canada, you can get your credit report for free from the two national credit bureaus, Equifax and TransUnion. Every consumer is entitled to access their own report at least once a year without charge. Obtaining your credit report allows you to review your credit history, check for inaccuracies, and understand how lenders view your financial reliability. Regularly checking your credit report is a key step in managing your personal finances and protecting against identity theft.
Understanding Credit Reports and Bureaus in Canada
Your credit report is a detailed record of your borrowing and repayment history maintained by credit reporting agencies. In Canada, the two major national credit bureaus are Equifax Canada and TransUnion Canada. These private companies collect information from lenders, such as banks and credit card companies, and compile it into an individual file for each consumer. The primary purpose of a credit report is to provide lenders with a standardized and objective basis for assessing your creditworthiness when you apply for loans, mortgages, or credit cards. The report does not contain your credit score itself but includes all the data used to calculate that score. It is important to understand that you may have slightly different information on file with each bureau, as some creditors may report to only one of them. Consequently, your Equifax credit report and your TransUnion credit report can contain different details about your credit history.
The contents of a standard credit report include several key sections. Your personal identification information, such as your name, current and previous addresses, date of birth, and Social Insurance Number, forms the first part. The heart of the report is your credit history, which lists your current and past credit accounts, including credit cards, lines of credit, loans, and mortgages. For each account, the report shows the date it was opened, the credit limit or loan amount, the current balance, and your payment history. Your payment history is summarized using a credit rating on a scale from 1 to 9, where a rating of 1 indicates you pay bills within 30 days of the due date and a rating of 9 can mean you never pay. An 'R' rating, also ranging from 1 to 9, is assigned by lenders based on your history with specific types of revolving credit.
Other sections of the report include public records, such as bankruptcies or registered court judgements, and a list of inquiries showing which companies have requested your credit report. Regularly reviewing your credit report from both bureaus allows you to verify that all this information is accurate and up to date. Errors on your report, such as accounts you did not open or incorrect payment statuses, can negatively impact your ability to obtain credit. By law, you have the right to dispute any information you believe is wrong, and the credit bureau must investigate your claim at no charge to you.
Your Legal Right to a Free Credit Report
Canadian consumer reporting legislation grants every individual the right to access their own credit report for free. You are entitled to request and receive a copy of your consumer credit report from both Equifax and TransUnion at least once every year without paying any fee. This right exists regardless of your credit history or financial situation. The free report is a complete disclosure of the information the bureau holds about you, though some personal details may be masked for privacy when mailed. It is important to exercise this right annually, as checking your own report does not harm your credit score. In fact, monitoring your report is a responsible financial practice that helps you stay informed and detect potential fraud early.
The process for obtaining your free annual report is designed to be accessible through multiple channels. You can request it online through the credit bureaus' official websites, by phone using their toll-free numbers, or by mailing a completed request form. There is no requirement to purchase any additional service or product to get your free report. Some third-party services and financial institutions also offer ways to view your credit report or score, but the legislated free access comes directly from Equifax and TransUnion themselves. If you encounter any issues verifying your identity online or by phone, the mail-in option remains a reliable alternative.
It is a common misconception that you have only one universal credit report. In reality, you have at least two separate reports, one at each major bureau. Since information can differ between them, it is advisable to get both your Equifax and TransUnion reports each year to get a full picture of your credit history. The free annual report is distinct from credit monitoring services, which typically charge a monthly fee for ongoing access and alerts. While monitoring services offer convenience, they are not necessary to fulfill your annual check. The free report provided by law will include notes and explanations to help you understand the contents and instructions on how to dispute errors you may find.
Step-by-Step Methods to Request Your Report
There are three primary methods to obtain your free credit report from Equifax and TransUnion: online, by phone, and by mail. Each method requires you to verify your identity to protect your personal information. The online method is often the fastest, while phone and mail requests result in a physical copy being sent to your address. To begin the process, you will need to provide personal details such as your full name, date of birth, current and previous addresses, and your Social Insurance Number. Having at least two valid pieces of government-issued identification on hand is recommended, especially for mail requests. The following list outlines the key steps common to all methods.
- Gather required personal information, including your full name, date of birth, and Social Insurance Number.
- Prepare at least two valid pieces of identification, such as a driver's licence and a utility bill.
- Choose your preferred request method: online, by phone, or by mail.
- Accurately answer identity verification questions based on your credit file history.
- If requesting by mail, ensure copies of your ID documents are clear and less than 90 days old.
- Provide your current mailing address where the report should be sent.
- Keep a record of your request date and any reference numbers provided.
- Allow up to three weeks for delivery if requesting a physical copy by mail or phone.
In Canada, you can access your credit report online for free from both major credit bureaus. Both Equifax and TransUnion offer free online access to your credit report. You can also receive your Equifax credit score online for free. It is advisable to get your report from both Equifax and TransUnion, as the details in each one could be quite different.
Both Equifax and TransUnion offer websites where you can request your free credit report directly. You will need to go to the consumer section of their websites and locate the option for a free report. The process involves filling out an online form with your personal information and answering a series of identity verification questions based on your credit file. These questions might ask about previous loans or account details to confirm you are the rightful person. If you successfully pass the verification, you will typically gain immediate online access to view and download your report. If the system cannot verify your identity online, it may offer you the option to have the report mailed to you instead. Equifax also provides a free credit score estimate online, while TransUnion generally charges a fee for a score alongside the free report.
You can request your free credit report by calling the credit bureaus. The toll-free number for Equifax Canada is 1-800-465-7166. The toll-free number for TransUnion Canada is 1-800-663-9980. When you call, you will go through automated questions to confirm your identity. Your credit report will then be sent to you by mail, which usually takes up to 3 weeks to arrive.
You can also request your free credit report by calling the credit bureaus' dedicated toll-free numbers. The numbers are Equifax at 1-800-465-7166 and TransUnion at 1-800-663-9980. When you call, you will interact with an automated phone system that will guide you through a series of questions to confirm your identity. The questions are similar to those asked online. Once your identity is verified, the system will process your request and mail your credit report to your address on file. It is important to speak clearly and provide accurate information, as a small mistake can cause the automated system to reject the request. If the phone request is unsuccessful, you can try another method. The report typically arrives by mail within three weeks.
You can get your free credit report by mail by filling out a request form. You need to download and mail the Credit Report Request Form to Equifax Canada. Once they receive your completed form, they will send your credit report back to you by mail at no charge. The report you receive will come with notes and explanations to help you understand it. It will also tell you what to do if you spot a mistake.
The mail-in method involves filling out a specific credit report request form. You must download the form from the Equifax or TransUnion website, print it, and complete it by hand. The form requires you to provide your full personal details and include copies of two pieces of identification, such as a driver's licence and a utility bill, to prove your identity and address. The documents must be less than 90 days old. You then mail the completed form and photocopies of your ID to the address specified by the credit bureau. There is no fee required for this service. Once the bureau receives and processes your request, they will mail your credit report back to you. This method is useful if you have difficulty with the online or phone systems, though it is the slowest, taking several weeks for the round trip.
What to Do After Receiving Your Credit Report
When your credit report arrives, whether online or in the mail, you should review every section carefully for accuracy. Start by checking your personal information for any misspellings, incorrect addresses, or wrong birth dates. Then, examine each account listed in the credit history section. Verify that all the accounts belong to you, that the credit limits and balances are correct, and that the payment status and history are accurately reported. Look for any accounts you do not recognize, as these could be signs of identity theft or a clerical error where someone else's information was mixed with yours. Also, review the inquiries section to see which companies have accessed your report. Too many hard inquiries in a short time can affect your credit score.
If you find an error or suspicious entry on your report, you have the right to dispute it. Both Equifax and TransUnion have formal processes for disputing information, which they must provide at no cost to you. You can typically initiate a dispute online, by phone, or in writing. You will need to clearly identify the item you are disputing and provide any supporting documentation you have, such as account statements or payment records. The credit bureau is then obligated to investigate your dispute by contacting the lender or data provider that reported the information. The investigation usually must be completed within 30 days. If the information is found to be inaccurate or cannot be verified, the bureau must correct or delete it from your file and notify you of the result.
After reviewing the report, you should also understand the credit rating codes and what they mean for your financial health. A rating of '1' or 'R1' is the best, indicating consistent on-time payments. Ratings escalate to '9' or 'R9' for the worst performance, such as accounts sent to collection or included in a bankruptcy. These ratings directly influence your credit score, which is a separate three-digit number ranging from 300 to 900. While your free report may not include your score, understanding the underlying data helps you comprehend why your score is what it is. If your report reveals negative information, you can take steps to improve your credit over time, such as paying down balances and ensuring all future payments are made on time.
Credit Scores Versus Credit Reports
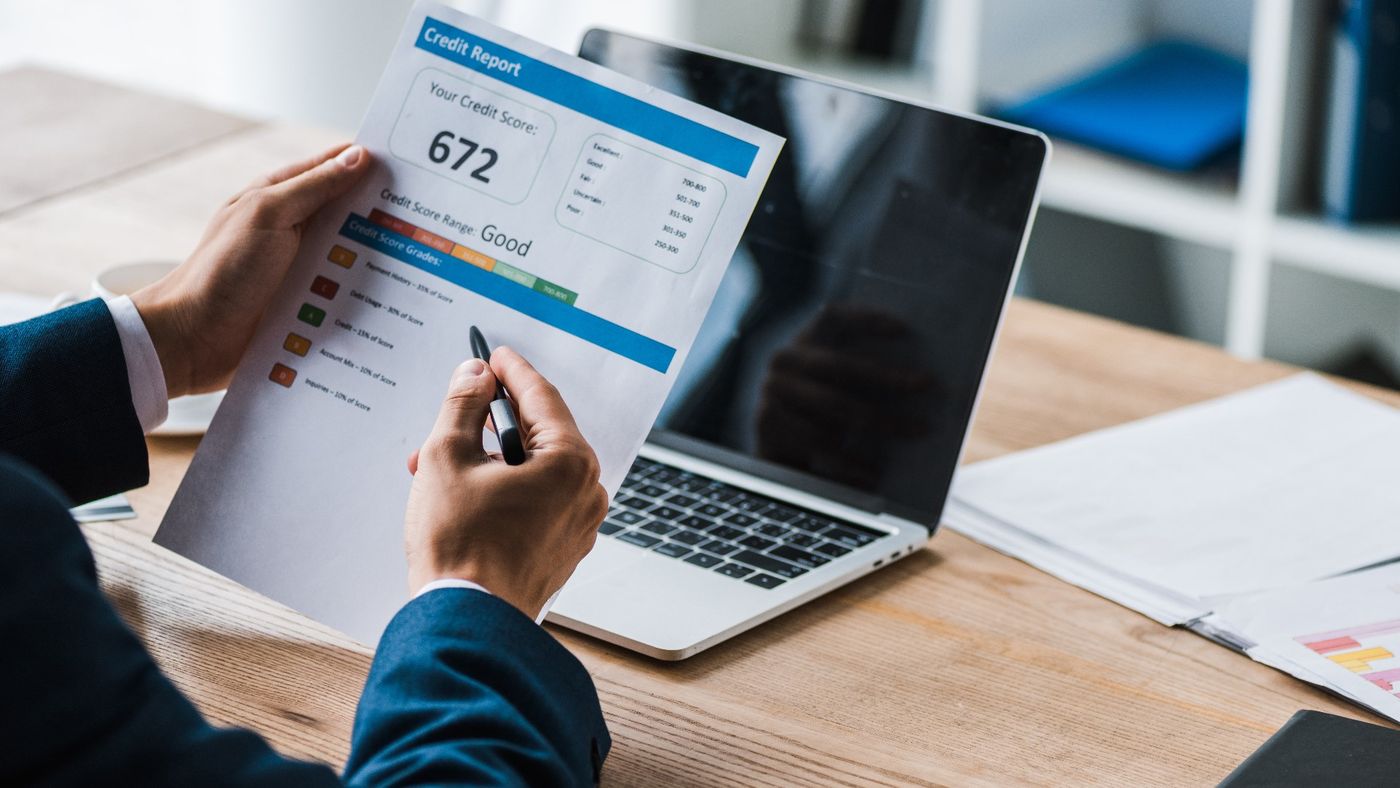
A credit score is a numerical summary of the risk you represent to a lender at a specific point in time, while a credit report is the detailed history that data is drawn from. In Canada, credit scores provided by Equifax and TransUnion typically range from 300 to 900, with a higher score indicating lower risk. The score is calculated using a proprietary formula that weighs factors from your credit report, such as your payment history, amounts owed, length of credit history, new credit applications, and types of credit used. It is crucial to understand that you do not have just one universal credit score. Different lenders may use slightly different scoring models, and the score you see may differ from the one a lender sees.
Your right to a free annual credit report does not automatically include a free credit score. Equifax provides a free credit score estimate online based on the data in your Equifax report. TransUnion generally charges a fee for access to a credit score, though it provides the report for free. Many banks and financial service companies, such as CIBC through its CreditView Dashboard and Intuit Credit Karma, offer free credit score estimates to their clients or users as a service. These scores are educational estimates meant to give you a general idea of your standing. They are useful for tracking trends, but the exact number may not match what a mortgage lender pulls when you apply for a loan.
Regularly checking your credit report is more fundamental than monitoring your score alone. Errors on your report will inevitably drag down your score, so correcting inaccuracies is the first step to improving your credit health. Since the report contains the raw data, it gives you the specific reasons behind your score. For instance, if your score drops, you can look at your report to see if a missed payment was reported or if your credit card balances increased. Focusing on the behaviours that shape the report, paying bills on time, keeping credit utilization low, and not applying for too much new credit at once, is the most effective way to build and maintain a good credit score over the long term.
Common Mistakes and How to Avoid Them
Many Canadians make the mistake of not checking their credit reports regularly, often going years without reviewing their files. This can allow errors or fraudulent activity to persist unnoticed, potentially causing problems when you next apply for credit. You should aim to check both your Equifax and TransUnion reports at least annually, and you can stagger these requests six months apart for more continuous monitoring. Another common error is only checking one bureau's report. Because creditors may not report to both, an issue might exist on only one file, and you could miss it if you don't check both.
When requesting your report, a frequent hurdle is failing the identity verification questions. This often happens because the information you provide does not perfectly match what the bureau has on file, perhaps due to an old address or a minor variation in your name spelling. If this occurs online or by phone, do not assume it reflects a problem with your credit. Simply try the mail-in method, which allows you to submit copies of your identification directly. Ensure the identification documents you send are clear, valid, and less than 90 days old if they are proof of address. Always keep a copy of any forms or correspondence you send for your records.
After receiving the report, a critical mistake is not taking action on errors. Some people feel the dispute process is too complicated or believe the bureaus are always correct. However, the law requires them to investigate your disputes. Failing to correct an inaccuracy means it will continue to affect your creditworthiness. Be proactive and persistent. Finally, avoid confusing free annual reports with paid subscription services. While companies offer credit monitoring for a monthly fee, you are not required to pay for your basic report. Be clear about what you are signing up for online. Read the terms to ensure you are not inadvertently enrolling in a paid service when you only wanted your free annual disclosure. The following list details common pitfalls to avoid during the entire process.
- Failing to check reports from both Equifax and TransUnion annually.
- Giving up after failing online or phone identity verification without trying the mail-in method.
- Not reviewing every section of the report, including personal details and inquiry lists.
- Ignoring errors or inaccuracies found on the report instead of disputing them.
- Confusing free annual reports with paid credit monitoring subscription services.
- Not keeping copies of request forms, identification, and dispute correspondence.
- Assuming a single credit score is your only important metric, neglecting the underlying report data.
Paid Services and Additional Options
Beyond the free annual report, both Equifax and TransUnion offer various paid services for consumers who want more frequent access or additional features. These typically include credit monitoring, which provides regular updates and alerts about changes to your credit file, and ongoing access to your credit score. For example, Equifax offers products like Equifax CompleteTM Premier, which includes credit report and score access, monitoring, and identity theft insurance, for a monthly subscription fee. TransUnion provides similar monitoring services. These paid options can be useful for individuals actively rebuilding credit, those who have been victims of identity theft, or people who prefer the convenience of automatic alerts.
Many Canadian financial institutions also provide credit score access as a complimentary service to their clients. CIBC offers the CreditView Dashboard through its online and mobile banking platforms, providing a TransUnion credit score and report summary to its clients. Scotiabank provides links and information to Equifax services. These bank-provided services are usually free for customers and offer a convenient way to keep an eye on your credit score between your annual full report checks. However, they may not provide the complete detailed credit report that you get directly from the bureaus, and they typically only show information from one of the two bureaus.
Third-party services like Intuit Credit Karma Canada also offer free credit scores and report insights. These services use their own algorithms to provide an educational score and are supported by advertising. They can be a helpful tool for general monitoring, but it is important to remember that the score and data they show are sourced from only one credit bureau. Regardless of which additional service you might use, your foundational right remains to obtain your full, detailed credit report directly from Equifax and TransUnion for free each year. These paid and third-party services are supplements to, not replacements for, that annual review.
In Canada, there are several ways to check your credit report for free. The two main credit reporting agencies are Equifax and TransUnion. You can request a free copy of your credit report from each bureau once per year. The main free access methods are online, by phone, and by mail.
| Access Method | Cost | Report Provided | Credit Score Included | Frequency |
|---|---|---|---|---|
| Free Annual Report (Direct from Bureau) | Free | Full detailed report | Equifax provides a free estimate. TransUnion typically charges | Once per year per bureau |
| Paid Monitoring Service (e.g., Equifax CompleteTM) | Monthly fee | Report and monitoring alerts | Usually included | Ongoing, often daily |
| Bank Service (e.g., CIBC CreditView) | Free for clients | Report summary or insights | Free score estimate provided | Regularly, via online banking |
| Third-Party Service (e.g., Intuit Credit Karma) | Free | Report insights | Free score estimate provided | Ongoing |
Frequently asked questions
How often can I get a free credit report in Canada?
You are entitled to receive one free credit report per year from each of the two major credit bureaus, Equifax and TransUnion. This is a right granted by consumer reporting legislation. You can request these reports at any time, and they do not have to be requested simultaneously. Many people choose to stagger their requests, getting one report every six months, for more consistent monitoring throughout the year.
Is checking my own credit report bad for my credit score?
No, checking your own credit report has no negative impact on your credit score. When you request your own report, it is recorded as a 'soft inquiry' or 'consumer disclosure,' which is not factored into your credit score calculation. Only 'hard inquiries' made by lenders when you apply for new credit can potentially lower your score slightly. Regularly reviewing your own report is a responsible financial habit.
What is the difference between a credit report and a credit score?
A credit report is the detailed history of your credit accounts, payments, and personal information held by a credit bureau. A credit score is a three-digit number, typically between 300 and 900, that summarizes the risk level indicated by your report at a specific time. You have a legal right to a free report annually, but a free score is not always included. The report provides the raw data, while the score is a statistical interpretation of that data used by lenders.
What should I do if I find an error on my credit report?
If you find inaccurate information on your credit report, you should dispute it with the credit bureau that issued the report. You can initiate a dispute online, by phone, or in writing, and the bureau must investigate it at no charge to you. Provide a clear explanation of the error and include any supporting documents. The bureau typically has 30 days to investigate and must correct or delete information that is found to be inaccurate or unverifiable.
Why should I get reports from both Equifax and TransUnion?
You should get reports from both Equifax and TransUnion because they are separate companies with independent databases. Not all lenders report account information to both bureaus, so your files can contain different details. An error or a sign of fraud might appear on only one of your reports. Checking both gives you a complete picture of your credit history and ensures you can identify and correct issues no matter where they are recorded.
Can I get my credit report if I have no credit history?
Yes, you can and should request your credit report even if you believe you have no credit history. The report will confirm whether a file exists in your name. If you have never used credit, the report may be mostly blank or contain only your personal information. Requesting it is a good first step to ensure your identity has not been used fraudulently and to establish a baseline as you begin to build your credit history.
Sources and further reading
- Consumer Credit Report | Equifax CA equifax.ca
- Free Credit Report in Canada: 3 Ways to Get Yours | CCS nomoredebts.org
- How to check your credit report and credit score cibc.com
- Credit bureau reports | Scotiabank Canada scotiabank.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.