Canadian consumers are entitled to obtain their TransUnion credit report free of charge. This report, known as a consumer disclosure, provides a detailed record of your credit history as held by one of the country's two major credit bureaus. Regularly reviewing your credit report is a key part of managing your financial health, as it allows you to check for accuracy and understand your credit standing. Accessing this report for free can be done through several methods, including online, by mail, or in person.
Understanding Your TransUnion Credit Report and Score
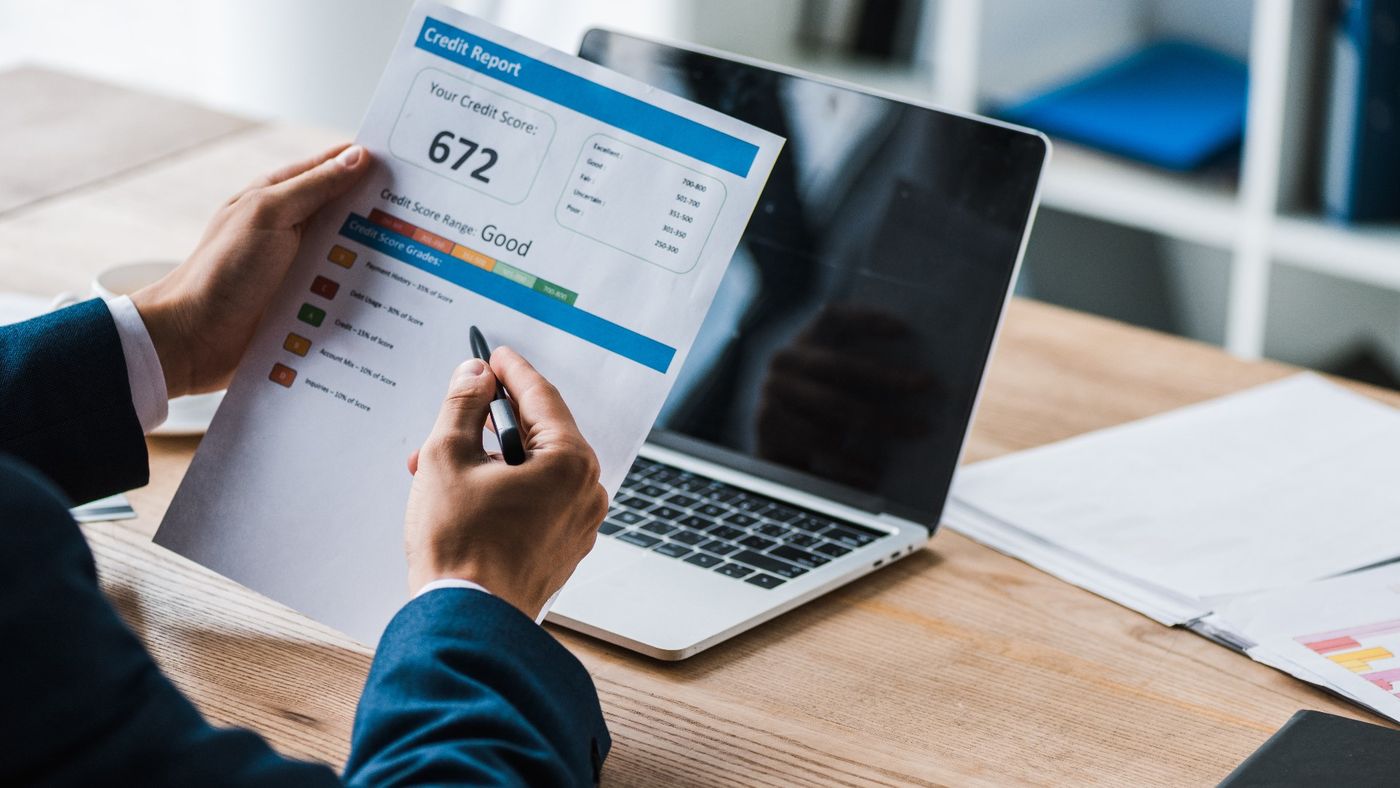
A TransUnion credit report, or consumer disclosure, is a comprehensive record of your credit history as reported to that bureau. It details your credit accounts, payment history, and credit inquiries, including account management inquiries, non-credit related inquiries, and your own inquiries. The information in this report is used to calculate your TransUnion credit score, which is a three-digit number between 300 and 900. This score represents the likelihood you will repay borrowed money, with a higher number indicating better odds. For example, a score of 780 means 780 people out of 900 are likely to repay their debt. It is important to note that information such as your address or employer may appear out of date, as it is often only updated when you apply for new credit. Creditors choose which bureau to report to, so your TransUnion report may differ from your Equifax report, and each bureau uses its own scoring algorithm.
Legal Rights and Frequency of Free Reports
Under Canadian law, you have the right to obtain a copy of your consumer disclosure from TransUnion free of charge. This is a fundamental consumer protection that ensures you can review the information creditors use to make decisions about you. The free report is distinct from commercial services that may advertise free credit scores as part of a subscription or trial. TransUnion provides several official channels for accessing your free report, including a dedicated self-service website where you can receive a report every 30 days. You can also obtain a free report each week through the centralized service at AnnualCreditReport.com. There is no annual limit to the number of free reports you can request through these legitimate avenues, allowing for regular monitoring of your credit file.
Step-by-Step Methods for Requesting Your Free Report
TransUnion offers multiple avenues to request your free credit report, accommodating different preferences for access. You can request your report online through their consumer portal, which is often the fastest method. For those who prefer traditional mail, you must download and complete a Consumer Request form and send it to TransUnion. Requesting by phone is another available option. In some provinces and territories, you can visit a TransUnion office in person to obtain your free credit report directly. If one method does not work, perhaps due to a mismatch in your information, you should try an alternative method, as it does not necessarily mean you have done anything wrong.
To successfully request your free TransUnion credit report, you must provide specific personal information. This required information includes your full name, date of birth, and current address. You must also provide your previous address if you have lived at your current address for less than two years. Providing your Social Insurance Number is optional but can help accurately locate your file. This information is necessary whether you request your report online, by mail, by phone, or in person.
- Gather your personal information, including your full name and date of birth.
- Have your current address ready, and your previous address if you have lived at your current address for less than two years.
- You may provide your Social Insurance Number, though it is optional for the request.
- Complete the required request form or online fields accurately to match the bureau's records.
- Submit your request via your chosen channel, whether online, by mail, or in person.
- Wait for processing and delivery of your consumer disclosure.
- Review the report thoroughly for any inaccuracies or unfamiliar entries.
- If needed, seek help from a credit counsellor to understand the report or deal with listed debts.
Detailed Contents of the Consumer Disclosure
Your free TransUnion consumer disclosure will contain several standard sections that paint a full picture of your credit history. The report lists all your credit accounts, such as credit cards, loans, and mortgages, along with their payment histories, outlining your credit usage over time. It includes a record of credit inquiries, showing which companies have requested your information. The report also contains identifying personal information, though this may not be current as it was updated the last time you applied for credit. While the free consumer disclosure provides the detailed report, your TransUnion credit score itself may be a separate offering, often promoted through other services that advertise access to your score. The consumer disclosure helps fill in gaps if you have lost track of your credit history, giving you an overall picture of your financial situation.
How Credit Scores Are Used and Why They Vary
Your TransUnion credit score is used by lenders, creditors, landlords, and sometimes employers or insurance companies to determine the likelihood you will repay borrowed money. A score closer to 900 indicates you are less of a borrowing risk, which can make gaining access to affordable credit products and loans significantly easier. It is important to know that every bank and credit grantor also generates their own internal credit score, basing lending decisions on that plus the bureau's score and other financial information. Your credit score is not static and changes often based on new information reported to your file. Furthermore, you have more than one credit score because each credit bureau calculates it differently, and creditors may report to only one bureau, leading to potential differences between your TransUnion and Equifax scores.
Addressing Errors and Filing Disputes with TransUnion
If you find inaccuracies on your free TransUnion credit report, you have the right to dispute them. Common errors can include accounts that do not belong to you, incorrect payment statuses, or outdated personal information. To initiate a dispute, you will need to contact TransUnion directly through their online consumer solutions portal, providing details about the specific item you are challenging. The bureau is then required to investigate your dispute with the creditor who reported the information. You can also add, modify, or remove a fraud alert on your file through the same portal if you suspect identity theft. Resolving errors is important because inaccurate negative information can lower your credit score and affect your ability to obtain credit, rent a home, or even secure certain jobs.
Comparing TransUnion and Equifax Reports
It is advisable to obtain your free credit report from both major bureaus, as TransUnion and Equifax reports can differ significantly. Creditors are not required to report to both agencies, so an account may appear on one report but not the other. Each bureau uses its own scoring algorithm to calculate your credit score, which can result in different scores from TransUnion and Equifax. Furthermore, the timing of when creditors report information can cause discrepancies between the two reports. For a complete view of your credit health, you should periodically check both your free TransUnion report and your free Equifax report, as both are legally available to you at no cost. Being aware of both reports is important for your financial future, especially when planning major purchases like a home or car.
In Canada, there are two main credit bureau companies: TransUnion and Equifax. Both bureaus provide consumers with their own credit report for free. However, your credit reports from TransUnion and Equifax may not look identical. Creditors choose which bureau to report your information to, so an account may appear on only one report. Each bureau also uses its own scoring algorithm to calculate your credit score.
| Aspect | TransUnion | Equifax |
|---|---|---|
| Free Report Name | Consumer Disclosure | Credit File Disclosure |
| Free Online Frequency | Every 30 days (self-service) | By request |
| Centralized Free Source | AnnualCreditReport.com (weekly) | AnnualCreditReport.com (weekly) |
| In-Person Offices | Available in some regions | Available in some regions |
| Standard Score Range | 300 to 900 | 300 to 900 |
| Primary Use | Lending, tenancy, employment checks | Lending, tenancy, employment checks |
When and Why to Check Your Credit Report
You should check your free TransUnion credit report regularly to monitor your financial health and guard against identity theft. It is particularly wise to review your report before applying for a major loan, such as a mortgage or car loan, to ensure all information is accurate. Newcomers to Canada or young adults building credit for the first time should check their reports to understand their starting point, as a lower score can indicate a history that is 'too new to score'. If you have lost track of your credit history, the report will fill in the gaps and help give you an overall picture of your financial situation. Regular checks allow you to spot errors early and understand how your credit behaviour, like payment history and credit usage, is being recorded by the bureau. A solid credit score is a great help when you are buying your first home, getting a car loan, and it can impact where you work depending on your sector.
Frequently asked questions
How often can I get a free TransUnion credit report?
You can obtain your free TransUnion consumer disclosure every 30 days through their official self-service website. Additionally, you can use the AnnualCreditReport.com service to get your TransUnion credit report for free each week. There is no mention of an annual limit for these free official channels. It is important to note that the free option is not always the first one advertised. These methods provide you with a full consumer disclosure, which is a complete account of the information on your TransUnion file, including credit inquiries.
What is the difference between a credit report and a credit score?
A credit report is a detailed record of your credit usage and payment history, containing information used to calculate your credit score. A credit score is a three digit number between 300 and 900 that lenders use to assess your likelihood of repaying debt. Your free TransUnion consumer disclosure provides the full report, while credit scores are often marketed separately. The score is not static and changes often, and each credit bureau calculates its own score based on its algorithm and the information reported to it by your creditors.
Can I get my free TransUnion report in person?
Yes, you can request your free TransUnion credit report in person. In some provinces or territories, you can visit a TransUnion office to obtain it. This is listed as one of the available methods alongside online, mail, and phone requests. To complete the request, you will need to provide required identification and personal details. This in person option ensures you receive a copy of your consumer disclosure directly from the bureau's office.
Do I need to provide my Social Insurance Number for a free report?
Providing your Social Insurance Number is optional when requesting your free TransUnion credit report. The necessary information you must provide includes your full name, date of birth, and current address. You also need to provide a previous address if you have lived at your current address for less than two years. While providing your SIN can help accurately locate your file, it is not a mandatory requirement for obtaining your free consumer disclosure.
What should I do if I find a mistake on my TransUnion report?
If you find an inaccuracy on your free TransUnion report, you should file a dispute directly with TransUnion. You can initiate this process through their online consumer solutions portal, which is designed for tasks like disputing inaccuracies. TransUnion will investigate the dispute with the creditor who reported the information in question. It is your right to ensure the information on your consumer disclosure is correct, as it forms the basis of your credit history and score.
Why does my TransUnion report look different from my Equifax report?
Your TransUnion and Equifax reports can differ because creditors choose which credit bureau to report your information to, so an account may appear on only one report. Each bureau also uses its own scoring algorithm and receives information independently. Furthermore, personal details like your address are updated only when you apply for new credit, which can lead to discrepancies. Therefore, it is recommended to check your free report from both major bureaus in Canada to get a complete financial picture.
Sources and further reading
- How to Get Your Free TransUnion Credit Report in Canada nomoredebts.org
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.