The exchange rate between the UAE dirham (AED) and the Philippine peso (PHP) is a key financial metric for Canadians sending money to family, supporting businesses, or managing remittances between the two nations. The rate is set by global foreign exchange markets and fluctuates based on economic indicators, monetary policy, and trade flows. Canadians have several options for converting currencies, including banks, specialized transfer services, and multi-currency accounts, each with different fee structures and exchange rate markups. Understanding how the rate moves and the costs involved helps individuals and businesses get better value when moving money from AED to PHP.
Understanding the UAE Dirham and Philippine Peso
It is pegged to the US dollar at a fixed rate, which provides stability but means its value against other currencies like the peso largely follows USD movements. The Philippine peso is the official currency of the Philippines, with a history dating back to the Spanish colonial period and its modern form established after independence. Both currencies are traded actively on the global foreign exchange market, with the AED to PHP pair being particularly important for the large flow of remittances from Filipino workers in the Gulf region back to the Philippines. The exchange rate between them determines how much Philippine currency a given amount of dirhams will yield. The dirham's symbol is د.إ and its currency code is AED, while the peso uses the symbol ₱ and the code PHP.
How the AED to PHP Exchange Rate Is Set
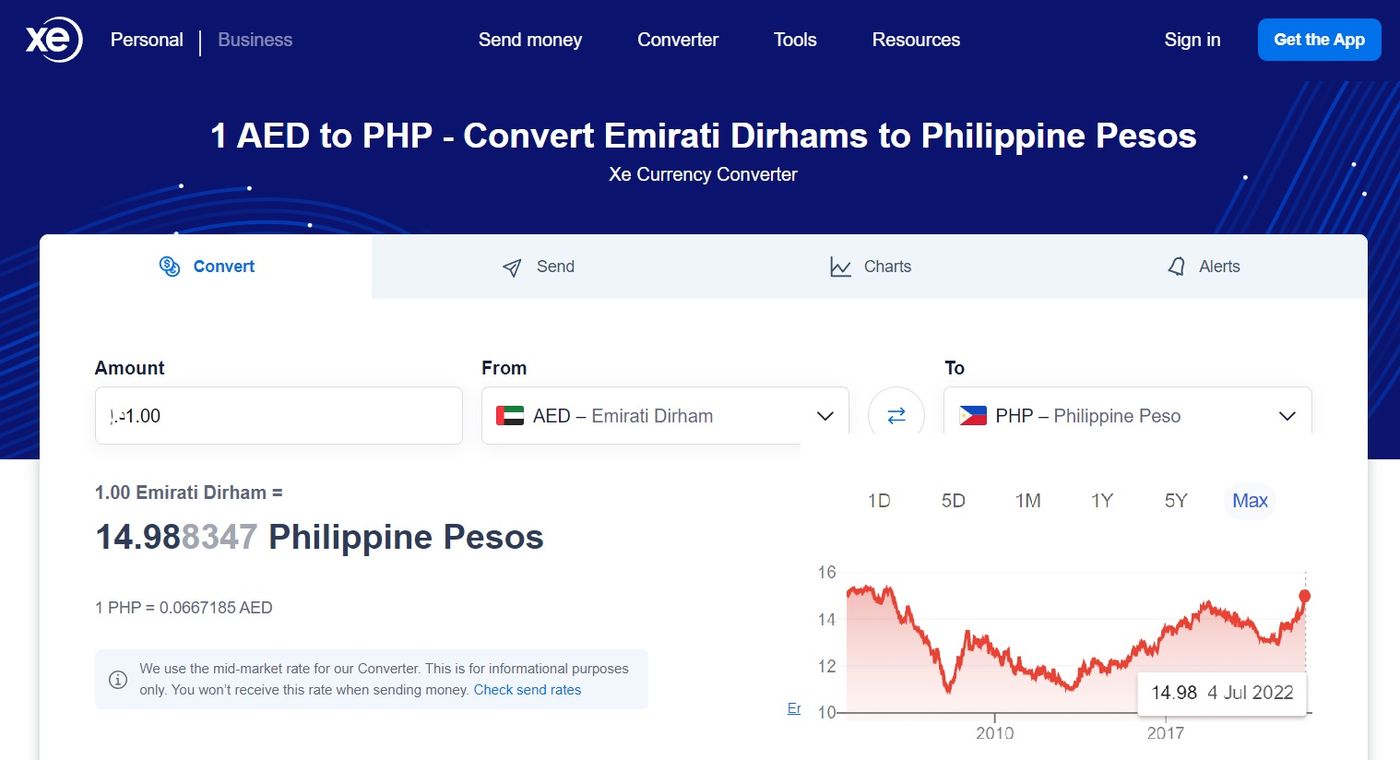
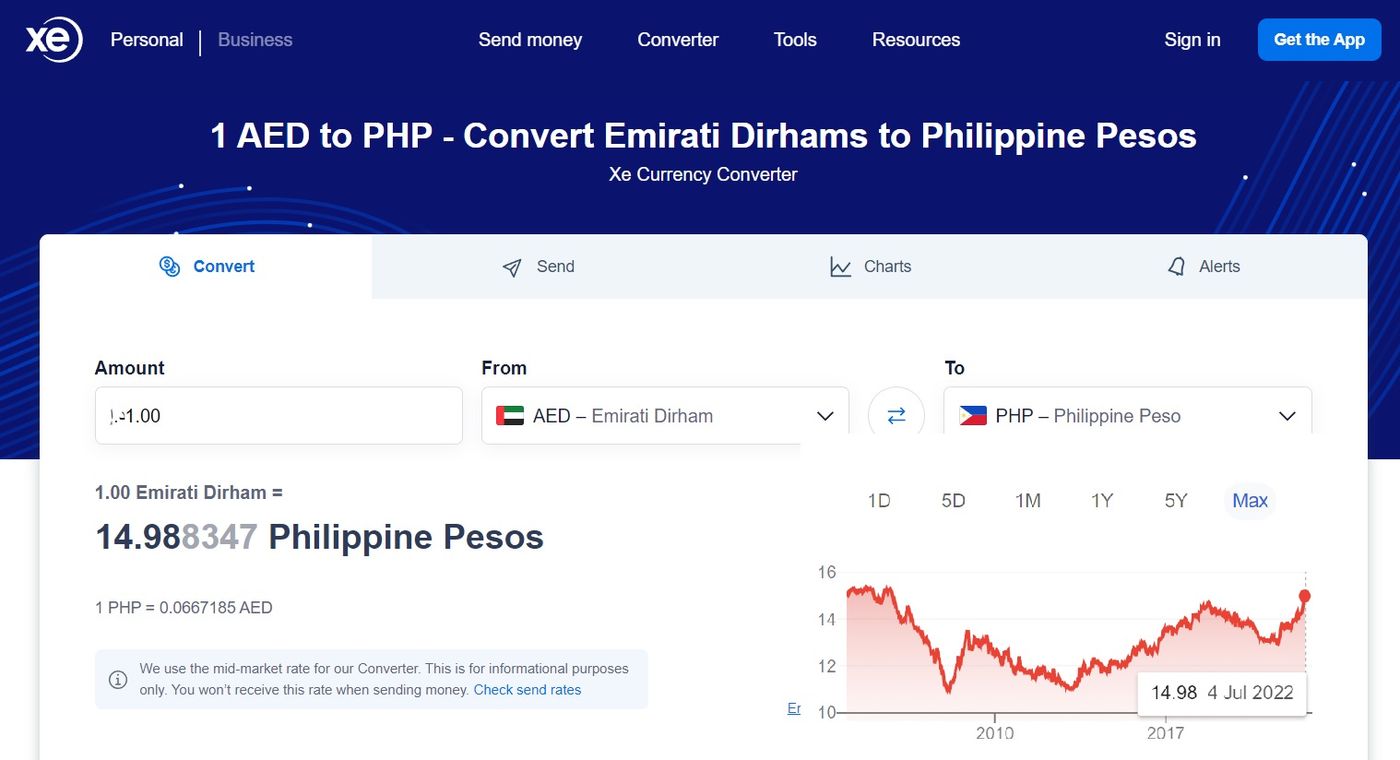
The exchange rate between the UAE dirham and the Philippine peso is determined by the foreign exchange market, where currencies are traded 24 hours a day. The most commonly referenced rate is the mid-market rate, which is the midpoint between the global buy and sell prices. This rate is purely theoretical for most consumers, as financial institutions apply their own markups. The dirham's value is directly influenced by US monetary policy due to its peg to the dollar. The peso's value is influenced by factors such as the Philippines' economic growth, inflation rates, remittance inflows, and the policies of the Bangko Sentral ng Pilipinas. Trade balances and geopolitical events in both regions can also cause the rate to move. The rate you see quoted on live charts from services like Xe or Wise reflects this real-time mid-market price, which serves as the baseline for all retail currency conversions.
Historical Performance and Notable Rate Movements
The AED to PHP exchange rate has experienced fluctuations over time, reflecting economic conditions in both countries. In recent observation periods, the rate has moved within a range, demonstrating typical foreign exchange volatility. For a 90-day period in 2026, the rate reached a high of 17.2401 pesos per dirham and a low of 16.5283 pesos per dirham, with an average of 16.9295. The overall change over that period was 2.55 percent. Over a 30-day period in the same year, the high was 17.2401 and the low was 16.9861, with an average of 17.0848 and a change of 0.89 percent. These movements highlight that even with the dirham's dollar peg, the pair can experience notable shifts based on peso market dynamics. Over a seven-day period, the range was between 17.0907 and 17.1748, with an average of 17.1388 and volatility of 0.12 percent. Tracking these highs and lows is a common practice for those waiting to send money when the rate is favourable.
Methods for Canadians to Convert AED to PHP
Canadians looking to convert UAE dirhams to Philippine pesos have several channels available, each with distinct cost structures. Traditional Canadian banks offer currency conversion services, but they typically add a significant markup to the mid-market rate and may charge additional transfer fees. Specialized foreign exchange platforms and money transfer services often provide more competitive rates and clearer fee schedules. These services operate online and through apps, allowing users to lock in rates and track transfers. Multi-currency accounts offered by some fintech companies enable users to hold and convert dirhams and pesos directly, sometimes at or near the mid-market rate. The choice of method significantly impacts the final amount received in pesos. Services like Western Union facilitate transfers through their website, app, or in-person agent locations, focusing on speed for cash pickup. Digital providers like Venn offer business accounts that can hold multiple currencies including CAD, USD, GBP, and EUR, and allow for conversions with what they advertise as competitive rates.
Fees and Charges from Financial Providers
When converting currency, the total cost is a combination of the exchange rate margin and any fixed or variable fees. Banks commonly profit from the spread, which is the difference between their buy and sell rates, and this cost is often hidden within the offered exchange rate. Many banks also charge wire transfer fees for sending money internationally. Specialized transfer services may advertise low or no transfer fees but might still incorporate a margin into their exchange rate. Transparent providers explicitly show the mid-market rate they use and list a separate, upfront fee for the transaction. Canadians should always look for full cost disclosure before initiating a transfer to understand exactly how many pesos will be delivered for their dirhams. A comparison example from 2026 showed that for a single large transfer, using a service like Xe could provide bank-beating rates and no hidden fees compared to traditional banks, though savings vary based on amount, timing, and currency. It is crucial to verify that the quoted rate and fees are for the specific transaction, as they can change based on payment method and transfer size.
Detailed Comparison of Transfer Services and Platforms
Different service providers cater to the AED to PHP transfer market with varying features, coverage, and business models. Digital-first companies like Wise and Xe emphasize using the real mid-market exchange rate and charging transparent, upfront fees, with Wise supporting transfers in over 40 currencies and Xe supporting 130 currencies across 190 countries. Fintech platforms such as Venn provide multi-currency business accounts that allow companies to hold dirhams and pesos and convert between them, often with integrated features for managing international payments, payroll, and API integrations with accounting software. Venn is a technology company and not a bank, and its account balances are held at the Bank of Montreal with CDIC deposit insurance eligibility up to applicable limits.
Canadians should compare key features when choosing a service to convert UAE Dirhams to Philippine Pesos. It is important to look for platforms that offer full transparency by showing the actual exchange rate and any separate transfer fees upfront. Specialized foreign exchange platforms can offer better mid-market rates compared to banks, which often charge higher spreads or hidden fees. Canadians should always verify current rates directly with a provider before making a transaction, as exchange rates and fees are subject to change.
- The exchange rate offered relative to the live mid-market rate, avoiding hidden markups.
- The structure and amount of any transfer fees, which may be fixed or a percentage.
- The speed of delivery, which can range from minutes for cash pickup to several business days for bank deposits.
- Transfer methods, such as bank deposit, cash pickup, or mobile wallet credit.
- Customer support channels and real-time payment tracking capabilities through apps or websites.
- Eligibility requirements, supported countries, and whether the service is registered as a money service business with FINTRAC in Canada.
- For businesses, additional features like batch payments, multi-user access, and FX risk management tools.
Some business-oriented money transfer services offer the ability to open free local accounts in currencies like CAD, USD, GBP, and EUR. These accounts allow users to send and receive payments via local rail systems such as EFT, ACH, SEPA, UK Faster Payments, and Interac. Using these local payment networks can help businesses avoid international transfer fees. This functionality is part of a suite of finance products designed to save businesses both time and money on their international transactions.
Regulatory and Security Considerations for Transfers
When sending money internationally from Canada, it is important to use providers that operate within the regulatory framework. In Canada, money service businesses must be registered with the Financial Transactions and Reports Analysis Centre of Canada (FINTRAC). For instance, Venn Software Inc. is registered under FINTRAC number M22941967. Funds held in certain multi-currency accounts may be eligible for deposit insurance. Venn account balances are held at the Bank of Montreal and are eligible for Canada Deposit Insurance Corporation (CDIC) coverage up to applicable limits. Providers use encryption and fraud prevention systems to protect transfers, and they require customer identity verification as part of anti-money laundering protocols. Canadians should be aware that transfer speeds and service availability can be affected by factors including the amount sent, destination country regulations, currency availability, agent location hours, and time zone differences. Some services are not available in all provinces. For example, Venn noted it was not available to businesses in Quebec as of 2026.
Practical Steps for Converting and Sending Currency
To convert UAE dirhams to Philippine pesos, a user typically starts by selecting a provider and registering for an account, which involves identity verification for security and regulatory compliance. The next step is to initiate a new transfer, specifying the amount in dirhams to send and selecting Philippine pesos as the target currency. The provider will then quote an exchange rate and outline all applicable fees, showing the final amount in pesos that the recipient will get. After the user confirms and pays for the transfer, the provider executes the conversion and sends the funds. The recipient in the Philippines can receive the money via bank deposit, cash pickup at an agent location, or directly into a mobile money account. Users can usually track the transfer's progress online or through a mobile app. For regular transfers, many services allow you to save recipient details and set up rate alerts to be notified when the AED to PHP rate reaches a desired level. It is advisable to compare the final delivery amount across multiple providers before committing to ensure you are getting a good value for your dirhams.
Tools and Features for Managing Currency Risk
Both individuals and businesses can use various tools to manage the risk of exchange rate fluctuations between the dirham and the peso. A fundamental tool is the rate alert, offered by many currency converters and transfer services, which sends a notification when the mid-market rate hits a user-specified target. Historical charts, which can show data for up to five years, help users understand long-term trends and volatility. For businesses with regular obligations, some platforms offer forward contracts or hedging solutions that lock in an exchange rate for a future date, providing budget certainty. Multi-currency accounts allow businesses to hold a balance in dirhams and convert to pesos when the rate is favourable, rather than at the time an invoice is due. Integrating these accounts with accounting software helps consolidate financial management. The ability to make same-day transfers and have real-time quotes is also a valuable feature for reacting quickly to market movements.
Frequently asked questions
What is the mid-market exchange rate for AED to PHP?
The mid-market rate is the real-time benchmark exchange rate set by the global currency markets, representing the midpoint between the buy and sell prices. It is the rate you see on financial data websites and is used as a reference point. When you convert money through a bank or transfer service, you will not receive this exact rate, as providers add a margin or spread. Always compare the rate you are offered against the live mid-market rate to understand the cost of your transaction.
How can I get the best exchange rate when sending money to the Philippines?
To get the best rate, compare offers from multiple providers, including banks, online money transfer specialists, and fintech platforms. Look for services that use or closely approximate the mid-market rate and are transparent about their fees. Avoid providers that only show you the final amount without disclosing the rate and fee separately. Specialized foreign exchange services often offer better rates than traditional banks for larger transfer amounts. Setting up a rate alert can also help you send money when the market rate is favourable.
Are there hidden fees when converting AED to PHP?
Fees can be hidden if a provider does not clearly separate the exchange rate margin from a fixed transfer fee. A common practice is to offer a rate that is worse than the mid-market rate, with the difference acting as the provider's profit. Reputable services will show you the mid-market rate they use and list any transfer fee upfront before you confirm the transaction. Always review the full breakdown of costs, including any receiving fees that might be charged by banks in the Philippines.
How long does an international money transfer from AED to PHP take?
Transfer times vary by provider and method. Some services offer transfers that can be completed in minutes for cash pickup at agent locations. Transfers directly to a Philippine bank account may take one to three business days. The speed can depend on the payment method used to fund the transfer, the currencies involved, and the service's processing times. Most providers give an estimated delivery time when you get a quote for your transfer.
Can I set up a recurring transfer from UAE dirhams to Philippine pesos?
Many money transfer services and multi-currency account platforms allow you to schedule recurring transfers. This is useful for regular obligations like sending monthly support to family. You can typically set the frequency, amount, and recipient details. The exchange rate for each transfer will be the rate at the time the transaction is processed, unless you use a service that allows you to lock in a rate in advance for future dates.
What should I look for in a service for business transfers from AED to PHP?
For business transfers, look for services that offer dedicated business accounts, support for batch payments, and the ability to handle larger transaction volumes. Integration with accounting software and detailed reporting are valuable features. Competitive, transparent FX rates are crucial for cost management, and reliable customer support is important for resolving any issues promptly. Some platforms provide tools for hedging against currency risk, which can be important for businesses with regular international payments.
Sources and further reading
- Convert UAE Dirham to Philippine Peso Today venn.ca
- United Arab Emirates dirhams to Philippine pesos today wise.com
- Convert United Arab Emirates Dirham to Philippine Peso westernunion.com
- 1 AED to PHP, Convert Emirati Dirhams to Philippine Pesos xe.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.