The money market is a crucial segment of the financial system where short-term borrowing and lending occur, with instruments maturing in one year or less. In Canada, it provides liquidity for the economy, influences interest rates, and offers investment vehicles like money market funds. The Bank of Canada uses the overnight rate target as its primary monetary policy tool, directly affecting this market. Understanding the money market is key for investors, businesses, and anyone following the country's economic health.
What Is the Money Market
The money market is a component of the financial system dedicated to short-term borrowing, lending, buying, and selling of assets with original maturities of one year or less. It deals in highly liquid, low-risk securities, providing a marketplace for participants to manage short-term cash needs and surpluses. This market is wholesale and primarily operates over the counter, meaning trades occur directly between parties rather than on a centralized exchange. Its primary purpose is to provide liquidity for the global financial system, including capital markets. The instruments traded bear differing maturities, currencies, credit risks, and structures, but all share the characteristic of short-term duration. In contrast, the capital market supplies longer-term funding through instruments like bonds and equity.
How the Money Market Works
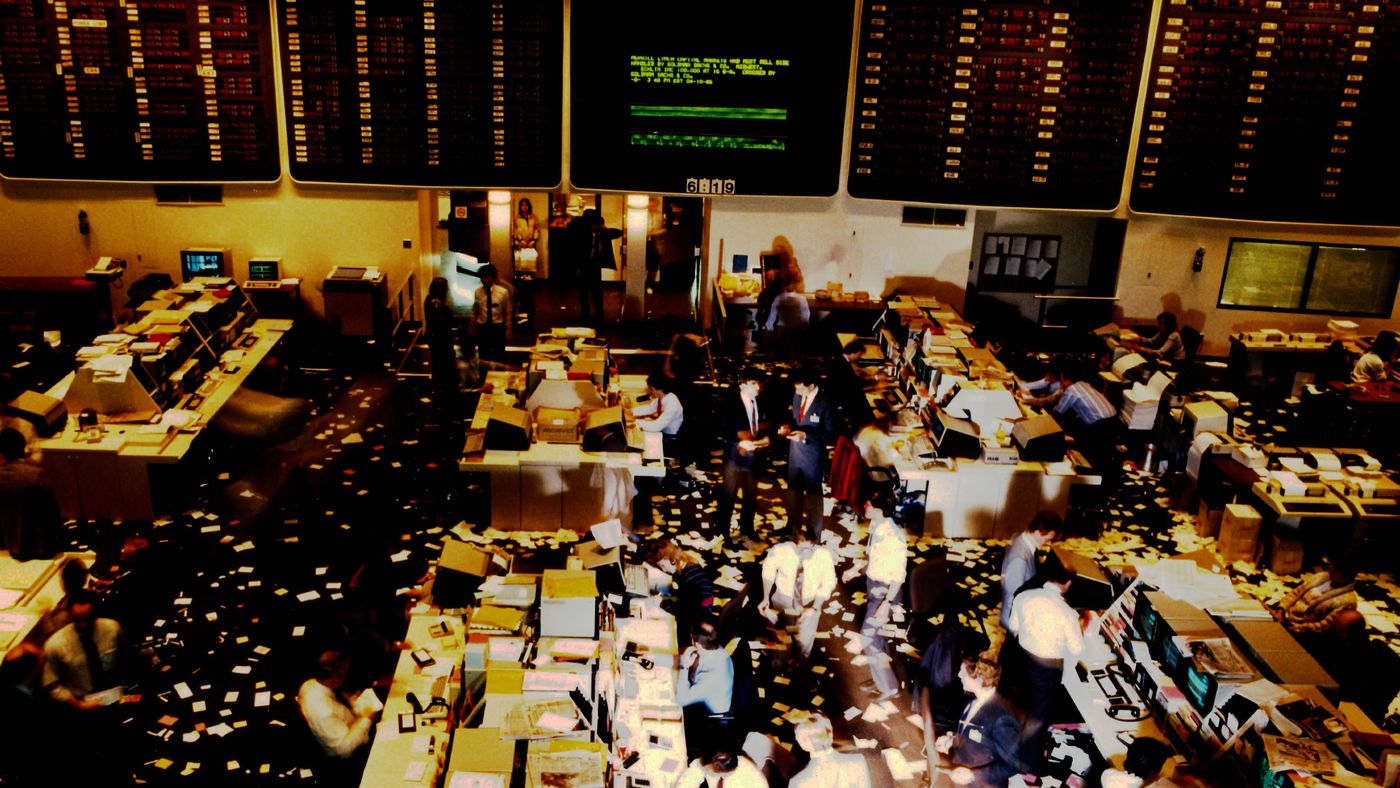
The money market functions through a network of financial institutions and dealers who borrow and lend for short periods, typically up to twelve months. Trading involves financial instruments commonly called paper, such as commercial paper and repurchase agreements. The core of the market involves interbank lending, where banks lend to and borrow from each other to manage daily liquidity needs and cover transactions. In Canada, major financial institutions settle large electronic transactions through the Large Value Transfer System, leading to an overnight market where they borrow and lend to balance their positions. The interest rate charged on these overnight loans is a central element of the system. The Bank of Canada sets a target for this overnight rate and maintains an operating band around it to guide market rates. This target is the Bank's main tool for conducting monetary policy, influencing other short-term interest rates throughout the economy.
Money markets serve several key functions in the economy. They finance trade by making commercial finance available through instruments like bills of exchange. They help finance industry by providing short-term loans for working capital needs and influencing long-term interest rates in the capital market. They enable commercial banks to invest excess reserves profitably while maintaining liquidity to meet depositor demands. Developed money markets also help commercial banks become more self-sufficient, allowing them to recall short-term loans from the market instead of borrowing from the central bank in an emergency. Finally, they assist central bank policy by providing immediate interest rate signals, enabling efficient policy implementation, and facilitating market-based liquidity management among financial institutions.
Money Market Instruments
Money market instruments are short-term debt securities that provide a means for governments, financial institutions, and corporations to raise funds. They are characterized by high credit quality and short maturities, making them relatively low-risk investments. In Canada, common instruments include Treasury bills issued by the federal government, commercial paper issued by corporations, and banker's acceptances used in trade financing. Repurchase agreements, or repos, are short-term loans arranged by selling securities with an agreement to repurchase them later. Certificates of deposit are time deposits offered by banks to consumers. Money market mutual funds pool investor money to purchase a diversified portfolio of these instruments. These instruments can be structured as discount instruments, issued at a discount to face value and redeemed at face value, or accrual instruments, issued and redeemed at face value with interest paid at maturity.
- Treasury Bills: Short-term government securities with maturities from four to 52 weeks.
- Commercial Paper: Short-term promissory notes issued by companies at a discount.
- Banker's Acceptances: Instruments used to finance trade, guaranteed by a bank.
- Repurchase Agreements: Short-term collateralized loans, often overnight.
- Certificates of Deposit: Time deposits offered by banks and credit unions.
- Money Market Mutual Funds: Pooled funds that invest in a portfolio of money market securities.
- Federal Funds: In the U.S., interest-bearing deposits held at the Federal Reserve.
- Municipal Notes: Short-term notes issued by municipalities in anticipation of revenues.
The Money Market in Canada
The Canadian money market is integral to the nation's monetary policy and financial stability. The Bank of Canada targets the overnight money market rate as its primary policy tool to influence inflation and economic activity. This target rate signals the desired average interest rate for one-day loans between major financial institutions. The Bank enforces this target through an operating band, typically half a percentage point wide, and stands ready to lend at the top of the band and pay interest on deposits at the bottom. Changes to this target directly affect other short-term interest rates, including the prime rates set by commercial banks, which in turn influence mortgage rates and savings account yields. The Canadian Overnight Repo Rate Average (CORRA) is a key benchmark, representing the weighted average rate of overnight general collateral repo trades. Money market funds in Canada are regulated under National Instrument 81-102, which sets standards for their designation and operation, focusing on capital preservation and liquidity.
Canadian money market funds are mutual funds or exchange-traded funds that invest in high-quality, short-term debt securities. Their fundamental objective is to earn interest income while preserving capital and maintaining liquidity. They typically invest in securities maturing in less than one year, such as federal and provincial government Treasury bills and high-grade commercial paper. These funds aim to maintain a stable net asset value per unit, though this is not guaranteed. Investors pay management fees, generally between 0.2 and 1.5 percent, and there may be minimum investment requirements. Performance is often measured by a seven-day annualized yield. For example, the RBC Canadian Money Market Fund reported a current yield of 2.2 percent with an average term to maturity of 77 days. These funds provide retail and institutional investors with a way to access the professional management of money market instruments.
Money Market Funds vs. Savings Accounts
Money market funds and high-interest savings accounts are both popular choices for Canadians seeking safety and some return on cash holdings, but they differ in structure, risk, and regulation. Money market funds are a type of mutual fund that invests in short-term government and corporate debt. They aim to preserve capital and provide steady income, with easy access to cash. However, they carry investment risk, as their unit price can fall, and returns are reduced by the management expense ratio. They are not covered by deposit insurance. In contrast, a high-interest savings account is a bank deposit product that typically pays a higher interest rate than a regular savings account. Interest is calculated daily and paid monthly. These accounts offer easy access with no fees, lock-in periods, or minimum deposits. Crucially, deposits in these accounts are protected up to applicable limits by the Canada Deposit Insurance Corporation.
| Feature | Money Market Fund | High-Interest Savings Account |
|---|---|---|
| Product Type | Mutual fund or ETF | Bank deposit account |
| Primary Objective | Interest income with capital preservation | Interest income with capital preservation |
| Risk to Principal | Price can fall. Not guaranteed | No risk of loss on initial investment |
| Deposit Insurance | Not covered by CDIC | Covered by CDIC up to limits |
| Fees | Management fees (e.g., 0.2% to 1.5%) | Typically no fees |
| Return Mechanism | Fund performance net of fees | Declared interest rate |
| Liquidity | High, but subject to fund terms | High, with immediate access |
Risks and Considerations
While money markets are considered low-risk relative to other financial markets, they are not without risks. The primary risk for investors in instruments like money market funds is that the net asset value per unit is not guaranteed to remain constant. Although rare, there is a possibility that the value could fall, meaning an investor may not get the full amount of their investment back. This is known as breaking the buck. Furthermore, returns are subject to management fees and expenses, which reduce net yield. For participants like banks and finance companies, liquidity risk and counterparty credit risk are always present, especially during periods of financial stress. The market relies heavily on the smooth functioning of interbank lending and the stability of short-term credit ratings. In Canada, the Bank of Canada's management of the overnight rate and its operating band is designed to mitigate systemic liquidity risks and ensure the market functions smoothly, but external shocks can still disrupt conditions.
Another consideration is interest rate risk. While short-term instruments are less sensitive to interest rate changes than long-term bonds, rising rates can cause the market value of existing fixed-rate money market securities to decline slightly. Furthermore, money market funds, while aiming for stability, do not offer the government-backed deposit insurance that savings accounts do. This trade-off means investors accept a small degree of risk in exchange for potentially higher yields than insured deposits. The performance of money market funds and the overall health of the money market are closely tied to the Bank of Canada's monetary policy decisions. When the Bank raises or lowers its target for the overnight rate, it directly affects the yields on money market instruments and the returns investors can expect from related funds.
Frequently asked questions
What is the money market rate in Canada?
The key money market rate in Canada is the target for the overnight rate set by the Bank of Canada. This is the interest rate the Bank wants to see for one-day loans between major financial institutions. Other important rates include the Canadian Overnight Repo Rate Average (CORRA) and yields on Government of Canada Treasury bills with maturities from one month to one year. These rates are influenced by monetary policy and economic conditions.
How does the Bank of Canada use the money market?
The Bank of Canada uses the overnight money market as the primary channel for monetary policy. By setting and maintaining a target for the overnight rate, the Bank influences short-term interest rates throughout the economy. It operates a system with an operating band to keep market trading near this target. Changes to this target rate signal the Bank's policy direction and affect commercial bank lending rates, mortgage rates, and savings yields, thereby influencing borrowing, spending, and inflation.
What is a money market fund in Canada?
A money market fund in Canada is a type of mutual fund or exchange-traded fund that invests in high-quality, short-term debt securities like government Treasury bills and corporate commercial paper. These funds aim to preserve capital, provide liquidity, and generate interest income. They are regulated under National Instrument 81-102. Investors should be aware they pay management fees, and unlike bank accounts, these funds are not covered by Canada Deposit Insurance Corporation protection.
Are money market funds safe?
Money market funds are considered low-risk investments focused on capital preservation, but they are not guaranteed. Their unit price aims to remain stable, but there is a risk it could fall, meaning you might not get your full investment back. They are not insured by the Canada Deposit Insurance Corporation. In contrast, high-interest savings accounts at banks are CDIC-insured up to limits and carry no risk to the principal amount deposited.
What is the difference between the money market and capital market?
The money market deals with short-term borrowing and lending, with instruments maturing in one year or less, such as Treasury bills and commercial paper. It provides liquidity. The capital market deals with long-term funding through instruments like bonds and equity, with maturities exceeding one year. It provides capital for investment. The short-term interest rates in the money market influence the long-term rates in the capital market.
What are examples of money market instruments?
Common money market instruments include Treasury bills, commercial paper, banker's acceptances, deposits, certificates of deposit, bills of exchange, repurchase agreements, federal funds, and short lived mortgage and asset backed securities. These instruments are used for short term borrowing, lending, buying and selling with original maturities of one year or less. In Canada, Government of Canada Treasury bills are a primary instrument with regular maturities ranging from 4 to 52 weeks. Other examples relevant to the Canadian market include provincial government paper, such as from Quebec or Alberta, and the Canadian Overnight Repo Rate Average which is a key benchmark rate.
Sources and further reading
- Money market (Wikipedia) en.wikipedia.org
- Money market yields bankofcanada.ca
- RBC Canadian Money Market Fund, RBF271 rbcgam.com
- Canada Money Market Rate economy.com
- TD Canadian Money Market Fund, I (TDB164) | TDAM td.com
- Money market funds vs. savings accounts canadalife.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.