Investing in gold in Canada involves several methods, including buying physical bullion, purchasing shares in gold-focused exchange-traded funds (ETFs), or investing in gold mining company stocks. Gold is often considered by Canadian investors for portfolio diversification and as a potential hedge against inflation and currency fluctuations. Each investment method carries distinct costs, risks, and tax implications that must be understood. This guide explains the available options and key considerations for adding gold to a Canadian investment portfolio.
Why Canadian Investors Consider Gold
Gold has historically served as a store of value, particularly during periods of economic uncertainty. For Canadian investors, gold can play a specific role in an investment portfolio by providing diversification. Its price often moves independently of traditional assets like stocks and bonds, which can help reduce overall portfolio volatility. During times of market stress, such as the COVID-19 pandemic period from February to May 2020, gold prices have shown resilience when equity markets declined. Furthermore, gold is widely regarded as a hedge against inflation, as its price tends to rise when the purchasing power of currency declines, helping to preserve wealth over the long term.
The value of gold for Canadians is also influenced by currency movements. Gold is predominantly priced in U.S. dollars, so a weaker Canadian dollar relative to the U.S. dollar can increase the Canadian-dollar value of gold holdings. This currency effect has been a notable factor for investors over the past decade. Gold does not generate income like dividends or interest, meaning its primary function is capital preservation rather than growth. Investors typically allocate a small portion of their portfolio to gold to mitigate risks from other asset classes, not to seek high returns.
Historical data illustrates gold's diversification benefits. Analysis of returns in Canadian dollars shows that from December 2007 to June 2009 during the Global Financial Crisis, gold provided positive returns while major equity indices declined. Similarly, in the first months of the COVID-19 crisis, the S&P GSCI Gold Spot Index performed well. The statistical correlation between gold and other major asset classes like Canadian equities, U.S. equities, and Canadian bonds is often low or negative, meaning they do not move in lockstep. This inverse relationship is precisely what makes gold a useful tool for smoothing portfolio returns during economic downturns.
Key Factors That Influence the Price of Gold
Several interconnected economic and geopolitical factors drive the price of gold, which is crucial for investors to understand. Inflation and the general cost of living are primary drivers, as gold is sought after to preserve purchasing power when currency values fall. Interest rates also have a significant impact, particularly real interest rates which are adjusted for inflation. When real interest rates are low or negative, the opportunity cost of holding non-yielding assets like gold decreases, making it more attractive to investors. Historical data from 1977 to 2025 shows gold prices tend to move inversely to real U.S. interest rates.
Geopolitical uncertainty, such as international conflicts or trade disputes, often triggers demand for gold as a safe-haven asset. Central bank activity is another major factor, as institutions like the Bank of Canada and others hold gold reserves and their purchasing patterns can signal confidence and affect global supply. Finally, the strength of the U.S. dollar is critical since gold is dollar-denominated a weaker dollar makes gold cheaper for international buyers and can increase demand. Canadian investors must also consider the CAD/USD exchange rate, as it directly affects the returns on their gold investments when converted back to Canadian dollars.
The supply and demand dynamics for gold are unique because it is a finite resource. New mine supply takes time to develop, and recycling from existing jewellery and industrial sources contributes to annual supply. On the demand side, investment demand through products like ETFs and central bank purchases has grown significantly in recent years. Industrial and technological demand, while smaller than investment demand, also plays a role. The combined effect of these factors means gold prices can be volatile in the short term, responding to news and economic data, but over the long term, its scarcity is a fundamental part of its value.
Methods for Investing in Gold in Canada
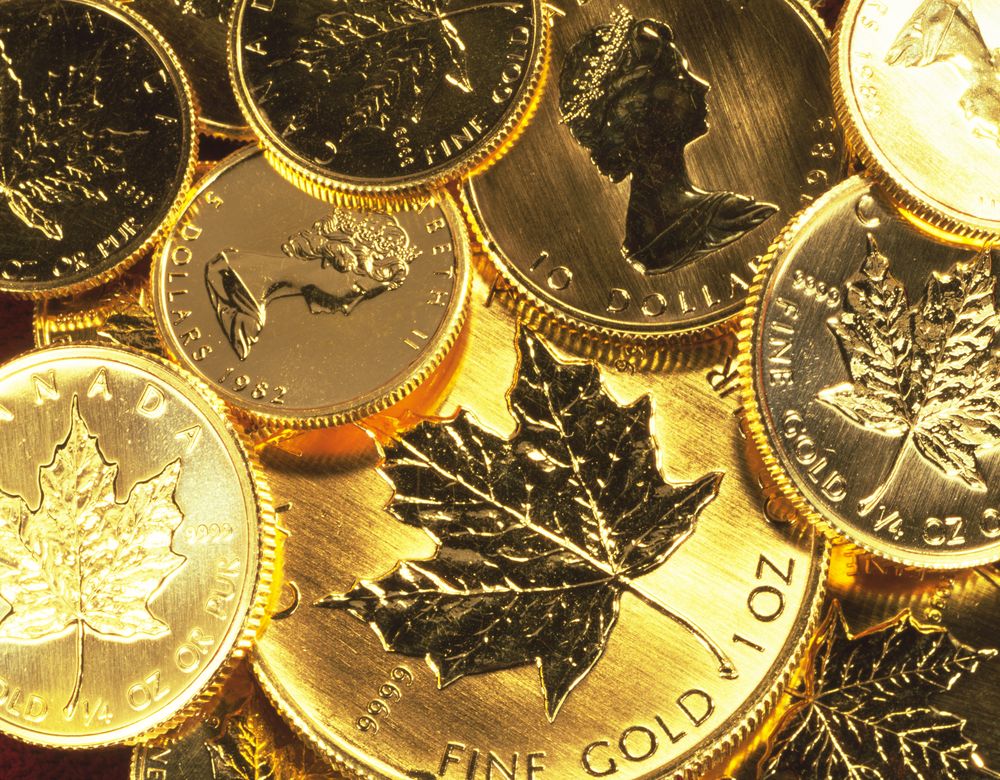
Canadian investors have multiple avenues to gain exposure to gold, each with different characteristics regarding ownership, cost, and complexity. The most direct method is purchasing physical gold bullion, which includes bars, coins, and rounds from dealers or banks. Products like the Canadian Maple Leaf coin are popular, and institutions like TD Bank offer bullion for delivery or secure storage. Physical ownership means you hold the asset directly, but it involves costs for storage, insurance, and a premium over the spot price upon purchase. Another method is investing in gold exchange-traded funds (ETFs) such as the iShares Gold Bullion ETF, which trades on the Toronto Stock Exchange and provides exposure without the need for physical storage.
For those seeking direct beneficial ownership of physical gold without taking delivery, the Royal Canadian Mint offers Exchange-Traded Receipts (ETRs) under the symbols MNT and MNT.U. These ETRs represent a direct interest in gold bullion stored at the Mint and are backed by the Government of Canada. Investors can also buy shares in gold mining companies like Barrick Gold or Agnico Eagle, which offer leveraged exposure to gold prices but carry additional operational risks. Finally, precious metal certificates are available through some financial institutions like TD Wealth, allowing ownership of gold in electronic form without physical possession. The table below outlines a comparison of the primary investment methods available to Canadians.
| Investment Method | Ownership Type | Key Features | Common Costs/Fees |
|---|---|---|---|
| Physical Bullion | Direct physical ownership | Bars, coins. Requires secure storage | Premium over spot (3-8% for coins), storage fees |
| Gold ETFs (e.g., CGL) | Indirect via fund shares | Trades on TSX, highly liquid | Management Expense Ratio (MER 0.35-0.50%) |
| Mining Stocks | Equity in a company | Leveraged to gold price, pays dividends | Brokerage commissions, market volatility |
| Mint ETRs (MNT) | Direct beneficial ownership | Backed by Government of Canada, redeemable | Management fees, trading commissions |
| Precious Metal Certificates | Electronic claim on metal | No physical storage needed | Issuer fees, potential spread on buy/sell |
Beyond these common methods, investors can also consider gold-focused mutual funds or futures contracts, though these are generally more complex and suited for experienced investors. Futures involve leverage and carry significant risk of loss. Some online dealers, such as Silver Gold Bull Canada and AU Bullion, specialize in selling physical bullion directly to retail investors with transparent pricing. It is important to understand that each method represents a different type of claim on gold, from direct physical possession to a derivative financial contract, and this fundamentally changes the risk profile of the investment.
Detailed Costs, Storage, and Transaction Considerations
Every method of gold investing involves specific costs that impact the overall return. When buying physical gold, investors pay a premium over the current market spot price, which covers minting, distribution, and dealer margins. Premiums typically range from 1% to 4% for bars and 3% to 8% for popular coins like the Canadian Maple Leaf. Upon selling, dealers usually buy back at or slightly below the spot price, creating a transaction cost spread. Secure storage is another critical cost factor for physical holders, with options including home safes, bank safety deposit boxes, or professional vaulting services like those offered by Brink's in major Canadian cities.
For paper gold investments like ETFs and ETRs, the primary cost is the annual management expense ratio. Gold ETFs commonly charge between 0.35% and 0.50% annually. These products also involve standard brokerage commissions to buy and sell shares on an exchange. The Royal Canadian Mint's ETRs have their own fee structure for management and administration. Mining stock investors face brokerage fees and are exposed to the volatility and specific risks of the mining industry. It is important for investors to account for all these costs, including potential tax implications, when calculating the net benefit of holding gold in their portfolio.
Storage solutions for physical gold vary in security and cost. TD Bank offers a service called TD Secure Storage, available only to its customers, for metals purchased through them. The Royal Canadian Mint stores the gold backing its ETRs in its own high-security vaults, with the Mint bearing the risk of physical loss or damage. For individuals storing gold at home, considerations include the cost of a quality safe and the potential need to add a rider to your home insurance policy, which will increase premiums. Professional vault storage, while more expensive, provides institutional-grade security, often with full insurance, but adds an ongoing annual fee that can erode returns on smaller holdings.
Tax Implications and Registered Account Eligibility
The tax treatment of gold investments in Canada depends on the form of ownership and the account type used. Losses can be used to offset other capital gains. Precious metal certificates and ETRs are also subject to capital gains tax upon disposal. Specific rules apply for holding gold within registered accounts like Tax-Free Savings Accounts (TFSAs) and Registered Retirement Savings Plans (RRSPs). Physical gold bullion itself is generally not eligible to be held directly in these accounts unless it meets specific Canada Revenue Agency criteria regarding purity and storage.
However, many gold-based financial products are eligible for registered accounts. Gold ETFs and ETRs that are listed on designated stock exchanges, like the Toronto Stock Exchange, can be held within a self-directed TFSA or RRSP. Shares of gold mining companies are also eligible as they are typical equity investments. Holding gold within a TFSA allows any growth to be tax-free, while within an RRSP, growth is tax-deferred until withdrawal. Investors should consult a tax advisor for personalized advice, especially regarding the declaration of capital gains or losses when selling precious metals back to a dealer or financial institution.
The CRA rules for holding physical gold in an RRSP are strict. The bullion must be of a minimum purity, typically .995 fine for gold, and it must be produced by a government mint or other approved entity. It must also be stored by a qualified custodian, not by the account holder personally. In practice, this makes holding physical coins or bars directly in an RRSP complex and uncommon. The more practical route for registered account exposure is through the listed securities like ETFs and ETRs. It is crucial to understand that selling any gold investment, whether from a registered or non-registered account, may trigger a taxable event, and proper records of purchase dates and costs must be kept.
Common Risks and Investor Misconceptions
Investing in gold carries specific risks that differ from traditional equities and bonds. A primary risk is price volatility. While gold is considered a safe haven, its price can experience significant swings based on the factors previously discussed. Gold mining stocks are particularly volatile due to their leveraged exposure to gold prices and operational risks like production costs, political risk in mining jurisdictions, and management decisions. Physical gold carries risks of theft, loss, and the cost of secure storage, which can erode returns. For paper gold products like ETFs, there is a counterparty risk, as the investor relies on the fund issuer to hold the underlying asset.
Several misconceptions surround gold investing. One is viewing gold purely as a short-term trading vehicle for quick profits. Its historical role is better suited as a long-term diversifier for wealth preservation. Another is treating jewellery as an investment, as it carries high retail markups and low resale value relative to its gold content. Investors may also overlook the total cost of ownership, including premiums, storage fees, and management expenses, which can significantly impact net returns. Finally, expecting gold to generate income like dividends is a misunderstanding, as it is a non-yielding asset whose value is derived from price appreciation and its hedging properties.
A specific risk for paper gold investments is the potential disconnect between the product's price and the underlying metal in extreme market conditions. While rare, an ETF could theoretically fail to accurately track the spot price if liquidity dries up. The Royal Canadian Mint emphasizes that its ETRs provide direct beneficial ownership, which differs from a fund structure, potentially mitigating some of this structural risk. Another common mistake is over-allocating to gold based on fear or hype. Financial experts generally suggest only a small allocation, as gold's long-term growth potential is limited compared to productive assets like equities. Understanding that gold is a defensive, insurance-like asset is key to using it appropriately within a broader financial plan.
Steps for Canadian Investors Getting Started with Gold
For Canadians interested in adding gold to their portfolio, a systematic approach helps in making an informed decision. The first step is to define your investment objective. Determine whether you seek diversification, inflation protection, or a safe-haven asset, as this will influence which gold investment method is most suitable. The second step is to research the specific products available. Compare the features of physical bullion, ETFs like iShares Gold Bullion ETF (CGL), Mint ETRs (MNT), and shares of major Canadian gold miners. Consider factors such as liquidity, costs, and how each product aligns with your objective.
The third step is to understand the full cost structure. For any product, calculate the total cost of ownership, including upfront premiums or commissions, ongoing management or storage fees, and the expected spread when you eventually sell. The fourth step is to decide on a purchase and storage plan. If buying physical metal, select a reputable dealer or bank, and arrange for secure storage in advance. If buying securities, ensure your brokerage account is funded and understand the trading process. The fifth step is to monitor your investment in context. Track the performance of your gold holding relative to your overall portfolio and rebalance if your allocation drifts significantly from your target due to price movements.
It is advisable to consult with a financial advisor or tax professional, especially for larger investments or when using registered accounts. Keep detailed records of all transactions, including purchase receipts for physical gold and trade confirmations for securities, as these are essential for accurate tax reporting. Finally, maintain a long-term perspective. Gold is not typically a buy-and-sell frequently asset. Review your gold investment annually as part of your overall financial plan, adjusting only if your goals or financial circumstances change substantially.
Frequently asked questions
Can I buy physical gold from a Canadian bank?
Yes, several major Canadian banks, including TD Bank, offer physical gold bullion, coins, and bars for sale to their customers. Purchases can often be made online, with options for home delivery, pickup at a local branch, or secure storage through the bank's vault services. Banks typically price these products based on current market bid and ask prices for the metal. TD Foreign Exchange Centres also have a selection of physical precious metals available for immediate purchase for their customers.
What is the difference between a gold ETF and the Royal Canadian Mint ETR?
A gold exchange-traded fund (ETF) is a fund that holds gold bullion or gold-related assets, and investors buy shares of the fund. The Royal Canadian Mint's Exchange-Traded Receipt (ETR) represents direct beneficial ownership of specific physical gold bullion stored at the Mint. The ETR is backed by the Government of Canada and can be redeemed monthly for physical gold or cash, whereas an ETF share represents an indirect claim on a pool of assets. The Mint states it does not offer units in a trust or fund, distinguishing its ETR structure.
Is gold a good hedge against inflation for Canadians?
Gold is widely regarded as a hedge against inflation because its price tends to rise when the purchasing power of currency declines. Historical data, such as the long-term trend in the price of bread measured in gold, shows that gold has maintained purchasing power over time. For Canadians, this effect can be amplified if the Canadian dollar weakens against the U.S. dollar, as gold is priced in USD. During periods of rising costs, a small allocation to gold may help protect a portfolio's real value.
Can I hold gold in my TFSA or RRSP?
Physical gold bullion itself generally cannot be held directly in a TFSA or RRSP unless it meets specific Canada Revenue Agency rules on purity and storage. However, many gold-based financial products are eligible. These include shares of gold exchange-traded funds (ETFs) and exchange-traded receipts (ETRs) that are listed on designated exchanges, as well as stocks of gold mining companies, all of which can be held in a self-directed registered account. Precious metal certificates offered by firms like TD Wealth are also held electronically and may be available in certain investment accounts.
What are the costs of owning physical gold?
Owning physical gold involves several costs. Upon purchase, you pay a premium over the spot market price, which can range from 1% to 8% depending on the product. You must also pay for secure storage, which could be a safe deposit box fee or a charge from a professional vaulting service. Insurance is often recommended for valuable holdings. When you sell, you may receive a price slightly below the spot price, creating a transaction cost spread. These combined costs mean physical gold is best considered for longer-term holding periods.
How do I sell gold that I own?
Physical gold can be sold back to bullion dealers, some banks, or specialized precious metals retailers. The selling price will typically be at or slightly below the current spot price of gold. For gold ETFs, ETRs, or mining stocks, you sell the shares through your brokerage account during market hours at the prevailing market price, subject to brokerage commissions. The Royal Canadian Mint allows ETR holders to redeem for physical gold or cash on a monthly basis. The proceeds from the sale may be subject to capital gains tax, so consult a tax advisor.
Sources and further reading
- Precious Metals: Buy Gold, Silver & Platinum td.com
- How to invest in gold in Canada: ETFs, bullion, and more wealthsimple.com
- An introduction to gold investing rbcgam.com
- Net Asset Value, Canadian Gold Reserves reserves.mint.ca
- How to Invest in Gold Canada: A No-Nonsense Guide canambullion.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.