Allstate Insurance Company of Canada provides home insurance policies for homeowners, condo owners, and tenants in select provinces. The company, which has operated in Canada's property and casualty insurance sector since 1953, offers coverage through a network of local agents rather than direct online sales. Canadians can customize their policies with various optional enhancements and may qualify for discounts, particularly by bundling home and auto insurance. Understanding Allstate's provincial availability, purchasing process, and coverage options is essential for evaluating it as a home insurance provider.
Provincial Availability and Service Model
Allstate home insurance is not available nationwide but is offered in five specific provinces. As of April 2025, coverage is available to residents of Ontario, Alberta, Quebec, New Brunswick, and Nova Scotia. The company operates through approximately 60 local agencies within these provinces, requiring customers to interact with an agent to purchase a policy. This model provides face-to-face service for those who prefer a traditional approach, though it limits customers to Allstate's own products and underwriting. Allstate Insurance Company of Canada is the underwriter for all policies, meaning coverage options, pricing, and discounts are set by the company itself. The parent organization, The Allstate Corporation, is one of the largest insurance organizations globally, providing financial backing to the Canadian operation.
Types of Home Insurance Policies Offered
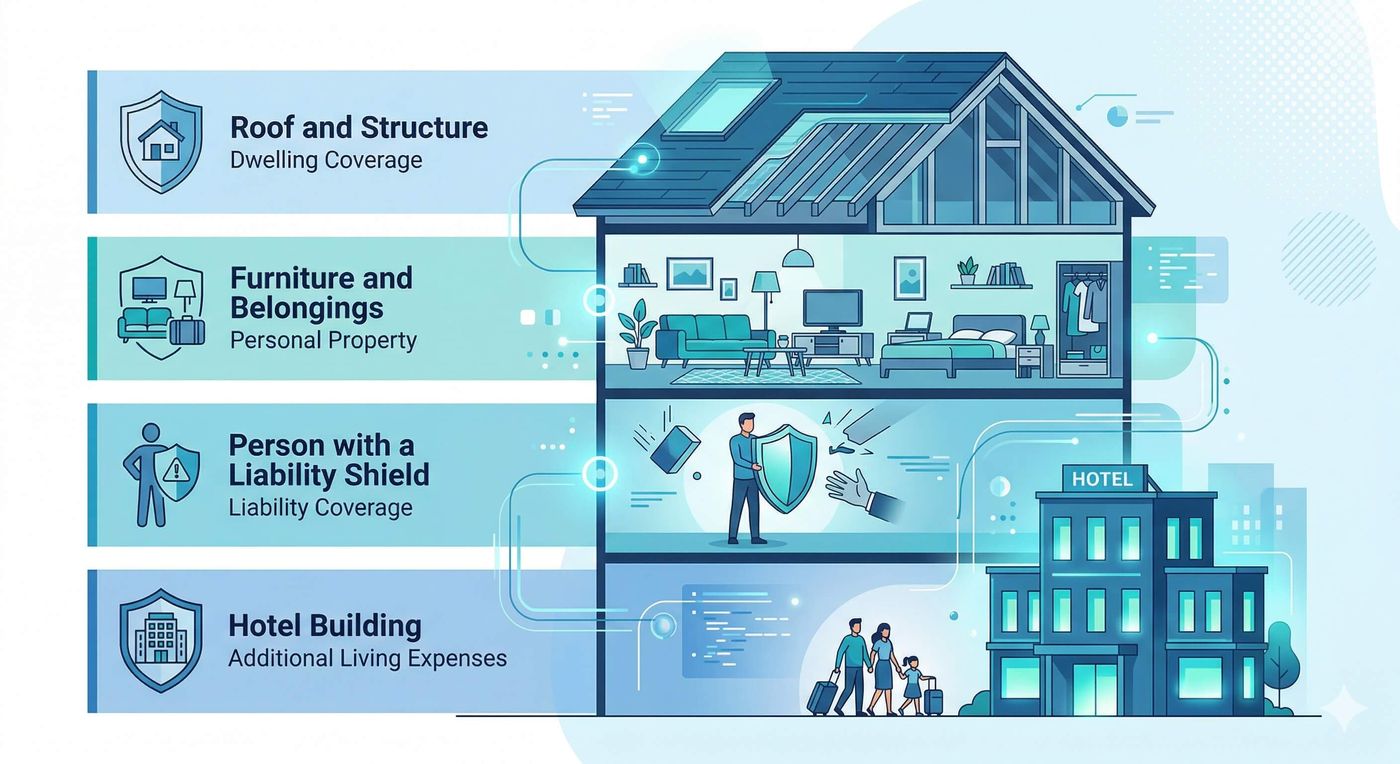
Allstate Canada provides property insurance for various types of dwellings, allowing customers to select a policy that matches their living situation. The company offers specific policies for standalone houses, condominium units, and tenants renting apartments or houses. Each policy type is designed to address the distinct insurance needs of the property owner or occupant. For homeowners, coverage typically includes the dwelling structure, detached structures like sheds, personal belongings, and personal liability. Condo insurance covers improvements to the unit, personal contents, and personal liability, often complementing the building insurance held by the condominium corporation. Tenant insurance focuses primarily on the renter's personal belongings and liability, as the building itself is the landlord's responsibility. Allstate allows for significant customization of these base policies with numerous optional coverages and enhancements.
Core and Optional Coverage Enhancements
Beyond basic home insurance, Allstate offers a suite of optional coverages that policyholders can add to tailor their protection. These enhancements address specific risks that may not be fully covered under a standard policy. One notable option is guaranteed replacement cost, which ensures a payout equivalent to the property's full repair or rebuild value even if the claim exceeds the policy's stated coverage limit. For protection against natural disasters, customers can add earthquake insurance and enhanced water coverage, which includes protection against sewer backup and overland flooding. Valuable items like jewellery can be covered through scheduled personal property endorsements that extend contents insurance limits.
Other specialized coverages include business property protection for at-home businesses, as regular home insurance does not cover commercial claims. The company also offers a claim-free protector, which prevents the home insurance premium from increasing after a customer makes their first claim. A disappearing deductible feature lowers the deductible amount for each consecutive policy term the customer remains claims-free, though this is not automatically included in every policy. Furthermore, Allstate provides an option called coverage reallocation, which allows extra coverage from one section of the policy to be used to compensate another underinsured section, such as using contents insurance to cover a shortfall in dwelling coverage.
Discounts and Savings Opportunities
Allstate promotes several ways for homeowners and renters to receive a discounted premium on their home insurance policy. The most advertised discount is for bundling, where customers combine their Allstate home insurance with an Allstate auto insurance policy. The company claims this can save customers an average of $1050, based on a national average as of May 2026, though terms and conditions apply. Other discounts are available for homes that are newly built, for the installation of monitored security systems or fire alarms, and for policyholders of retirement age. Customers may also qualify for a discount if their company or association is part of Allstate's Group Hands Insurance program.
- Bundle home and auto insurance with Allstate.
- Insure a newly built home.
- Install monitored security systems or fire alarms.
- Participate in the Group Hands Insurance program through a qualifying employer or association.
- Be of retirement age.
- Install a Liberty Security system (specific partnership).
It is important to note that the availability of these discounts may vary by region and are subject to provincial laws and insurance regulations. Customers should confirm their eligibility for any discount directly with their Allstate agent, as not all discounts are available in every province or for every policy type. The specific discount for installing a Liberty Security system is an example of a partnership that may offer savings but is not a universally available option. Terms and conditions apply to all discounts and coverage options. For details, customers should contact their local Allstate agency or call 1-800-ALLSTATE.
The Purchasing and Claims Process
Purchasing Allstate home insurance requires interaction with a local agent, as policies cannot be bought directly online. The process typically begins by obtaining a quote, which can be done through the Allstate website in less than three minutes. However, to proceed from a quote to a purchased policy, a customer must contact an Allstate agent by phone or through an in-person visit. This contrasts with digital brokers that allow for complete online purchase and binding of coverage. Once a policy is in force, customers can manage it through the myAllstate online portal or mobile app, which provides access to policy documents, billing information, and digital pink cards. The app also allows customers to go paperless, pay bills, and get support through live chat functions during specified hours.
Filing a home insurance claim can be initiated through multiple channels. Policyholders can start a claim online using the myAllstate platform or the mobile app. Alternatively, they can report a claim by calling 1-800-ALLSTATE (1-800-255-7828). Allstate's claims team offers a service where they can connect customers with a pre-approved network of service providers, handling the initial contact and providing details about the damage and coverage to help facilitate repairs. For customer support, live chat with an agent about policy questions is available Monday to Friday from 9 a.m. to 4 p.m. EST. Chat with a claim service representative for existing claims is available from 8:30 a.m. to 6:15 p.m. in all provinces except Quebec, offering another avenue for assistance during the claims process.
Comparison with Insurance Brokerage Models
A key distinction for consumers is the difference between purchasing insurance directly from Allstate and using an insurance brokerage. Allstate is a direct writer, meaning it underwrites and sells its own insurance products exclusively through its agents. In contrast, an insurance broker acts as an intermediary, comparing products, coverage, and prices from multiple insurance companies on behalf of the customer. This model can increase the chances of finding a policy that matches specific needs at a competitive price, as the broker has access to a wider market. Brokers like YouSet, mentioned in industry comparisons, operate digitally and can provide quotes from various carriers, promoting a mix-and-match approach to bundling home and auto insurance that may yield greater savings than bundling with a single provider like Allstate.
The direct agent model of Allstate offers personalized, in-person service but limits choice to one company's offerings. Customers are responsible for ensuring the policy and price are competitive, which may involve obtaining quotes from other providers independently. The brokerage model aggregates this comparison, though the broker may have a select panel of insurers. Allstate's financial strength, backed by its large global parent, is a factor some customers may weigh against the potentially wider choice offered by a broker. Ultimately, the choice between a direct insurer and a broker depends on a customer's preference for service style, desire for comparison shopping, and specific insurance needs, with each model presenting distinct advantages and limitations.
Important Considerations and Policy Management
When considering an Allstate home insurance policy, customers should be aware of several important details. All coverage, discounts, and perils are subject to provincial laws and insurance regulations, meaning what is offered in Ontario may differ from what is available in Alberta or Nova Scotia. The actual policy wording, not marketing materials, governs what is covered, so reviewing the specific terms and conditions is crucial. Optional features like the disappearing deductible or claim-free protector are not automatically included and must be added to the policy, potentially for an additional cost. Customers should also note that Allstate's advertised savings, such as the average bundling discount, are based on national averages and individual savings will vary.
Policy management is facilitated through digital tools. The myAllstate portal and app allow customers to access their policy, view billing information, make payments, go paperless, and get their pink card. For ongoing support outside of an agent visit, the live chat function provides direct access during business hours. At renewal, customers should review their coverage and premium, as rates are not guaranteed to remain static. While Allstate offers features to protect against rate increases after a claim, standard market factors can still affect pricing. It is considered a prudent practice to periodically compare insurance quotes, even for bundled policies, to ensure ongoing value and to confirm that the coverage continues to meet the homeowner's evolving needs.
Frequently asked questions
In which Canadian provinces is Allstate home insurance available?
Allstate home insurance is available in five provinces: Ontario, Alberta, Quebec, New Brunswick, and Nova Scotia. As of April 2025, the company does not offer home insurance in other provinces or territories. Coverage is provided for homeowners, condo owners, and tenants within these regions through a network of local agencies. The company offers both car insurance and home insurance to Canadians living in these provinces.
Can I buy Allstate home insurance online?
No, you cannot purchase Allstate home insurance directly online. While you can obtain a quote through the Allstate website in less than three minutes, the actual purchase of a policy must be completed through a local Allstate agent. This requires either a phone call or an in-person visit to one of their approximately 60 agencies in the covered provinces. Allstate operates through local agencies in select provinces, meaning you need to contact an agent directly to purchase a policy.
What discounts does Allstate offer on home insurance?
Allstate offers several potential discounts on home insurance premiums. The most prominent is for bundling home and auto insurance with Allstate, which the company states can save an average of $1050. Other discounts may be available for newly built homes, installed security systems or fire alarms, participation in a qualifying group insurance program, being of retirement age, and installing a specific Liberty Security system. Discount availability varies by province.
How do I file a home insurance claim with Allstate Canada?
You can file a home insurance claim with Allstate by starting the process online through the myAllstate portal or mobile app. Alternatively, you can report a claim by calling 1-800-ALLSTATE (1-800-255-7828). Allstate's claims team can then connect you with pre-approved service providers to help facilitate repairs, sharing details of the damage and your coverage with them. You can also manage and track your claim digitally using myAllstate.
What is Allstate's disappearing deductible?
The disappearing deductible is an optional feature that lowers your insurance deductible for each consecutive policy term you remain claims-free. It is not automatically included in every Allstate home insurance policy. Customers must either add it as an endorsement or select a coverage package that includes it. This feature is designed to reward customers who do not make claims.
How does Allstate home insurance differ from using an insurance broker?
Allstate is a direct insurance company that sells its own underwritten policies exclusively through its agents. An insurance broker, by contrast, represents multiple insurance companies and can compare products and prices from different carriers on your behalf. Using a broker may provide access to a wider range of options, while using Allstate directly provides service from a single, financially large provider but limits you to its products. Allstate home insurance is underwritten by Allstate Insurance Company of Canada.
Sources and further reading
- Auto, Property Insurance & More | Allstate Insurance Canada allstate.ca
- Allstate Insurance: Auto & Home Insurance in Canada ratehub.ca
- Home Insurance Coverage & Policies allstate.com
- Allstate Home Insurance vs. YouSet: Pros and Cons [2026] youset.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.