A Wealthsimple Joint Chequing Account is a no-fee hybrid account that combines everyday banking transactions with the ability to earn interest on deposits. This account allows two people equal access to manage shared finances, with features like a Visa Platinum Prepaid card, no foreign transaction fees, and worldwide ATM fee reimbursements. It is designed for Canadians seeking a fully digital banking solution for shared household expenses or savings. The account's structure and benefits differ from traditional bank joint accounts, particularly in how interest is calculated and how funds are protected.
What the Wealthsimple Joint Account Offers
The Wealthsimple Joint Chequing Account functions as a combined chequing and savings account for two co-owners. It provides a digital and physical Visa Platinum Prepaid card for both account holders to make purchases and withdrawals. There are no monthly account fees, no minimum balance requirements, and no fees for Interac e-Transfers. A key feature is the reimbursement of any fees charged by third-party ATM operators worldwide, allowing for free cash access in Canada and abroad. The account also does not charge a foreign transaction fee on purchases made in other currencies, though a standard currency conversion rate from the payment network still applies. Users can deposit cheques via the mobile app, order bank drafts for delivery, and deposit cash at over 5300 Canada Post locations. Funds in the joint account are held in trust with CDIC member institutions, providing deposit insurance protection. The account is designed for digital management, with all balances and transactions updated in real time through the Wealthsimple mobile app.
Interest Rates and How They Are Calculated
The interest earned on a Wealthsimple Joint Chequing Account is variable and calculated based on the total assets an individual holds across all their Wealthsimple accounts. The interest is an annualized rate calculated daily and paid out monthly. The specific rate tier applies to the primary account holder's total relationship with Wealthsimple. For joint accounts, the funds are registered under the primary account holder's name and the interest calculation is based on that person's eligible deposits and total assets. An additional interest boost of 0.5 percent is available for Core and Premium clients who set up a direct deposit of at least 2000 dollars per month into their Wealthsimple account. The tiered interest rate structure as of June 2026 is detailed in the following table. This structure means that to unlock the highest rate of 2.25 percent, the primary account holder must have at least 500000 dollars in assets with Wealthsimple across all accounts. These rates have no set promotional end date but are subject to change based on broader economic conditions such as Bank of Canada rate decisions. The 2.25 percent rate is positioned as the highest interest rate for a chequing account in Canada as of the 2026 information.
Eligibility and the Process to Open a Joint Account
To open a Wealthsimple Joint Chequing Account, both applicants must be Canadian residents with a valid Canadian address, a Social Insurance Number, and government-issued photo identification. The entire process is conducted online through the Wealthsimple mobile app. The primary account holder initiates the application and can then invite the co-holder via email to complete their portion. There is no requirement to visit a physical branch. Each user can have up to eight individual Wealthsimple Chequing Accounts and up to eight joint accounts. It is important to note that a joint account cannot be linked to a prepaid Visa Platinum card that is separate from the account's own card. Opening a joint deposit account does not affect the credit score of either holder, as it is not a credit product. This online setup process typically takes between 10 to 15 minutes to complete for most applicants, mirroring the digital onboarding experience of other Canadian digital banks like Neo and EQ Bank for their joint accounts.
Legal Structure, Access, and Provincial Considerations
A joint bank account in Canada typically grants both owners equal access and equal responsibility for the funds, meaning either person can deposit, withdraw, or send e-Transfers without the other's approval. This equal access is a fundamental characteristic that requires complete trust between co-owners, as there are no internal safeguards to prevent one person from emptying the account. In most provinces, joint accounts include a right of survivorship. This means if one account holder dies, the funds automatically transfer to the surviving holder outside of the estate process. Quebec is the exception to this common law rule. In Quebec, joint accounts are generally structured as Tenants in Common, meaning the deceased holder's share of the account forms part of their estate and does not automatically pass to the surviving account holder. Canadians in Quebec should confirm the specific account structure with Wealthsimple before opening a joint account to understand how survivorship would be handled. This provincial distinction is a critical piece of estate planning for couples using a joint account for shared assets.
Detailed Fee and Cost Structure
The Wealthsimple Joint Chequing Account operates with a clear no-fee structure for everyday banking activities. There are no monthly account fees and no minimum balance fees. The account does not charge fees for ATM withdrawals, and Wealthsimple reimburses any eligible fees charged by third-party ATM providers globally. There are no foreign transaction fees levied by Wealthsimple, though the Visa network's standard currency conversion applies, contrasting with the typical 2.5 percent foreign transaction fee charged by many Canadian banks. Interac e-Transfer fees are also not charged. For wire transfers, Wealthsimple charges a flat fee of 15 dollars for outgoing domestic wires, which is noted as the lowest flat rate fee for such wires in the country. There is no fee to receive wire transfers from any location. If an incoming wire is in a foreign currency, it will be converted and a standard foreign exchange fee will apply. The Visa Platinum Prepaid card has no annual fees and does not require a credit check or any other qualifications. This comprehensive fee waiver is a central part of the account's value proposition for cost-conscious Canadian households.
Deposit Insurance and Financial Services Context
Wealthsimple is not a bank but a FINTRAC-registered money services business. It does not operate physical branches. The funds held in a Wealthsimple Chequing Account, including joint accounts, are held in trust for the client with members of the Canada Deposit Insurance Corporation. This means eligible deposits are protected by CDIC insurance in case of a member institution's failure. Because Wealthsimple is not a traditional bank, it does not offer a full suite of banking products like personal loans or mortgages. Its offerings are focused on digital banking, investing, and cryptocurrency trading. The hybrid nature of the chequing account, which combines transaction and savings features, is a product design that differs from typical bank account structures. The lack of a branch network allows Wealthsimple to offer no account fees and competitive interest rates that might not be sustainable for traditional banks with higher overhead costs.
Comparison with Other Canadian Joint Account Options
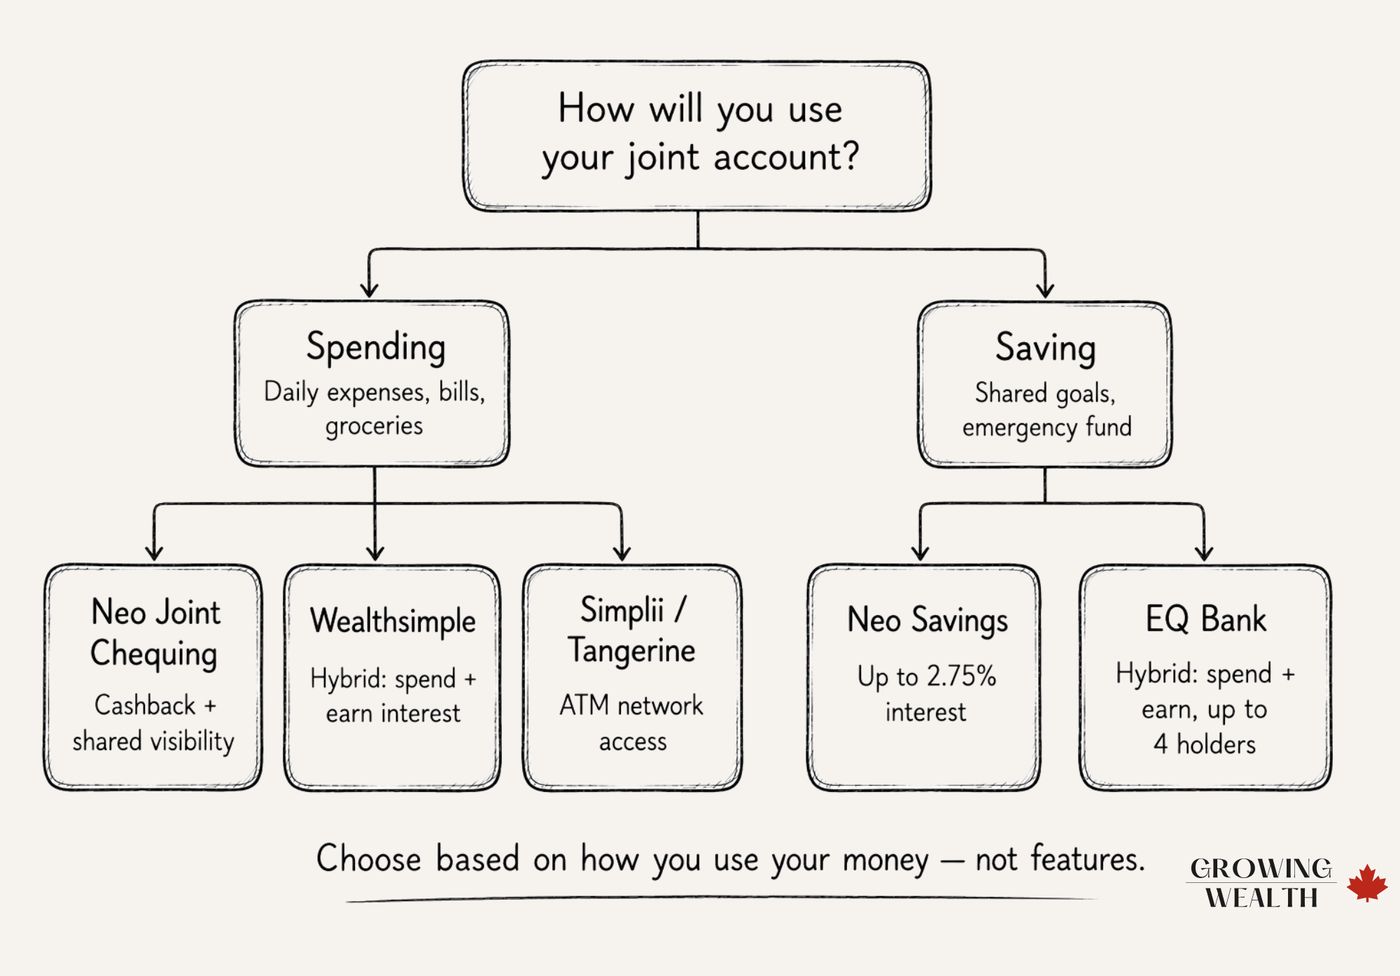
In the Canadian digital banking sector of 2026, several providers offer no-fee joint accounts with different strengths. Wealthsimple's hybrid model, which combines chequing and savings, is similar to the single-account approach of EQ Bank. Neo Financial offers a different model by providing separate joint chequing and joint savings accounts designed to work as a pair. Tangerine and Simplii also provide joint account options, though adding a joint holder to an existing Tangerine account requires a phone call. The specific benefits of each account cater to different uses, such as daily spending versus building shared savings. For instance, Neo's joint chequing account offers tiered cashback on gas and groceries that increases with the account balance, while EQ Bank's interest rate requires a qualifying direct deposit. The following table compares key features of these primary digital joint account options as of mid-2026. This comparison illustrates that the best joint account depends entirely on its intended use, whether for daily transactions, saving, or a combination of both, as each provider optimizes for different financial behaviours.
| Provider | Account Type | Key Feature for 2026 | Interest Rate Condition |
|---|---|---|---|
| Neo Financial | Joint Chequing | Cashback on gas/groceries (1-3%) | N/A (cashback account) |
| EQ Bank | Joint Hybrid | Single account for spend/save | 2.75% (with $2,000/month direct deposit) |
| Wealthsimple | Joint Chequing (Hybrid) | No FX fees, ATM fees reimbursed | 1.25% to 2.25% (based on total assets) |
Common Considerations and Operational Details
When using a Wealthsimple Joint Account, several practical considerations arise from its structure and features. The interest rate is tied to the primary holder's total assets, which may not align with the co-holder's financial situation or expectations. Both parties have full, unilateral access to all funds, which requires a high degree of trust and financial alignment as there are no internal safeguards if one person withdraws all the money. The account is entirely digital, which means there is no in-person branch support for customer service issues. Some features noted by Wealthsimple, such as instant access to part of a cheque deposit or a separate USD account, were listed as coming soon as of 2026. Users should also be aware that the prepaid Visa Platinum card linked to the account cannot be obtained separately for a joint account. A free chequebook is available if you set up your paycheque to be deposited into the Wealthsimple account. Key operational details for account holders to manage include cheque deposits processed by taking photos in the app with funds available in approximately six business days, bank drafts ordered through the app's 'more' section and shipped with a secure tracking link after a security check, and cash deposits made at over 5300 Canada Post locations across the country. Each account holder manages their card and spending preferences through the Wealthsimple mobile app, including the ability to lock the card if lost. The account was renamed from Wealthsimple Cash to the Wealthsimple Chequing Account in June 2025. Domestic wire transfers cost a flat $15 fee, while receiving wires is free. Funds can be deposited by linking a Visa or Mastercard debit card, in addition to bank account links and e-Transfers. Understanding these points helps users set realistic expectations for managing their shared finances through this digital platform and contrasts its operation with traditional joint accounts at brick-and-mortar banks.
Frequently asked questions
Does a Wealthsimple joint account affect my credit score?
No, opening or using a Wealthsimple Joint Chequing Account does not affect your credit score. It is a deposit account, not a credit product. The associated Visa Platinum Prepaid card also does not require a credit check and has no impact on your credit score, as it is a prepaid card and not a credit card. This differs from joint credit products like lines of credit or credit cards, which do report to credit bureaus and affect the credit of both holders.
How many joint accounts can I have with Wealthsimple?
You can open up to eight joint Wealthsimple Chequing Accounts. In addition, each user can also have up to eight individual Wealthsimple Chequing Accounts. This allows for significant flexibility in organizing finances for different shared goals or with different partners. This multi-account capability is part of Wealthsimple's design to help users keep their money organized across various saving and spending objectives.
What happens to a Wealthsimple joint account if one holder dies?
In most Canadian provinces, joint accounts with Wealthsimple carry the right of survivorship. This means if one account holder dies, the funds automatically transfer to the surviving account holder, bypassing the estate process. In Quebec, however, joint accounts are typically structured as Tenants in Common, meaning the deceased holder's share would become part of their estate. It is essential for Quebec residents to confirm the account's specific survivorship terms with Wealthsimple directly before opening the account.
Are there any fees for using the Wealthsimple joint account abroad?
The Wealthsimple Joint Chequing Account does not charge a foreign transaction fee. You can use the Visa Platinum Prepaid card for purchases in other currencies without a fee from Wealthsimple, though the Visa network applies a standard currency conversion rate. ATM fees charged by foreign ATM operators are reimbursed by Wealthsimple worldwide. This combination of no foreign transaction fee and ATM fee reimbursement is a distinctive benefit for Canadians who travel or make international purchases.
How do I deposit money into a Wealthsimple joint account?
You can deposit funds by linking an external bank account, sending an Interac e-Transfer, or initiating a wire transfer. You can also deposit cheques by taking photos of the front and back within the Wealthsimple mobile app, with processing taking about six business days. Cash deposits can be made at over 5300 Canada Post locations across Canada. Additionally, you can link a Mastercard or Visa debit card to deposit funds, providing multiple flexible options for adding money to the shared account.
Can I get a separate prepaid card for a Wealthsimple joint account?
No, you cannot get a separate prepaid Visa Platinum card for a Wealthsimple joint account. The joint account comes with its own Visa Platinum Prepaid card that both co-owners can use. The notes specify that you cannot get a prepaid Visa Platinum card with a joint account that is separate from the account's primary card function. This is an important limitation for users who might want distinct physical cards for different purposes within the same joint account structure.
Sources and further reading
- Best Joint Accounts in Canada for Families (2026 Guide) growingwealth.ca
- Wealthsimple Chequing Account review finder.com
- Canada's most powerful chequing account | Wealthsimple wealthsimple.com
- Wealthsimple Review 2026 - Pros, Cons, Fees & Promo milliondollarjourney.com
- Best no-fee joint accounts in Canada: A 2026 guide | Blog neofinancial.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.