First-time home buyers in Canada have access to several federal and provincial programs designed to reduce the upfront costs of purchasing a home. These include savings accounts, tax credits, and rebates that can make homeownership more attainable. The most prominent tools are the First Home Savings Account (FHSA) and the Home Buyers' Plan (HBP), alongside various tax relief measures. Understanding these programs is important for the financial aspects of buying your first property.
Federal First-Time Home Buyer Programs
The Government of Canada administers three primary programs to assist first-time home buyers. These are the First Home Savings Account (FHSA), the Home Buyers' Plan (HBP), and the First-Time Home Buyers' Tax Credit. Each program has distinct rules and benefits aimed at different stages of the home buying process. The FHSA is a savings vehicle, the HBP allows for a loan from retirement savings, and the tax credit provides direct relief on income tax owed. These federal initiatives are a major part of the support for new buyers across the country.
The First Home Savings Account is a registered plan introduced in April 2023. Contributions to an FHSA are tax-deductible, and withdrawals used to buy or build a qualifying first home are tax-free. The account has an annual contribution limit of $8,000 and a lifetime limit of $40,000 per person. Unused contribution room can be carried forward up to a maximum of $8,000 to the following year. The FHSA can remain open for up to 15 years, or until the end of the year you buy your first home, whichever comes first.
The Home Buyers' Plan allows individuals to withdraw up to $60,000 from their Registered Retirement Savings Plan (RRSP) to use toward a down payment. This withdrawal is not subject to income tax, provided it is repaid according to the program rules. Funds must be repaid to the RRSP over a 15-year period. For withdrawals made between January 1, 2022, and December 31, 2025, there is a three-year grace period, meaning repayments start in the fifth year after withdrawal. If a required repayment is missed, that amount is added to the individual's taxable income for that year.
The First-Time Home Buyers' Tax Credit is a non-refundable credit that reduces federal income tax payable. Eligible buyers can claim up to $10,000 on their tax return for a qualifying home. This amount is multiplied by the lowest federal tax rate of 15%, resulting in a maximum credit of $1,500. The credit can be split between eligible buyers, such as a spouse, but the combined total cannot exceed $10,000. It is designed to help offset costs like legal fees and home inspections.
Provincial and Municipal Programs
Several provinces and some municipalities offer additional incentives for first-time home buyers, primarily in the form of land transfer tax rebates or grants. These programs are separate from federal offerings and have their own eligibility criteria. The availability and value of these incentives vary significantly across the country. Buyers should investigate programs specific to their province and city of purchase, as these can provide meaningful savings on closing costs.
Ontario provides a land transfer tax rebate for first-time buyers of up to $4,000. In Toronto, which levies an additional municipal land transfer tax, the rebate for first-time buyers can be up to $4,475. British Columbia offers a first-time home buyer exemption or refund on the property transfer tax, with a maximum relief of $8,000. Prince Edward Island provides a grant covering up to 50% of legal closing costs, to a maximum of $1,500, plus a repayable loan. Nova Scotia has a First-time Homebuyers Program pilot project aimed at making homeownership more affordable.
Quebec offers a tax rebate for buyers of new or substantially renovated homes. This rebate covers a portion of the GST and provincial sales tax. It is important to contact provincial revenue or finance ministries to confirm program details. You should also contact local city halls to learn about municipal assistance programs. These local programs can change, so verifying information directly with the source is a necessary step before you buy.
Eligibility Rules for First-Time Buyers
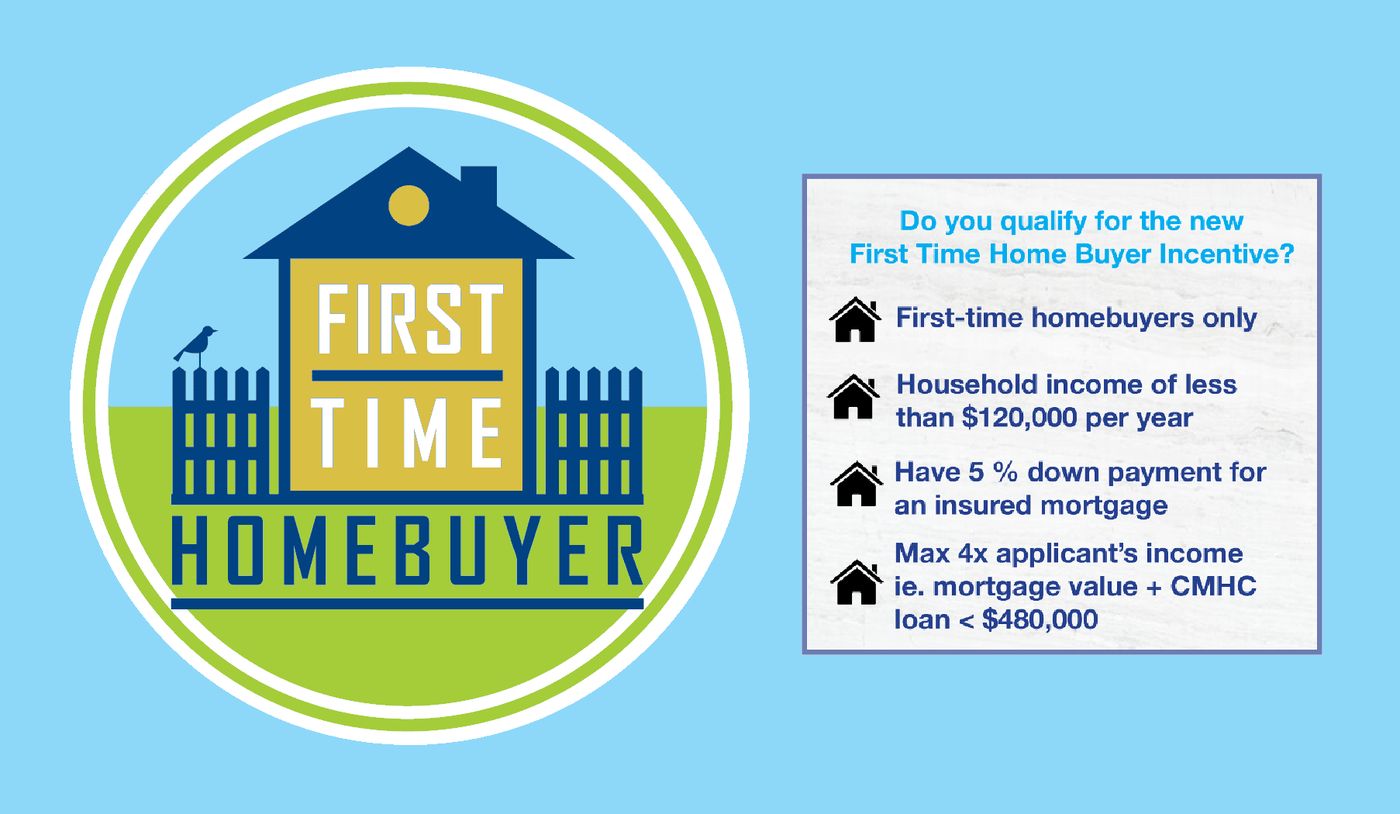
To qualify as a first-time home buyer for most programs, you must be at least 18 years old and a Canadian citizen or permanent resident. The core definition typically requires that you, or your spouse or common-law partner, have not owned and lived in a home as your primary residence in the current calendar year or the previous four calendar years. This rule applies to ownership in Canada or abroad. You must also intend to occupy the purchased home as your primary residence to meet the requirements for incentives like the HBP and FHSA.
There are specific exceptions to the first-time buyer rule. Individuals who are divorced or separated may be eligible for programs like the Home Buyers' Plan even if they owned a home before, provided any previous HBP withdrawal has been fully repaid. People buying a home for a related person with a disability are also exempt from the first-time buyer requirement for both the HBP and the First-Time Home Buyers' Tax Credit. Each program has slight variations, so verifying the specific criteria is essential before you apply.
- Must be 18 years or older and a Canadian citizen or permanent resident.
- Must not have owned and occupied a home as a principal residence in the current year or prior four years.
- Must intend to use the purchased home as a primary residence.
- Exceptions exist for those divorced/separated (with repaid HBP) and buyers for disabled relatives.
Eligibility for the First Home Savings Account has additional conditions. You must be a resident of Canada and cannot have opened an FHSA before. You also cannot have owned a home that you lived in as your principal residence at any time in the current calendar year or the preceding four calendar years. It is possible to transfer funds from an RRSP to an FHSA tax-free, but this counts toward the annual and lifetime contribution limits of the FHSA.
Key Financial Limits and Contribution Rules
The various first-time home buyer programs have specific financial limits that dictate how much you can save, withdraw, or claim. These limits are set by the federal government and are subject to change. Understanding these caps is vital for effective financial planning when saving for a down payment and closing costs. The table below outlines the key limits for the major federal programs.
| Program | Lifetime/Maximum Limit |
|---|---|
| First Home Savings Account (FHSA) | $40,000 |
| Home Buyers' Plan (HBP) Withdrawal | $60,000 per person |
| First-Time Home Buyers' Tax Credit | $10,000 claim amount |
| GST/HST New Housing Rebate | Full 5% GST on homes up to $1 million |
For the FHSA, contribution room starts accumulating only once the account is opened. If you do not contribute the full $8,000 in a year, you can carry forward the unused amount up to a maximum of $8,000 to the next year. This means you could contribute up to $16,000 in a single year if you had $8,000 in unused room from the prior year. A one percent tax per month applies to any contributions that exceed your available contribution room, so tracking your contributions is important.
The Home Buyers' Plan allows a withdrawal of up to $60,000 per person. The withdrawal does not have to be a single lump sum but must all be taken within one calendar year. For couples, each person can withdraw from their own RRSP, allowing for a combined total of up to $120,000. Note that withdrawals from locked-in or group RRSPs are generally not permitted under the HBP, which is a key restriction for some savers.
Steps to Access First-Time Buyer Programs
Accessing first-time home buyer benefits involves a series of steps, from opening accounts to making claims on your tax return. The process differs for each program, and some steps must be completed in a specific order. Being proactive and organized can help ensure you receive all the benefits for which you qualify. Following a clear sequence will help you manage the requirements for the FHSA, HBP, and tax credits.
- Confirm your eligibility as a first-time home buyer for each program you intend to use.
- Open a First Home Savings Account (FHSA) at a participating financial institution to start accumulating contribution room.
- Contribute to your FHSA and/or RRSP, keeping within annual and lifetime limits.
- When ready to buy, arrange withdrawals from your FHSA or HBP, ensuring you have a signed purchase agreement.
- Apply for provincial land transfer tax rebates through your provincial revenue agency at the time of purchase.
- Claim the First-Time Home Buyers' Tax Credit on your annual income tax return (Line 31270).
- Apply for the GST/HST New Housing Rebate if purchasing a new or substantially renovated home.
- Begin HBP repayments according to your schedule, starting in the second year after withdrawal (or year five with grace period).
For the First Home Savings Account, you will need to provide government issued identification and your Social Insurance Number when opening the account. To make a withdrawal for a home purchase, you must have a signed agreement to buy or build a qualifying home. For the Home Buyers' Plan, you must submit Form T1036 to your RRSP issuer to authorize the withdrawal. You should keep all relevant documents for your records, including purchase agreements and rebate forms.
Common Mistakes and Considerations
First-time buyers often encounter pitfalls when using these programs, which can lead to unexpected taxes or missed opportunities. A common mistake is not understanding the repayment requirements of the Home Buyers' Plan. Missing a required repayment installment means that amount is added to your taxable income for that year, creating a tax liability. Another error is over-contributing to the FHSA, which triggers a monthly penalty tax of one percent on the excess amount. Failing to use the FHSA within its 15-year lifetime is another consideration that can affect your savings strategy.
If you do not buy a home within the FHSA's 15-year period, the account must be closed. You can transfer the savings to an RRSP or Registered Retirement Income Fund (RRIF) without tax penalty, but you lose the unique tax-free withdrawal benefit for a home purchase. Buyers sometimes overlook provincial programs, assuming all incentives are federal. Checking for municipal grants or rebates in your city can provide additional savings that are easy to miss, so researching local options is a key step.
Using the Home Buyers' Plan impacts long-term retirement savings, as withdrawn funds are no longer growing tax-sheltered until they are repaid. The First-Time Home Buyers' Tax Credit is non-refundable, meaning it cannot generate a tax refund if your tax payable is already zero. For the proposed GST/HST rebate on new homes, the rebate is gradually reduced for homes priced between $1 million and $1.5 million and is not available for homes over $1.5 million. Always verify the most current rules, as program details can change from year to year.
Proposed and Recent Changes
The federal government has proposed changes to first-time home buyer programs through Bill C-4. As of early 2026, this bill has passed the Senate and is awaiting final approval. A key measure in the bill is a new GST/HST rebate for first-time buyers of newly constructed homes. The rebate would provide a full rebate of the 5% Goods and Services Tax on new homes priced up to $1 million. For homes priced between $1 million and $1.5 million, the rebate would be gradually reduced, and it would not apply to homes over $1.5 million.
If implemented, this rebate could reduce the upfront cost of buying a new home by up to $50,000. The rebate applies to newly built or substantially renovated homes that will be used as the buyer's primary residence. This change is designed to make new construction more accessible to first-time buyers. It is important to monitor official government sources for the enactment of this law and any updates to its terms, as this would be a significant new benefit.
Frequently asked questions
What is the First Home Savings Account (FHSA)?
The First Home Savings Account is a registered plan that helps first-time home buyers save for a down payment. Contributions are tax-deductible, and withdrawals used to purchase a qualifying first home are tax-free. The annual contribution limit is $8,000, with a lifetime maximum of $40,000 per person. Unused contribution room can be carried forward to the next year.
What is the First-Time Home Buyers' Tax Credit worth?
The First Time Home Buyers' Tax Credit allows you to claim up to $10,000 on your tax return. This amount is multiplied by the lowest federal tax rate of 15 percent. This provides a maximum non refundable credit of $1,500 to reduce your income tax payable. The credit can be split between eligible buyers, but the total claim cannot exceed $10,000.
Are there programs for first-time buyers in provinces like Ontario or BC?
Yes, several provinces offer programs. Ontario provides a land transfer tax rebate of up to $4,000 for first-time buyers. British Columbia offers a property transfer tax exemption or refund with a maximum relief of $8,000. Prince Edward Island has a grant covering up to 50% of legal closing costs, to a maximum of $1,500. Nova Scotia also runs a First-time Homebuyers Program pilot project.
What happens if I don't repay my Home Buyers' Plan withdrawal?
If you miss a required annual repayment under the Home Buyers' Plan, the missed amount is added to your taxable income for that year. This means you will pay income tax on that sum. It is essential to adhere to the 15 year repayment schedule. The schedule typically starts the second year after your withdrawal, or in year five if you used the grace period for withdrawals made by the end of 2025.
How much can I withdraw from my RRSP under the Home Buyers' Plan?
You can withdraw up to $60,000 from your RRSP tax free under the Home Buyers' Plan. If you are purchasing a home with a spouse or common law partner, each person can withdraw up to $60,000 for a combined total of $120,000. This withdrawal is specifically for buying or building a qualifying first home. The amount withdrawn must be repaid to your RRSP over a 15 year period. Repayments typically begin two years after the withdrawal, though withdrawals made between 2022 and 2025 have a three year grace period, starting repayment in year five.
Who qualifies as a first-time home buyer in Canada?
To qualify as a first time home buyer in Canada, you must be at least 18 years old and a Canadian citizen or permanent resident. You or your spouse must not have owned and lived in a home as your principal residence in the current year or the previous four calendar years. There are specific exceptions to this rule. For example, individuals who are divorced or separated may qualify if a previous Home Buyers' Plan withdrawal has been fully repaid. Another exception applies to those buying a home for a related person with a disability, where the first time buyer requirement is waived.
Sources and further reading
- Government of Canada Homebuyer Incentives and Rebates cmhc-schl.gc.ca
- First-Time Home Buyer Programs in Canada in 2026 ratehub.ca
- Grants and incentives for first-time home buyers nbc.ca
- Canada First-Time Home Buyer Incentives & Programs rbcroyalbank.com
- The Scoop on Five First-Time Home Buyer Programs in Canada crea.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.