First-time home buyers in British Columbia have access to several provincial and federal programs designed to reduce the upfront costs of purchasing a home. The primary provincial incentive is the First Time Home Buyers' Program, which can eliminate or reduce the property transfer tax owed. At the federal level, programs like the Home Buyers' Plan and the First Home Savings Account provide additional financial support. Understanding these programs and their eligibility rules is essential for any prospective buyer in the BC real estate market.
The BC First Time Home Buyers' Program
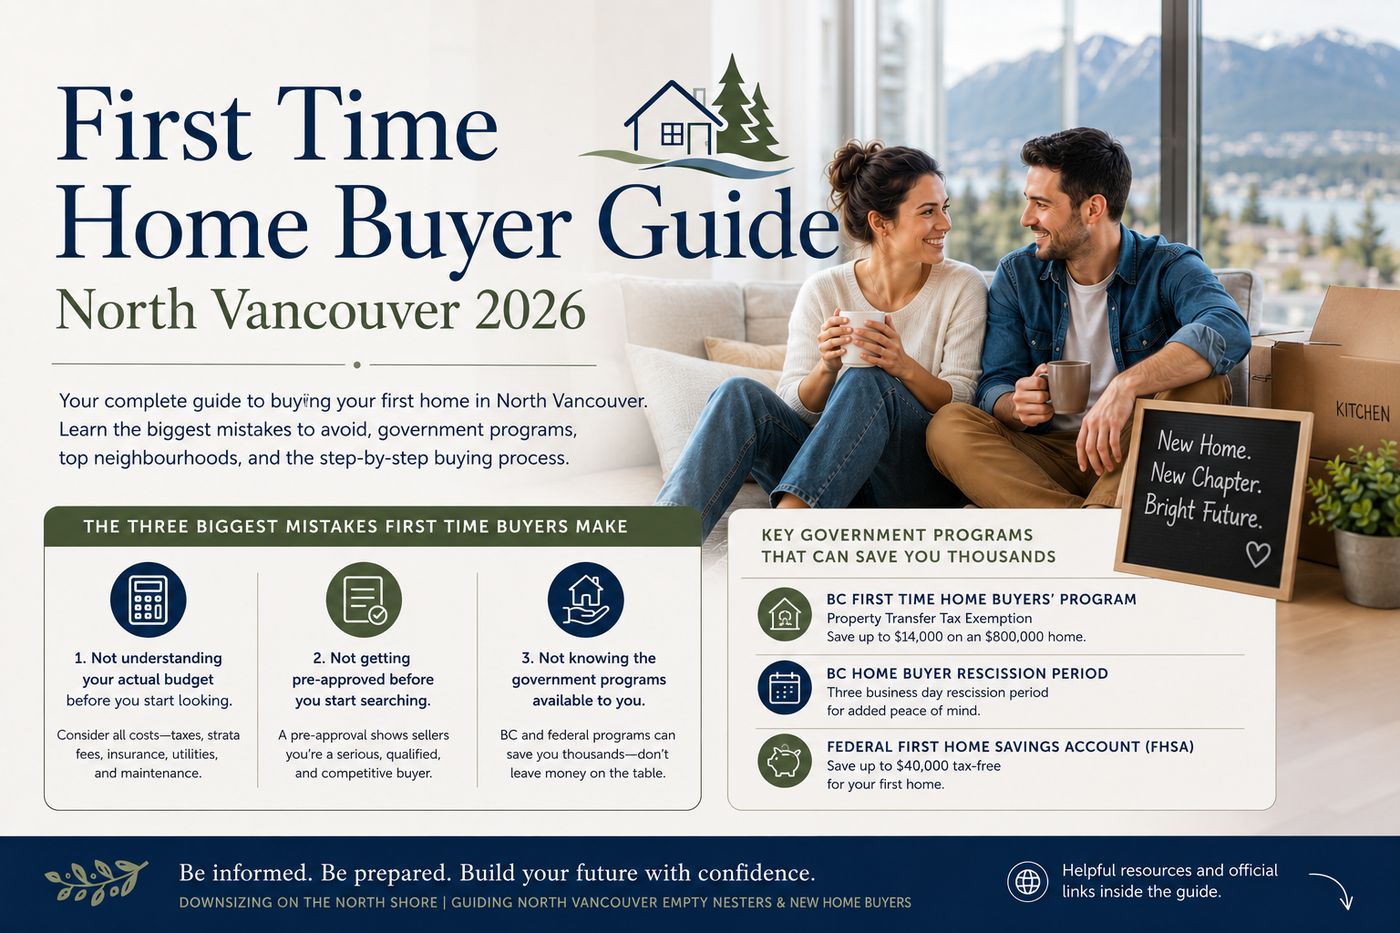
The First Time Home Buyers' Program is the main provincial incentive, providing a full or partial exemption from the property transfer tax (PTT). To qualify for a full exemption, the fair market value of the home must be $500,000 or less. If the purchase price exceeds $500,000, a partial exemption is available, providing a maximum benefit of $8,000 off the total PTT owed. The exemption applies specifically to the first $500,000 of the property's purchase price. Eligibility is not solely based on the property value but also on the buyer's personal circumstances and history. For homes purchased before April 1, 2024, the full exemption required a fair market value of $500,000 or less, and a partial exemption applied for values between $500,000 and $525,000.
You must also meet specific BC residency requirements, having lived in the province for at least one year immediately before the purchase or having filed at least two income tax returns as a BC resident in the last six taxation years. Crucially, you must never have owned an interest in a principal residence anywhere in the world and never have received a first time home buyers' exemption or refund before. If you purchase with others who do not qualify, only your percentage of interest in the property is eligible for the exemption. For example, if you have a 60% interest and a co-purchaser with a 40% interest does not qualify, only your 60% share receives the tax exemption.
Foreign entities and taxable trustees are not eligible for this exemption. However, an individual who is not a Canadian citizen or permanent resident at the time of purchase but becomes one on or before the first anniversary of the registration date may apply for a refund of the property transfer tax paid. To apply for such a refund, individuals must call 236-478-1593. All applications for the exemption are reviewed, and falsely declaring eligibility can result in a penalty equal to the amount of the exemption claimed. You will be charged this penalty if you falsely declare that you meet the occupancy requirements or that you are a first-time home buyer.
Federal Programs for First-Time Buyers
First-time buyers in BC can leverage several key federal programs to help with down payments and closing costs. The Home Buyers' Plan (HBP) allows you to withdraw up to $60,000 from your Registered Retirement Savings Plan tax-free to put toward a home. If you are buying with a spouse or common-law partner, you can each withdraw this amount for a combined total of up to $120,000. These funds must be repaid into your RRSP over 15 years to remain tax-free, with a repayment grace period for withdrawals made by the end of 2025. Withdrawals under the HBP must be taken within one calendar year, and withdrawals from locked-in and group RRSPs are not permitted under this plan.
The First Home Savings Account (FHSA) is a registered savings plan that combines features of an RRSP and a TFSA. Contributions are tax-deductible, and investment growth and withdrawals for a qualifying home purchase are tax-free. You can contribute up to $8,000 annually, with a lifetime limit of $40,000 per person. Unused contribution room carries forward to the next year, up to a maximum of $8,000. For example, if you contributed $5,000 in 2025, you would have up to $11,000 in available contribution room in 2026. The account can remain open for up to 15 years, or until the end of the year you buy your first home, whichever comes first. If you do not buy a home, the savings can be transferred to an RRSP or RRIF without tax penalties.
The First-Time Home Buyers' Tax Credit provides a non-refundable tax credit of up to $1,500, calculated as 15% of a $10,000 claim. This credit can be split between eligible buyers purchasing a home together, but the combined total cannot exceed $10,000. To claim it, you enter the amount on Line 31270 of your federal income tax return. The credit is non-refundable, meaning it can only reduce tax owed to zero and will not generate a refund. For persons with a disability, or those buying a home for a related person with a disability, the first-time home buyer requirement is waived for this credit.
Eligibility Rules and Residency Requirements
Eligibility for first-time buyer programs involves meeting specific criteria that often differ between provincial and federal initiatives. For the BC property transfer tax exemption, the definition of a first-time buyer is strict. You cannot have previously owned a principal residence anywhere in the world or have received this specific BC exemption before. Your residency status is also critical. You must be a Canadian citizen or permanent resident at the time of purchase. Foreign entities and taxable trustees are not eligible for the provincial exemption. An individual who does not qualify initially due to residency status but becomes a citizen or permanent resident within one year of registration can apply for a refund.
Federal programs have their own definitions. For the Home Buyers' Plan and the First Home Savings Account, you are generally considered a first-time buyer if you have not owned and lived in a home as your principal residence in the current year or the previous four calendar years. An exception exists for the First-Time Home Buyers' Tax Credit, where the requirement is waived if you are buying a home for a related person with a disability. It is important to review the specific rules for each program you intend to use, as they are not identical. The eligibility criteria can vary, so checking the requirements before application is necessary.
To qualify as a first-time home buyer in Canada for most federal programs, you must be at least 18 years old and a Canadian citizen or permanent resident. You or your spouse or common-law partner must not have owned and lived in a home as your primary residence in Canada or abroad in the current or previous four calendar years. You must also intend to make the purchased home your primary residence. You may still qualify as a first-time buyer under certain circumstances even if you have owned a home before, depending on the specific program's rules.
Financial Amounts and Purchase Price Limits
The financial benefits and applicable limits of first-time buyer programs are tied directly to purchase prices. The BC property transfer tax exemption applies to the first $500,000 of the property purchase price. For a home valued at $500,000 or less, you will be exempt from paying any property transfer tax. If the property's purchase price is more than $500,000, the maximum exemption amount you can receive is $8,000. Furthermore, the minimum down payment required in Canada is 5% for the first $500,000 of a home's purchase price.
| Program or Threshold | Benefit or Requirement |
|---|---|
| BC PTT Full Exemption | No property transfer tax owed |
| BC PTT Partial Exemption | Maximum $8,000 tax reduction |
| Minimum Down Payment | 5% of purchase price |
| Minimum Down Payment | 5% on first $500,000, 10% on remainder |
| Minimum Down Payment | 20% of purchase price |
| First-Time Home Buyers' Tax Credit | Up to $1,500 credit (on $10,000 claim) |
| FHSA Lifetime Contribution | $40,000 per person |
| HBP Withdrawal Limit | $60,000 per person |
For the BC exemption, if the purchase price is more than $500,000, the exemption is calculated only on the first $500,000, resulting in the maximum $8,000 benefit. The federal GST/HST New Housing Rebate provides a rebate on the federal portion of the tax paid on a new or substantially renovated home, with the amount depending on the province. A proposed federal measure under Bill C-4, which had passed the Senate as of early 2026, could offer a full GST rebate on new homes priced up to $1 million for first-time buyers, with a phased reduction for homes up to $1.5 million. This rebate could reduce the upfront cost of buying a new home by up to $50,000.
Application Process and Key Deadlines
Applying for the BC First Time Home Buyers' Program typically occurs during the property registration process. Your lawyer or notary will apply the exemption directly on the property transfer tax return submitted to the province. After registration, you must meet ongoing requirements to keep the tax exemption. If you fail to meet these conditions, you may be required to repay the exemption and could face a penalty.
If you qualified for the program but did not apply at the time of registration, you can apply for a refund. The application window opens on the first anniversary of the registration date and closes 18 months after that date. To apply, you must complete, print, and sign the First Time Home Buyers' Application for Refund form, then scan and submit it with required documentation. For federal programs, the process is different. The Home Buyers' Plan requires you to fill out a form with your RRSP issuer, while the FHSA and tax credit are managed through your financial institution and annual tax return, respectively. The Home Owner Grant for property taxes is applied for annually through your municipality or the provincial government.
- BC PTT Exemption: Applied by legal professional during property registration.
- Occupancy Period: Must live in home for the first full year of ownership.
- Refund Application Window: From 12 months to 18 months after registration date.
- HBP Withdrawal: Must be taken within one calendar year.
- FHSA Account Lifetime: Can remain open for up to 15 years.
- HBP Repayment: Begins the second year after withdrawal (with grace period for withdrawals until end of 2025).
- Tax Credit Claim: Filed on Line 31270 of your annual income tax return.
If you move out of your home before the end of the first year of ownership, you may be required to repay a portion or all of the property transfer tax exemption you received. You must contact the province if you apply but fail to move onto the property within the required time, or move out before the required time. However, you still qualify to keep the full tax exemption if the owner passed away, or the property is transferred because of a separation agreement or a court order under the Family Law Act before the first anniversary. All applications for the exemption are reviewed by the provincial authorities.
Common Mistakes and Important Considerations
A common mistake is assuming eligibility for one program guarantees eligibility for another. The provincial and federal definitions of a first-time home buyer differ, so you must verify your status for each. Another error is misunderstanding the occupancy rules for the BC exemption. Moving out before the first year ends, except for permitted reasons like death or a court-ordered separation, can trigger a requirement to repay the tax benefit. Falsely declaring eligibility on the property transfer tax return can result in a penalty equal to the amount of the exemption claimed. You can be charged this penalty if you falsely declare that you meet the occupancy requirements or that you are a first-time home buyer.
When using the Home Buyers' Plan, a significant consideration is the long-term impact on retirement savings, as withdrawn funds must be repaid. Missing an annual repayment installment will cause that amount to be added to your taxable income for that year. For the First Home Savings Account, contributors must be mindful of the contribution limits to avoid a one percent monthly tax on over-contributions. It is also important to note that the GST/HST New Housing Rebate is available for newly built homes, which is separate from the first-time buyer programs but can provide additional savings. The Affordable Home Ownership Program in BC requires only a 5% down payment on the first $500,000, but 10% down is required on the remaining value over $500,000.
First-time buyers should also be aware of the Newly Built Home Exemption in BC, which provides a property transfer tax exemption and does not require the buyer to be a first-time home buyer. All applications for the first-time buyer exemption are reviewed by the province. Using the Home Buyers' Plan can help reduce upfront costs, but it may impact long-term retirement savings, so weighing the trade-offs is important before deciding to withdraw funds. The program acts like a loan with a 2-year grace period where no repayments are required for withdrawals made by the end of 2025, after which repayments must be made in equal installments over 15 years.
Additional Provincial and Targeted Supports
Beyond the main PTT program, BC offers other forms of homeowner support. The Home Owner Grant helps reduce annual property taxes on a principal residence and is available to all eligible homeowners, not just first-time buyers. To qualify, you must be the registered owner, a Canadian citizen or permanent resident, live in BC, and occupy the home. Homeowners must pay at least $350 in property taxes before receiving the grant. First-time buyers may be able to claim this grant in the current tax year if the previous owner did not. This grant is claimed each year through your municipality or directly from the province if you live in a rural area.
There are also targeted programs for specific groups. The Métis Homeownership Program, delivered by the Métis Financial Corporation, is a financial support initiative created to assist eligible Métis citizens in purchasing their first home in British Columbia. Furthermore, the Newly Built Home Exemption can provide a full or partial property transfer tax exemption on a newly constructed home, and this program does not require the buyer to be a first-time home buyer. The federal government has also proposed new GST relief for first-time buyers of newly constructed homes under Bill C-4, which could reduce costs by up to $50,000 on homes up to $1 million if implemented.
Some Canadian provinces and cities offer land transfer tax rebates specifically for first-time buyers. In Ontario, the maximum rebate is $4,000, in Toronto it is $4,475, and in Prince Edward Island it is $2,000. British Columbia's rebate under the First Time Home Buyers' Program is a maximum of $8,000. These rebates are only available in select provinces and cities, and eligibility rules apply. The BC Public Service acknowledges the territories of First Nations around BC and the rights of all Indigenous Peoples. The Métis Financial Corporation states that owning a home is a powerful way to build financial security and carries deep meaning for Métis families.
Frequently asked questions
What is the maximum property transfer tax rebate in BC for first-time buyers?
The maximum property transfer tax rebate under the BC First Time Home Buyers' Program is $8,000. This is the value of the partial exemption applied when a home's purchase price exceeds $500,000. If the home is priced at $500,000 or less, the rebate is a full exemption, meaning you pay no property transfer tax. For homes purchased before April 1, 2024, a partial exemption was available for homes valued between $500,000 and $525,000.
Can I use both the RRSP Home Buyers' Plan and the First Home Savings Account?
Yes, you can use both the Home Buyers' Plan and the First Home Savings Account together to save for your first home. The HBP allows a tax-free withdrawal from your RRSP, while the FHSA is a separate registered account with tax-deductible contributions and tax-free growth. Using both can significantly increase your available funds for a down payment. The FHSA has a lifetime limit of $40,000 per person, and the HBP has a limit of $60,000 per person.
What is the First-Time Home Buyers' Tax Credit worth?
The First-Time Home Buyers' Tax Credit is a non-refundable federal tax credit worth up to $1,500. It is calculated by multiplying the lowest personal federal income tax rate of 15% by a claim amount of up to $10,000. This credit reduces the amount of income tax you owe but will not generate a refund if your tax payable is already zero. The credit can be split between eligible buyers, but the total claim cannot exceed $10,000.
What are the down payment requirements for a first home in BC?
The minimum down payment in Canada is based on the purchase price. For a home valued at $500,000 or less, you need a minimum down payment of 5%. For a home priced between $500,000 and $1,499,999, you need 5% on the first $500,000 and 10% on the portion above $500,000. For homes costing $1.5 million or more, a 20% down payment is required. The Affordable Home Ownership Program (AHOP) in BC also requires a 5% down payment on the first $500,000.
Do I qualify as a first-time buyer if I owned a home outside of Canada?
For the BC First Time Home Buyers' Program, you do not qualify if you have ever owned an interest in a property that was your principal residence anywhere in the world. This is a key eligibility requirement for the provincial property transfer tax exemption. You must have never owned or had interest in a property that was your principal residence anywhere in the world. This global scope is stricter than some federal programs. Federal programs like the Home Buyers' Plan and the First Home Savings Account typically only consider ownership within Canada during a specific look back period, such as the past four calendar years.
What happens if I move out of my first home in BC within the first year?
If you move out of your home before the end of the first year of ownership, you may be required to repay a portion or all of the property transfer tax exemption you received. You must contact the province if you move out before the required time. There are specific exceptions to this rule. You may keep part of the exemption if you moved out before the end of the first year. You still qualify to keep the full tax exemption if the owner passed away, or the property is transferred because of a separation agreement or a court order under the Family Law Act before the first anniversary of the registration date.
Sources and further reading
- First time home buyers' program, Exemptions www2.gov.bc.ca
- First-Time Home Buyers Incentives in British Columbia nesto.ca
- Canada First-Time Home Buyer Incentives & Programs rbcroyalbank.com
- First-Time Home Buyer Programs in Canada in 2026 ratehub.ca
- Métis Homeownership Program | First-Time Buyer Support BC mfcbc.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.