Variable mortgage rates in Canada are interest rates that fluctuate with a lender's prime rate, which itself is influenced by the Bank of Canada's policy decisions. The best available variable rates are typically offered to borrowers with strong credit, verified income, and mortgages that are either default-insured or meet insurable criteria. These rates can vary significantly by province, lender, and the specific terms of the mortgage contract. Understanding how these rates are determined and compared is essential for Canadian homeowners and buyers seeking financing in a dynamic interest rate environment.
Understanding Variable Mortgage Rates in Canada
A variable rate mortgage in Canada features an interest rate that changes in relation to the lender's prime rate. For example, a Royal Bank of Canada variable mortgage might be advertised as RBC Prime Rate plus or minus a certain percentage. The prime rate used by major financial institutions generally moves in response to changes made by the Bank of Canada to its policy interest rate. This means your monthly payment amount or the portion of your payment going toward interest can change throughout the term of your mortgage. Variable rates are distinct from fixed rates, which are locked in for the entire term and typically move with government bond yields. The most commonly compared variable mortgage terms are the three-year and five-year closed terms, although other term lengths are available. In the current market, as of late 2026, five-year variable rates have been advertised starting from 3.25 percent for insured mortgages.
Key Factors That Determine Your Mortgage Rate
Several specific factors directly influence the mortgage rate a Canadian borrower is offered, moving beyond the general economic environment. The type of borrower is paramount, with the best prime mortgage rates reserved for those with strong credit scores, generally around 700 or higher, and fully verified income. The mortgage type and its insurance status create distinct rate tiers. Mortgages with default insurance, required for down payments below 20 percent on owner-occupied homes under $1.5 million, typically carry the lowest rates. Next are insurable mortgages, which have at least 20 percent equity, a 25-year or less amortization, and are for owner-occupied homes purchased under $1 million. Uninsurable mortgages, which fall outside these criteria, usually have the highest rates. The property location also affects rates, as competition among lenders and brokers varies province by province. Finally, the mortgage term length influences pricing, with lenders setting different rates for terms like one, three, or five years.
The following list details common scenarios that can lead to significant rate premiums or require alternative non-prime lending. Mortgages for condominiums may have a premium of 10 basis points. Properties located in small towns or rural areas can see premiums of 10 to 20 basis points. Non-prime mortgages typically cost at least 100 to 200 basis points more than prime rates and often include lender or broker fees of one percent of the mortgage amount or more. Furthermore, pre-approvals can sometimes carry a cost premium because a significant portion do not result in a closed mortgage, leaving lenders with unrecovered hedging expenses.
It is important for borrowers to understand that advertised best rates are for prime residential mortgages and may not apply to their specific situation without a full application and qualification. The stress test is another major factor, as federally regulated lenders must calculate if a borrower can afford payments at a rate that is 200 basis points above their contract rate or 5.25 percent, whichever is higher. This qualification hurdle can dictate which mortgage term and rate a borrower ultimately gets approved for, especially for those with higher debt-to-income ratios. The rules for this stress test were modified for borrowers switching lenders at maturity, with an exemption taking effect on November 21, 2024.
The Role of Default Insurance and Mortgage Eligibility
Mortgage default insurance is a critical component for accessing the best mortgage rates in Canada. This insurance is legally required for any home purchase where the down payment is less than 20 percent of the purchase price, applicable on the first $500,000 at 5 percent down and 10 percent on the portion from $500,000 to $1.5 million. Contrary to intuition, these insured mortgages often have the lowest rates because the insurer, not the lender, assumes the risk of default. This makes the loan less risky for the lender, who can then offer a lower interest rate. For borrowers with 20 percent or more equity, an insurable mortgage can offer rates 10 to 25 basis points lower than uninsured conventional mortgages, provided the amortization is 25 years or less and the home is owner-occupied. A savings of 10 basis points translates to keeping over $470 over five years for every $100,000 borrowed on a 25-year amortization.
Eligibility for the best prime rates involves meeting specific lender criteria beyond just the down payment. Borrowers must have a strong credit history, typically with a score around 700 or higher. They must also provide verification of stable income. Federally regulated lenders are required to apply a stress test to all insured and uninsured mortgages at the time of origination. This rule changed for borrowers switching lenders at maturity effective November 21, 2024. On that date, the federal stress test was removed for switch transactions where the mortgage amount and amortization period remain unchanged, regardless of whether the mortgage is insured or uninsured.
How to Compare and Find Current Variable Rates
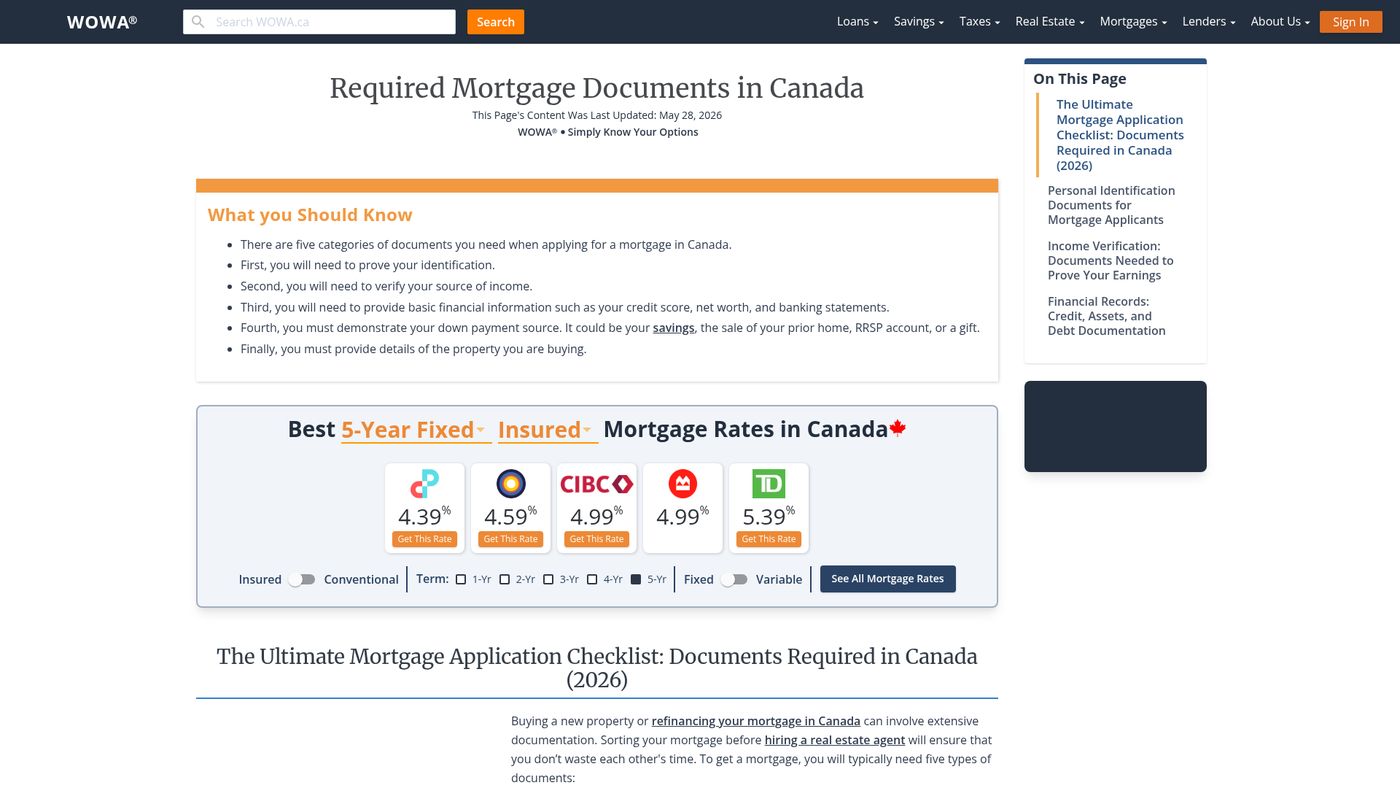
Canadian mortgage rates are dynamic and can change multiple times within a single business day. To find and compare the best current variable rates, borrowers should consult rate comparison websites and brokerages that aggregate data from numerous lenders. These services, such as Ratehub.ca, collect mortgage rates three times daily on business days from over fifty federal and provincial lenders and major brokerages across the country. They filter rates by province and classify them as insured, insurable, or uninsurable, presenting them from lowest to highest. It is important to note that the best rate displayed is based on the data these services can gather, and it is possible some brokerages or monoline lenders with slightly better rates may not be included. Furthermore, financial institutions may compensate these comparison sites through advertising or leads, but reputable sites maintain that this does not influence their independent rate ranking systems.
When comparing rates, borrowers should personalize their search by specifying their province, as rates can differ regionally due to local market competition. The same lender may offer different rates in Ontario versus Alberta, for instance. Key details to compare include the advertised rate, the annual percentage rate (APR) which includes some associated costs, and whether the rate is for an insured, insurable, or uninsurable mortgage. For example, a lender might advertise a 5-year variable closed rate at 3.65 percent with an APR of 3.68 percent. Borrowers should also look beyond the headline rate to understand terms, potential penalties for breaking the mortgage, and any fees associated with the product. Engaging with a mortgage broker can provide access to a wider array of lenders and help with these specific details, as brokers have relationships with multiple institutions and can often secure competitive offers.
Provincial Variations and Rate Tiers
Mortgage rates in Canada are not uniform across the country. The competitive landscape, lender licensing, and local economic conditions contribute to rate variations from province to province. Major rate comparison platforms allow users to filter rates specifically for Ontario, British Columbia, Alberta, Quebec, Manitoba, Nova Scotia, Saskatchewan, New Brunswick, and Newfoundland and Labrador. This provincial filtering is crucial because the lowest available rate for a 5-year variable mortgage in Vancouver may differ from the lowest available rate for the same product in Calgary or Toronto. Even national lenders may adjust their offerings to compete in specific regional markets. Consequently, a borrower's location is a concrete factor in the rates they are quoted, making it essential to search for rates within the correct provincial context.
Within each province, rates are further stratified into distinct tiers based on risk and insurance status. The primary tiers are insured, insurable, and uninsurable. Insured rates apply to mortgages with default insurance, typically from buyers with less than 20 percent down. Insurable rates are for conventional mortgages with at least 20 percent down that still meet insurer guidelines for owner-occupied properties, amortization, and price. Uninsurable rates are for all other mortgages, including those on rental properties, with amortizations over 25 years, or for owner-occupied homes over $1 million. The rate difference between these tiers is systematic, with insured generally being the lowest and uninsurable the highest. The following table illustrates typical rate differentials and examples of criteria for these tiers.
| Rate Tier | Typical Rate Premium | Common Criteria |
|---|---|---|
| Insured | Lowest Rate | Down payment < 20%, owner-occupied, price < $1.5M |
| Insurable | 10-25 bps above Insured | Down payment ≥ 20%, amortization ≤ 25 yrs, owner-occupied, price < $1M |
| Uninsurable | Highest Rate | Rental properties, amortization > 25 yrs, or does not meet insurable criteria |
Understanding which tier a mortgage falls into is the first step in anticipating the rate range a borrower might qualify for. This tiered system explains why two borrowers with identical credit scores but different down payment amounts or property types may receive substantially different mortgage rate offers from the same lender. Insurance status sorts mortgages into rate tiers that climb from insured through insurable to uninsurable as the lender takes on more risk. The criteria for these tiers are based on the risk profile assessed by both lenders and default insurers, creating a structured pricing model across the Canadian mortgage market.
Common Mistakes When Shopping for Variable Rates
One frequent mistake is focusing solely on the advertised headline rate without considering the mortgage's insurability status. A borrower with a 25 percent down payment might see a very low advertised rate, not realizing it is for an insured mortgage and thus not applicable to their situation. They would be looking at a higher insurable or uninsurable rate. Another common error is neglecting to factor in the stress test when calculating affordability. Some borrowers also fail to shop rates within their specific province, potentially missing better local offers available only through certain credit unions or regional lenders.
Overlooking the potential costs beyond the interest rate is another pitfall. This includes lender fees, appraisal costs, legal fees, and the potential cost of breaking a variable rate mortgage early, which is typically three months' interest but can be more. Relying on a pre-approval as a guaranteed rate can be misleading, as pre-approval rates are often slightly higher than final offered rates and are not a firm commitment until the full application is approved and the rate is locked. Finally, a significant mistake for existing homeowners is not being aware of the stress test exemption for switch transactions that took effect in late 2024. When renewing with a new lender without changing the mortgage amount or amortization, the stress test no longer applies, which could open up more competitive options that were previously unavailable due to the qualification hurdle. This exemption, effective November 21, 2024, applies regardless of whether the mortgage is insured or uninsured.
Frequently asked questions
What is the best 5-year variable mortgage rate in Canada?
The best available 5-year variable mortgage rate changes frequently, sometimes multiple times a day. As of late 2026, rates for insured mortgages have been advertised starting from 3.25 percent. The specific best rate for an individual depends on their province, credit profile, down payment amount, and whether their mortgage qualifies as insured, insurable, or uninsurable. Rate comparison websites that aggregate data from over fifty lenders are the most reliable source for current best rates.
How does the mortgage stress test affect variable rates?
This applies to both variable and fixed rate mortgages at origination. For a variable rate of 3.25 percent, the stress test rate would be 5.25 percent. This rule ensures borrowers can handle potential payment increases. An important exemption exists for borrowers switching lenders at maturity without changing their mortgage amount or amortization, as the stress test no longer applies to these switches as of November 21, 2024.
Why are insured mortgage rates often lower?
Insured mortgage rates are often the lowest because mortgage default insurance protects the lender, not the borrower, in case of default. This transfer of risk makes the loan less risky for the financial institution, which allows them to offer a lower interest rate. Insurance is required by law on any mortgage where the down payment is less than 20 percent of the purchase price, for owner-occupied homes under $1.5 million. This creates the counterintuitive situation where putting down less money can sometimes result in a lower mortgage rate.
Do variable mortgage rates differ by province?
Yes, variable mortgage rates can and do differ by province in Canada. Lenders and brokers are licensed provincially, and local competition influences pricing. The lowest available rate for a 5-year variable mortgage in Ontario may not be the same as the lowest rate in Alberta or British Columbia. Reputable rate comparison tools allow users to filter rates by province to see the best offers available in their specific regional market, which is a crucial step in accurate comparison.
What is the difference between insured and insurable mortgages?
An insured mortgage has borrower-paid default insurance, required when the down payment is less than 20 percent. An insurable mortgage has at least 20 percent equity but still meets the insurer's guidelines for owner-occupancy, a maximum 25-year amortization, and a purchase price under $1 million. Lenders can obtain insurance on these loans themselves, which allows them to offer rates that are typically 10 to 25 basis points lower than uninsurable mortgages. Uninsurable mortgages, such as those for rental properties or with longer amortizations, do not meet these criteria and have higher rates.
How often are mortgage rates updated?
Mortgage rates in Canada are highly dynamic. Major rate comparison platforms collect and update rates three times per day on business days from the websites of over fifty lenders and brokerages across the country. This frequent updating reflects changes in the bond market that affect fixed rates and changes in lender prime rates that affect variable rates. Borrowers should check rates close to when they are ready to apply or lock in a rate, as the best available offer can change within a short timeframe.
Sources and further reading
- Ratehub.ca: Compare Mortgages and Personal Finance ... ratehub.ca
- Best Mortgage Rates Canada from 3.25% (Compare 50 ... wowa.ca
- Current Mortgage Rates | RBC Royal Bank of Canada rbcroyalbank.com
- Canada Mortgage Rates from 2.49% | 19,000 Five Star Reviews truenorthmortgage.ca
- The best mortgage rates in Canada right now financialpost.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.