Low interest credit cards in Canada offer an annual percentage rate (APR) that is typically lower than the standard credit card rate, which often exceeds 20%. These cards are designed for individuals who occasionally carry a balance from month to month, as the lower interest rate can reduce the total cost of borrowing. They can also be useful tools for consolidating higher-interest debt through balance transfers. Understanding the features, rates, and trade-offs of low interest cards can help Canadian consumers make informed financial decisions.
What Defines a Low Interest Credit Card
A low interest credit card is characterized by an annual percentage rate that is substantially lower than the rates found on standard rewards or premium credit cards. The average interest rate on a standard credit card in Canada ranges from 19.99% to 23.99%, and can reach as high as 25% in some cases. In contrast, a low interest rate is generally considered to be under 14% APR. For example, the RBC Visa Classic Low Rate Option card has a fixed annual interest rate of 12.99% on purchases and 14.99% on cash advances. The primary purpose of these cards is to minimize interest costs for cardholders who do not pay their balance in full each billing cycle. This makes them a distinct product category focused on cost-saving rather than earning rewards or receiving extensive travel benefits. A low interest rate credit card has a rate of interest that is usually less than the typical interest rate of 20.99%, meaning less interest is charged if the balance is not paid in full on the payment due date.
Key Features and Common Trade-offs
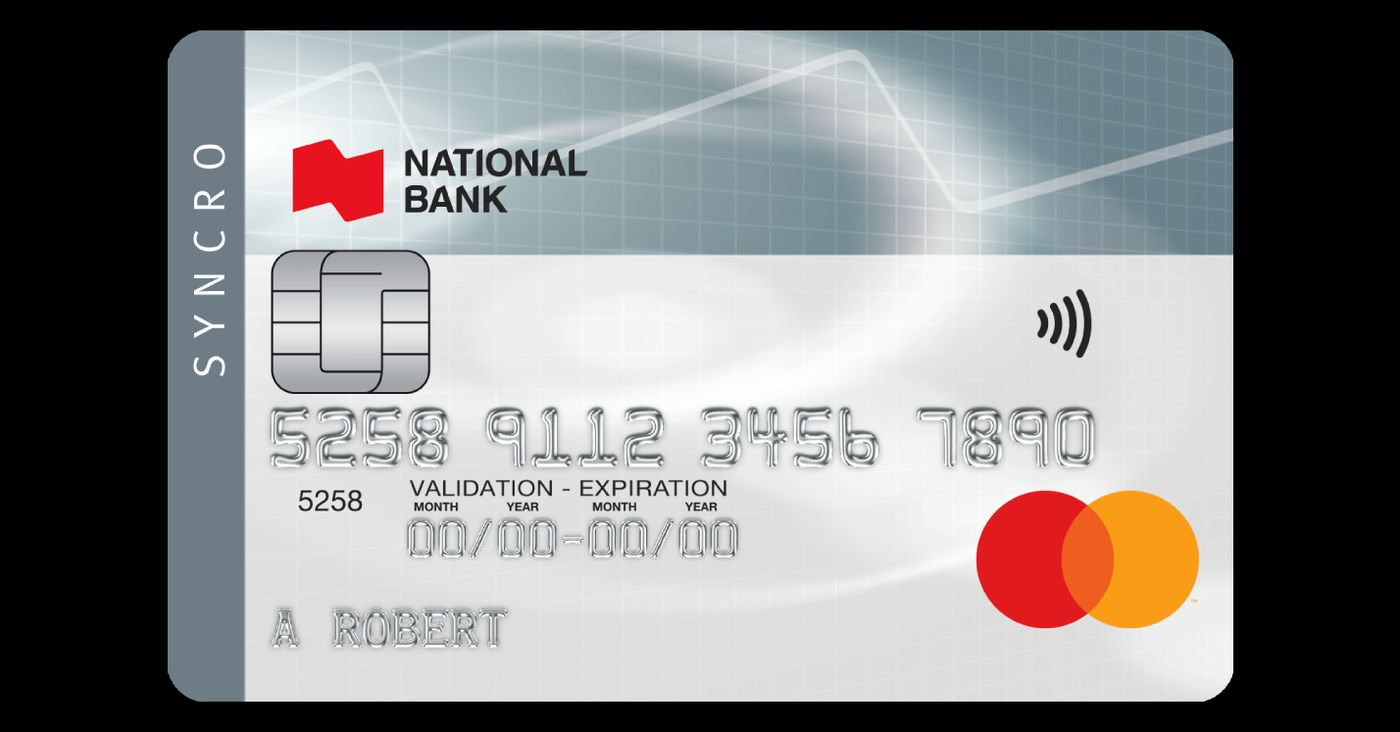
Low interest credit cards provide specific features aimed at reducing borrowing costs, but they also involve notable trade-offs compared to other card types. A central feature is the lower, often fixed, interest rate which provides payment predictability and easier budgeting. Some cards, like the National Bank Syncro Mastercard, offer variable rates starting as low as 8.90%, though these can fluctuate with the bank's prime rate. Many low interest cards also provide promotional balance transfer offers, such as a 0% interest rate for an introductory period, commonly between 6 to 12 months, to help consolidate debt. The trade-off for these lower rates is that the vast majority of low interest credit cards do not offer rewards programs, extensive travel insurance, or additional perks like purchase protection. Their design prioritizes interest savings over earning potential, which means cardholders seeking to build points or miles would need to look elsewhere. The biggest disadvantages of low interest credit cards is that very few of them offer rewards, insurance coverage or include any additional perks. The purpose of low interest credit cards is to save on interest paid as opposed to earning rewards on spending.
Promotional Offers and Balance Transfers
Promotional interest rates and balance transfer offers are significant features of many low interest credit cards in Canada. These promotions are typically time-limited and designed to attract new customers or help with debt consolidation. A common offer is a 0% promotional interest rate on balance transfers for a set period. For instance, the Scotiabank Value Visa Card offers a 0% rate on balance transfers for the first 9 months with a 1% balance transfer fee. The MBNA True Line Mastercard provides a 0% interest rate on balance transfers for 12 months. It is crucial to understand that these promotions usually involve a balance transfer fee, which is typically 1% to 3% of the amount transferred. After the promotional period ends, the card's standard low interest rate applies to any remaining balance. These offers can be effective for managing existing credit card debt, but require careful planning to pay off the transferred balance before the promotional rate expires. A balance transfer is when you move outstanding debt from one of your credit cards at another financial institution to your new credit card, which may help you manage your credit card debt. Using a low interest rate credit card to consolidate an outstanding balance from a high interest rate card can take advantage of lower interest rate charges.
Comparing Low Interest Card Options
Several financial institutions in Canada offer low interest credit cards, each with varying rates, fees, and structures. For example, the RBC Visa Classic Low Rate Option has a fixed annual interest rate of 12.99 percent on purchases. The MBNA True Line Gold Mastercard is ranked as one of the best low interest credit cards in Canada. The Scotiabank Value Visa Card offers a 0 percent promotional interest rate on balance transfers for the first 9 months. The following table compares a selection of cards and their key features as of 2026.
| Card Name | Notable Feature |
|---|---|
| National Bank Syncro Mastercard | Lowest listed purchase rate |
| RBC Visa Classic Low Rate Option | Fixed rate stability |
| MBNA True Line Mastercard | 0% balance transfer for 12 months |
| Scotiabank Value Visa | 0% balance transfer for 9 months |
| Scotiabank Platinum American Express | Earns Scene+ points |
| CIBC Select Visa Card | CIBC low interest option |
| BMO Preferred Rate Mastercard | BMO low interest option |
| Desjardins Flexi Visa | Desjardins low interest option |
As the table illustrates, options range from no-annual-fee cards with competitive rates to premium cards that combine a relatively low rate with a rewards program. The Scotiabank Platinum American Express is an exception among low interest cards, as it offers a 9.99% rate while also earning Scene+ points and providing travel benefits, though it carries a high annual fee of $399. Most other cards, like the MBNA True Line Mastercard, forgo rewards and often have low or no annual fees to maximize interest savings. Other notable cards include the American Express Essential Card which has an interest rate of 8.99%, and the TD Visa Low interest credit cards which offer credit flexibility with a low interest rate for purchases, balance transfers and cash advances.
Understanding Interest Calculations and Grace Periods
The Annual Percentage Rate (APR) represents the yearly cost of borrowing money, including both the interest and any additional fees associated with the credit card. The interest rate is the percentage charged on the amount borrowed, not including other fees. Understanding the APR provides a more comprehensive view of the total cost of carrying a balance. Most credit cards offer an interest-free grace period on new purchases, which is typically at least 25 days if you pay your new balance in full by the payment due date. There is no interest-free grace period on cash advances, special balance transfers, or interest charges themselves. The billing cycle or statement period is typically between 28 and 31 days. If you reside anywhere other than the province of Quebec, your required minimum payment will be the greatest of 1% of your new balance plus any interest charges and past due amounts, or $10 plus any past due amount. In Quebec, the minimum payment calculation is different, being the greatest of 5% of your new balance or $15 plus any past due amount.
Eligibility and Application Considerations
Eligibility for a low interest credit card typically depends on an applicant's credit history and income, similar to other credit products. Financial institutions assess an individual's credit score, debt-to-income ratio, and payment history to determine approval and the specific interest rate offered. Some card issuers provide online pre-approval tools that allow potential applicants to check their eligibility without an immediate impact on their credit score. For instance, Capital One offers a pre-approval process where, if pre-approved, an applicant can be sure of approval except in limited circumstances such as a significant change in credit information or inability to verify identity. While low interest cards are often accessible to those with good credit, individuals building or rebuilding credit may need to consider secured credit card options first. It is important to review all terms, including the standard interest rate, annual fee, and any potential penalty rates that may apply if minimum payments are missed. For example, on a TD Aeroplan Visa Business Card, the standard rate of 24.99% on purchases or 27.99% on cash advances applies if the minimum payment is not received before the payment due date twice within any 12 consecutive statement periods.
Strategic Use for Debt Management and Savings
Using a low interest credit card effectively requires a strategic approach focused on debt management and interest savings. The most effective strategy is to pay the full statement balance by the due date each month, which avoids all interest charges regardless of the card's rate. For those using a card for debt consolidation via a balance transfer, the goal should be to pay off the entire transferred balance before the promotional 0% interest period ends. A low interest rate credit card could be helpful if used to consolidate the outstanding balance from any high interest rate credit card you may have with another financial institution. If you cannot consistently pay off your credit card in full, the interest you accumulate on a rewards credit card would devalue any rewards you earn, making a low interest card a better financial position when carrying a balance. These cards can also fund an unexpected purchase as a safety net, with the lower rate minimizing the cost of carrying that emergency balance. Automating your credit card payments and limiting your card usage to essential purchases are two effective approaches to reduce interest and manage debt.
Common Mistakes and Penalties to Avoid
Several common mistakes can negate the benefits of a low interest credit card and lead to higher costs. A frequent error is focusing solely on a low promotional rate while overlooking the balance transfer fee, which can be 1% to 3% of the transferred amount. Another mistake is using the card for new purchases during a balance transfer promotional period, as payments are often applied to the lowest-interest balance first, which can leave the higher-interest purchase balance accumulating costs. Cardholders should also avoid missing minimum payments, as this can trigger penalty interest rates much higher than the card's advertised low rate. For example, a missed payment can cause a card's rate to revert to a standard penalty rate of 24.99% or more. Failing to pay off a transferred balance before the promotional period ends results in the remaining balance being subject to the card's standard purchase rate, which may still be low but is no longer interest-free. Not reviewing the cardholder agreement for specific terms regarding interest calculations, grace periods, and minimum payment formulas, especially the different rules for residents of Quebec, can lead to unexpected charges.
When a Low Interest Card Is the Right Choice
A low interest credit card is the right choice for specific financial behaviours and goals. It is suitable for individuals who anticipate occasionally carrying a balance from month to month due to unexpected expenses or timing issues with income, as it minimizes interest costs compared to a standard card. It is also a practical tool for someone looking to consolidate and pay down existing credit card debt through a balance transfer offer. If your main priority is paying off debt, it is wise to avoid rewards cards and stick with a low interest credit card or a balance transfer card. A low interest rate credit card might be right for you if you anticipate carrying a balance. Since these cards offer lower interest rates, you will likely pay less if you carry a balance compared to other credit cards. Conversely, if you consistently pay your balance in full each month, the interest rate is less critical, and a rewards card might provide more value, provided you avoid interest charges. A rewards credit card is only worth it if you pay off your statement in full each and every month. Sometimes, emergency expenses crop up or paycheques do not come through in time, and a low interest credit card will help minimize the interest that accumulates on your balance.
Frequently asked questions
What is considered a low interest rate for a credit card in Canada?
A low interest rate for a credit card in Canada is generally an annual percentage rate (APR) under 14%. This is significantly lower than the average standard credit card rate, which typically ranges from 19.99% to 23.99%. For example, the RBC Visa Classic Low Rate Option card offers a fixed rate of 12.99% on purchases. The National Bank Syncro Mastercard has a variable rate starting at 8.90%, which is among the lowest listed rates. The American Express Essential Card offers a rate of 8.99%.
Do low interest credit cards offer rewards or cash back?
The vast majority of low interest credit cards in Canada do not offer rewards, cash back, or extensive travel insurance benefits. This is the primary trade-off for receiving a lower interest rate. The design philosophy is to save on interest costs rather than earn on spending. A notable exception is the Scotiabank Platinum American Express card, which offers a 9.99% interest rate while also allowing cardholders to earn Scene+ points, though it carries a high annual fee of $399.
Can I transfer a balance to a low interest credit card?
Yes, many low interest credit cards offer balance transfer promotions. These often feature a 0% introductory interest rate for a set period, commonly between 6 to 12 months, to help consolidate higher-interest debt. For instance, the MBNA True Line Mastercard offers a 0% interest rate on balance transfers for 12 months. The Scotiabank Value Visa offers a 0% rate for the first 9 months. It is important to be aware of any balance transfer fees, which are typically 1% to 3% of the amount transferred.
What is the difference between a fixed and variable low interest rate?
A fixed interest rate on a credit card remains constant and does not fluctuate with market changes, offering predictability for budgeting. The RBC Visa Classic Low Rate Option, for example, has a fixed rate of 12.99%. A variable interest rate is tied to a financial institution's prime rate and can change over time. The National Bank Syncro Mastercard has a variable rate starting at 8.90%. Issuers can adjust fixed rates with notice to the cardholder.
Who should consider getting a low interest credit card?
A low interest credit card is suitable for individuals who anticipate occasionally carrying a balance from month to month, as it minimizes interest costs compared to a standard card. It is also a practical tool for someone looking to consolidate and pay down existing credit card debt through a balance transfer offer. If you consistently pay your balance in full each month, the interest rate is less critical, and a rewards card might provide more value, provided you avoid interest charges. A low interest rate card could be helpful to consolidate an outstanding balance from a high interest rate card to take advantage of lower interest rate charges.
What happens if I miss a payment on a low interest card?
Missing a minimum payment can have significant consequences on a low interest credit card. Many card agreements include penalty clauses that trigger a much higher standard interest rate if a payment is missed. For example, on certain TD credit cards, if the minimum payment is not received by the due date twice within any 12 consecutive statement periods, the standard rate of 24.99% on purchases or 27.99% on cash advances will apply. This can quickly negate the benefits of the card's low rate.
Sources and further reading
- Apply Online for Low interest rate Credit Cards in Canada td.com
- Low interest credit cards cibc.com
- The best low interest credit cards in Canada for 2026 ratehub.ca
- Which credit card is right for you? capitalone.ca
- Low Interest Rate Credit Cards, Apply & Save on Interest rbcroyalbank.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.