The Home Buyers' Plan (HBP) is a federal government program that allows Canadian residents to withdraw funds from their Registered Retirement Savings Plans (RRSPs) to buy or build a qualifying home. It is designed specifically for first-time home buyers to help finance a down payment. Withdrawals up to a set limit are not taxed at the time of withdrawal, provided the amount is repaid into an RRSP over a 15-year period. The plan is a significant tool for many Canadians seeking to enter the housing market by leveraging their existing retirement savings.
What Is the Home Buyers' Plan?
The Home Buyers' Plan is a program established under the Canadian Income Tax Act to facilitate home ownership. It permits eligible individuals to make tax-free withdrawals from their RRSPs to use toward the purchase or construction of a qualifying home. Normally, withdrawals from an RRSP are included in taxable income, but funds taken out under the HBP are not taxed at the time of withdrawal provided all program conditions are met. The core premise of the plan is that it functions as a loan from one's own retirement savings, which must be repaid over time. This allows first-time buyers to access a potentially large sum for a down payment without incurring immediate tax penalties or needing to secure additional high-interest debt.
Eligibility Requirements
To participate in the Home Buyers' Plan, an individual must meet several specific conditions set by the Canada Revenue Agency. The participant must be a resident of Canada from the time of the first HBP withdrawal until the purchase or construction of the qualifying home is complete. The primary condition is being a first-time home buyer, which is defined as not having owned and occupied a home as a principal residence in the calendar year of the withdrawal or in any of the four preceding calendar years. This condition is waived if the home is being purchased or built for a related person with a disability. The buyer must have a written agreement to buy or build a qualifying home, and that home must be occupied as the participant's principal residence within one year of buying or building it. Furthermore, the home must have been owned for less than 30 days before the first HBP withdrawal is made.
How the Withdrawal Process Works
To initiate a withdrawal under the HBP, an individual must first ensure the funds have been in their RRSP for at least 90 days. The next step is to complete the Home Buyers' Plan request form, known as Form T1036, and submit it to the RRSP issuer. This should be done before the closing date of the home purchase. It is crucial to coordinate with your financial institution, as they may require time to sell investments within the RRSP. Withdrawals must be completed in the same calendar year as the first withdrawal, or in January of the following year at the latest. A withdrawal can be made up to 30 days after the closing date of the home purchase, but not after. The withdrawn funds can be used for the down payment, closing costs, or both related to the qualifying home.
Participants can make multiple withdrawals under the plan, provided all withdrawals occur within the eligible timeframe. The total amount withdrawn cannot exceed the individual limit, which is $60,000 as of April 16, 2024. For couples where both partners are eligible, each can withdraw up to the limit from their own RRSPs, allowing for a combined total of $120,000 to be put toward the home purchase. This process converts retirement savings into immediately accessible home-buying capital without triggering a tax bill.
Repayment Rules and Schedule
The amount withdrawn under the HBP must be repaid into an RRSP over a maximum period of 15 years. Repayments are made by contributing to an RRSP and then designating a portion of those contributions as an HBP repayment when filing your annual income tax return. The minimum annual repayment is calculated as 1/15 of the total amount withdrawn. You can repay more than the minimum in any year, and there is no maximum on early repayments. If you repay less than the required minimum in a given year, the shortfall is added to your taxable income for that year and taxed at your marginal rate.
The schedule for when repayments must begin has been temporarily extended for recent withdrawals. For withdrawals made between January 1, 2022 and December 31, 2025, the 15-year repayment period starts in the fifth year after the year of the first withdrawal. For withdrawals outside this window, the repayment period traditionally starts in the second year after the withdrawal. Early repayments are permitted and will reduce the HBP balance, but they do not shorten the overall 15-year repayment period.
- Repayment period: 15 years maximum.
- Minimum annual payment: 1/15 of total withdrawal.
- Shortfall added to taxable income.
- Repayments do not affect RRSP contribution room.
- Start date for 2022 to 2025 withdrawals: 5th year after withdrawal.
- Start date for other withdrawals: 2nd year after withdrawal.
Financial Considerations and Strategic Use
Using the Home Buyers' Plan involves important financial trade-offs that prospective buyers should weigh. The primary advantage is accessing a substantial, interest-free loan from oneself to fund a down payment, which can reduce the size of a mortgage and potentially avoid the cost of mortgage default insurance if the down payment reaches 20% of the purchase price. The withdrawal itself is not taxable, and the repayments do not reduce your annual RRSP contribution room, allowing you to continue saving for retirement. A common strategy involves using existing non-RRSP savings to make an RRSP contribution just before a purchase, claiming the tax deduction, and then immediately withdrawing those same funds under the HBP, effectively generating a tax refund.
The main drawback is the loss of potential investment growth on the withdrawn funds within the tax-sheltered RRSP environment. If the investments in the RRSP would have generated significant returns, the cost of forgoing that growth could outweigh the benefits of the HBP. Furthermore, the requirement to repay the loan adds a mandatory annual savings obligation for 15 years, which could strain cash flow. If repayments are missed, the taxable income inclusion could result in an unexpected tax bill. The plan is best suited for individuals who have a stable income to manage the repayments and who prioritize home ownership in the near term over long-term retirement compound growth.
Comparison with the First Home Savings Account (FHSA)
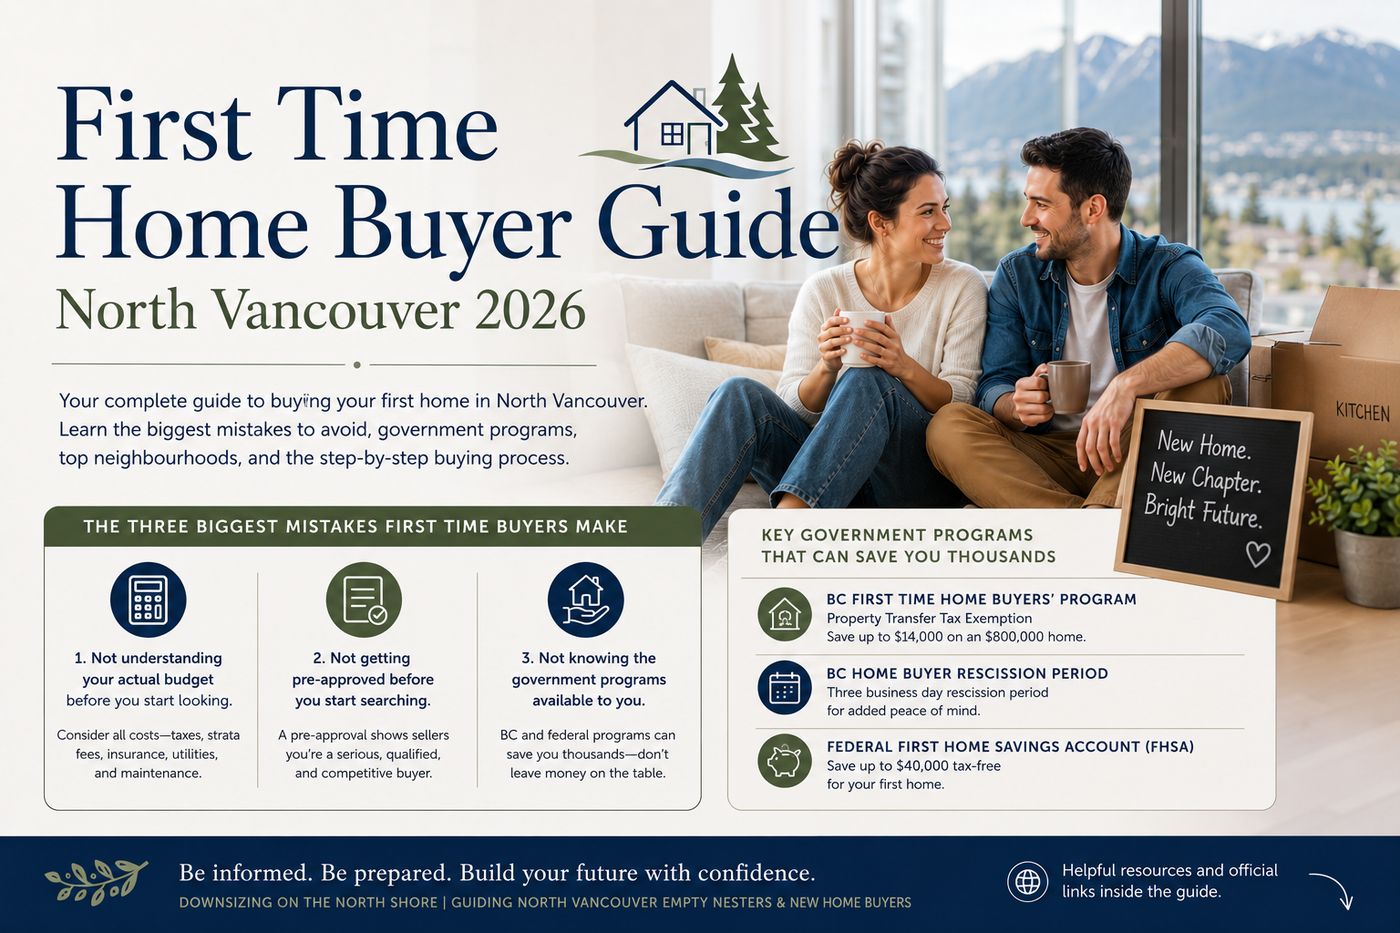
The First Home Savings Account is a newer registered plan introduced to help Canadians save for a first home. While both the HBP and FHSA aim to facilitate home ownership, they operate under different rules and can be used in combination. The FHSA allows for tax-deductible contributions and tax-free growth, and qualifying withdrawals for a home purchase are completely tax-free with no requirement to repay. The annual contribution limit for an FHSA is $8,000, with a lifetime maximum of $40,000. In contrast, the HBP is not a savings account but a withdrawal mechanism from an existing RRSP, with a much higher accessible amount of $60,000 per person that must be repaid.
A key difference is that FHSA withdrawals do not need to be paid back, whereas HBP withdrawals do. The HBP can be used in conjunction with the FHSA, allowing a first-time buyer to maximize their available funds. The FHSA has a 15-year lifetime for the account itself, while the HBP has a 15-year repayment schedule for the withdrawn funds. Choosing between or combining these tools depends on individual savings, timeline, and financial goals.
| Feature | Home Buyers' Plan (HBP) | First Home Savings Account (FHSA) |
|---|---|---|
| Source of Funds | Existing RRSP savings | New contributions to a dedicated account |
| Maximum Accessible Amount | $60,000 per person | $40,000 lifetime contribution limit |
| Tax Treatment on Withdrawal | Tax-free if repaid | Tax-free (no repayment) |
| Repayment Required | Yes, over 15 years | No |
| Annual Contribution Limit | N/A (withdrawal, not contribution) | $8,000 |
Recent Changes and Historical Limits
The Home Buyers' Plan has undergone several adjustments since its inception, most notably increases to the withdrawal limit and changes to the repayment grace period. The most recent change, effective April 16, 2024, raised the maximum withdrawal amount to $60,000 per individual from the previous limit of $35,000. This change significantly increases the potential down payment assistance available to Canadian home buyers. Furthermore, a temporary measure extends the repayment start date for withdrawals made between January 1, 2022 and December 31, 2025. For these withdrawals, the 15-year repayment period begins in the fifth year after the year of withdrawal, rather than the second year, providing buyers with more immediate financial flexibility after their purchase.
These changes reflect the government's response to rising home prices and the challenges faced by first-time buyers in accumulating a sufficient down payment. The increased limit allows individuals and couples to tap into a larger portion of their retirement savings to bridge the affordability gap. The extended repayment start date acknowledges the upfront costs of home ownership, giving buyers several years to stabilize their finances before beginning the mandatory repayments. It is important for users to verify the specific rules in effect at the time of their withdrawal, as these parameters can be subject to further government amendment.
Frequently asked questions
How much can I withdraw from my RRSP using the Home Buyers' Plan?
As of April 16, 2024, the withdrawal limit is $60,000 per eligible individual. This increase from $35,000 means a couple where both partners are eligible can withdraw a combined total of $120,000 from their RRSPs. The funds must be used to buy or build a qualifying home. To qualify, the RRSP funds you are using must have been on deposit for at least 90 days before the withdrawal.
What happens if I don't repay the minimum amount one year?
You are required to repay at least 1/15 of the total withdrawn amount each year. If you repay less than this minimum, the shortfall is added to your taxable income for that year. This amount will be taxed at your marginal tax rate. Importantly, this payment does not reduce your outstanding HBP balance, so you still owe the full original amount.
Can I use the HBP if I already have money saved for a down payment?
Yes, using the HBP can still be a strategic financial move. If you have non RRSP savings, you could contribute them to your RRSP at least 90 days before your home purchase. This contribution is tax deductible. You can then withdraw those funds under the HBP for your down payment. This generates a tax refund while providing the down payment money, though you must repay the withdrawn amount to your RRSP over 15 years.
Can I use both the HBP and the First Home Savings Account (FHSA)?
Yes, the Home Buyers' Plan and the First Home Savings Account can be used together. The FHSA allows for tax free contributions and withdrawals for a first home purchase, with a lifetime limit of $40,000. You can use an FHSA and also make a separate withdrawal from your RRSP under the HBP, which has a $60,000 limit per person. This combination can maximize the total funds available for your down payment.
What are the eligibility requirements for the Home Buyers' Plan?
To be eligible for the Home Buyers' Plan, you must be a resident of Canada from your first withdrawal until you buy or build the home. You must be a first-time home buyer, which typically means you have not owned a home you lived in as your principal residence in the last four years. You must have a written agreement to buy or build a qualifying home and intend to use it as your principal residence within one year. The home must have been owned for less than 30 days before your first withdrawal. Exceptions exist for buying a home for a related person with a disability.
How long do I have to repay the Home Buyers' Plan withdrawal?
You have 15 years to repay the full amount withdrawn under the Home Buyers' Plan. Repayments must begin in the second year after the year of your first withdrawal. However, for withdrawals made between January 1, 2022 and December 31, 2025, the start of the repayment period is extended to the fifth year after the year of withdrawal. You must repay at least 1/15 of the total amount each year into your RRSP.
Sources and further reading
- First Time Buyers and Canada's Home Buyers' Plan td.com
- The RRSP Home Buyers' Plan rbcroyalbank.com
- Use the Home Buyers' Plan to Buy Your Home Sooner cibc.com
- What exactly is the Home Buyers' Plan (HBP)? ia.ca
- How does the Home Buyers' Plan HBP Work? fidelity.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.