The Wealthsimple Chequing Account is a hybrid financial product that combines no-fee daily banking with high-interest savings features. It is designed for Canadians seeking a digital-first account that offers interest on balances, unlimited transactions, and reimbursed ATM fees. This account is notable for its tiered interest rate structure and lack of monthly fees, though it is not offered by a traditional chartered bank. Understanding its features, limitations, and how it compares to conventional banking is essential for Canadians considering it for their primary financial needs.
What is the Wealthsimple Chequing Account
The Wealthsimple Chequing Account, formerly known as Wealthsimple Cash, is a digital financial account that merges the functionality of a transactional chequing account with the interest-earning potential of a savings account. It is not a product of a traditional bank but is offered by Wealthsimple, a FINTRAC-registered money services business. The account provides a Visa Platinum Prepaid card, available in both digital and physical forms, for making purchases and withdrawals. Account management is conducted entirely through the Wealthsimple mobile app, which offers real-time balance updates and card control features. The core appeal of this account lies in its combination of no monthly fees, interest earnings on balances, and reimbursement of ATM fees charged by other providers. The account was renamed from Wealthsimple Cash to the Wealthsimple Chequing Account in June 2025, reflecting its expanded functionality.
Key Features and Benefits
The Wealthsimple Chequing Account includes several features that differentiate it from standard bank accounts. It charges no monthly account fees, no minimum balance fees, and no fees for Interac e-Transfers. For international use, the account does not charge a foreign transaction fee, though a currency conversion rate from the payment network still applies. A significant benefit is the unlimited reimbursement of ATM fees worldwide, meaning any fees charged by an ATM operator will be refunded by Wealthsimple. The account also facilitates cash deposits at over 5,300 Canada Post locations and offers low-cost domestic wire transfers for a flat fee of fifteen dollars. Users can order bank drafts through the app, which are then shipped to them, and can deposit cheques by taking photos within the app, with funds typically processed in approximately six business days.
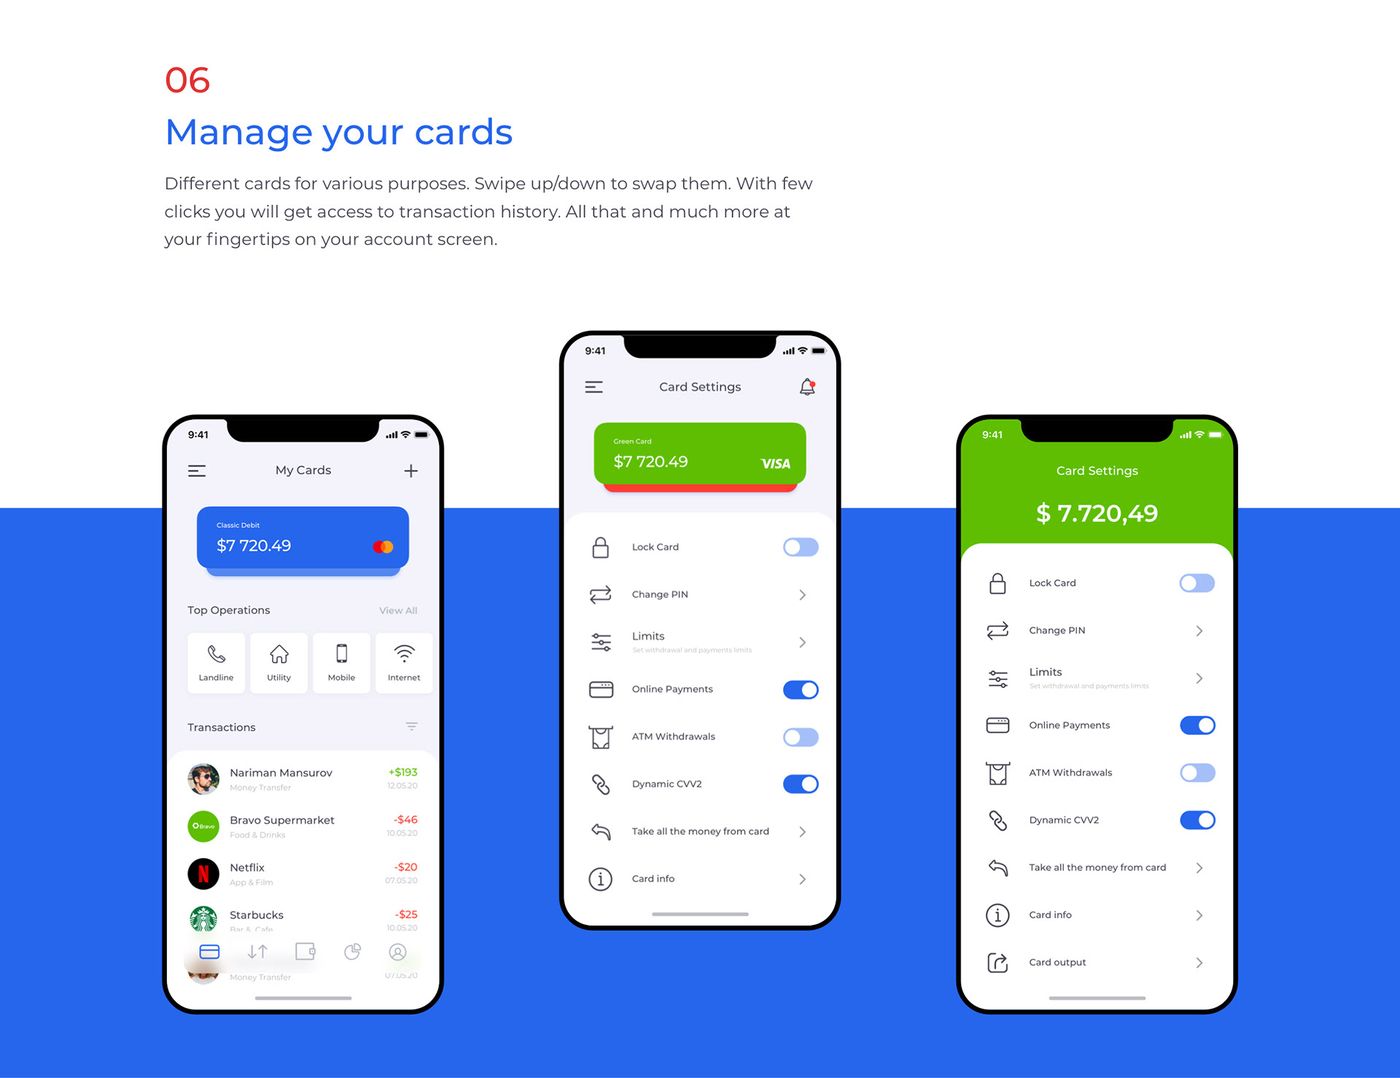
The specific features of the Visa Platinum Prepaid card and account access include several distinct points. The Visa Platinum Prepaid card comes in both a digital and physical form and can be locked or managed directly from the Wealthsimple app. There are no annual fees on the card and it does not require a credit check, and a free chequebook is available if you set up direct deposit of your paycheque into the account. Bank drafts can be ordered through the app and are shipped with a secure tracking link, while instant access to part of a cheque deposit was noted as a feature coming soon. A separate place to spend and receive in USD was also noted as coming soon, and these features collectively aim to replicate many services of a traditional branch within a digital environment.
- The Visa Platinum Prepaid card comes in both a digital and physical form.
- The card can be locked or managed directly from the Wealthsimple app.
- There are no annual fees on the card and it does not require a credit check.
- A free chequebook is available if you set up direct deposit of your paycheque into the account.
- Bank drafts can be ordered through the app and are shipped with a secure tracking link.
- Instant access to part of a cheque deposit was noted as a feature coming soon.
- A separate place to spend and receive in USD was also noted as coming soon.
Interest Rates and How They Work
Interest on the Wealthsimple Chequing Account is calculated daily and paid out monthly, with the annualized rate subject to change based on broader economic conditions. The interest rate is not a promotional rate with a fixed end date but is variable and can adjust if the Bank of Canada changes its policy rates. The specific rate a user earns depends on the total assets they hold with Wealthsimple across all products, following a tiered structure. To unlock the highest advertised rate of 2.25 percent, a user must have at least five hundred thousand dollars in total assets with Wealthsimple. This structure means the account can function as a high-interest savings vehicle, but the yield is directly tied to the user's overall relationship with Wealthsimple.
Account Limits and Management
Wealthsimple allows for significant flexibility in how users organize their money through multiple accounts. An individual can open up to eight personal Wealthsimple Chequing Accounts, and can also open up to eight joint accounts. However, the joint accounts do not come with the Visa Platinum Prepaid card. The prepaid card itself does not require a credit check or impact a user's credit score, as it is not a credit product. The account supports a variety of funding methods including linking an external bank account, Interac e-Transfer, wire transfer, and linking a Mastercard or Visa debit card. Withdrawals can be made at any ATM globally with fee reimbursement, and money can be transferred out to a connected bank account at any time without cost.
The process for opening and funding a Wealthsimple Chequing Account involves several clear steps. First, download the Wealthsimple app and sign up for an account, then provide your personal information to verify your identity. Next, link an external bank account to transfer initial funds and order your physical Visa Platinum Prepaid card if desired. After that, set up direct deposit for your paycheque to qualify for a free chequebook and use the app to deposit cheques by photographing the front and back. Finally, order bank drafts or initiate wire transfers through the app's interface, and once set up, the account is managed entirely through the mobile application.
- Download the Wealthsimple app and sign up for an account.
- Provide your personal information to verify your identity.
- Link an external bank account to transfer initial funds.
- Order your physical Visa Platinum Prepaid card if desired.
- Set up direct deposit for your paycheque to qualify for a free chequebook.
- Use the app to deposit cheques by photographing the front and back.
- Order bank drafts or initiate wire transfers through the app's interface.
Safety, Protection, and What Wealthsimple Is Not
Funds held in the Wealthsimple Chequing Account are held in trust for the client with members of the Canada Deposit Insurance Corporation. This means eligible deposits are protected by CDIC insurance in the event of a failure of the CDIC member institution holding the funds. It is crucial to understand that Wealthsimple itself is not a bank and is not a CDIC member. The protection comes through its partnership with member institutions. As a digital platform without physical branches, all customer service is handled remotely through the app and online channels. Wealthsimple does not offer the full suite of products a traditional bank does, such as personal loans, mortgages, or lines of credit. Its focus is on specific products like this chequing account, investment accounts, and crypto trading.
Fees and Cost Structure
A primary advantage of the Wealthsimple Chequing Account is its lack of many common banking fees. There are no monthly account fees, no transaction fees, and no Interac e-Transfer fees. The account also does not charge foreign transaction fees, though the Visa payment network applies a standard currency conversion rate. For ATM use, Wealthsimple does not charge a fee and reimburses any fees charged by the ATM operator worldwide. For wire transfers, Wealthsimple charges a flat fee of fifteen dollars for outgoing domestic wires, which is noted as one of the lowest flat rates in Canada. There is no fee to receive wires from any location. If a wire arrives in a currency different from the account's currency, it will be converted with a standard foreign exchange fee applied.
Common Considerations and Potential Drawbacks
When evaluating the Wealthsimple Chequing Account, several practical considerations emerge. The interest rate for most users will be lower than the maximum advertised rate, as the top tier requires a substantial asset commitment. Some features noted in promotional materials, such as instant access to cheque deposits or a separate USD spending account, were listed as coming soon, indicating they may not be fully available at all times. As a digital-only service, users must be comfortable managing all banking through an app, with no option for in-person branch assistance. While wire transfers are offered at a low flat fee, the standard processing time for cheque deposits is around six business days, which may be slower than some traditional banks. Furthermore, the company's primary focus has expanded beyond its original robo-advice roots into areas like crypto trading, which may influence the development priorities for its banking products.
Wealthsimple's broader business context includes several facts relevant to potential users. Wealthsimple was founded in 2014 by Michael Katchen, Brett Huneycutt, and Rudy Adler, and the platform now serves more than three million Canadians. Its early focus was on robo-advice and passive investing, but it has since expanded its product range, and Wealthsimple's portfolio returns for its investment products have been noted as lower than some competitors over a five-year period. The company has been critiqued for shifting focus towards crypto trading, and it does not provide access to dedicated portfolio managers for its robo-advice service. The platform is recognized for its polished app and no-minimum entry point, and this evolution means the Chequing Account is one product within a larger, changing financial ecosystem.
- Wealthsimple was founded in 2014 by Michael Katchen, Brett Huneycutt, and Rudy Adler.
- The platform now serves more than three million Canadians.
- Its early focus was on robo-advice and passive investing, but it has since expanded its product range.
- Wealthsimple's portfolio returns for its investment products have been noted as lower than some competitors over a five-year period.
- The company has been critiqued for shifting focus towards crypto trading.
- It does not provide access to dedicated portfolio managers for its robo-advice service.
- The platform is recognized for its polished app and no-minimum entry point.
Comparison with Traditional Banking
The Wealthsimple Chequing Account differs from a standard bank chequing account in several fundamental ways. Traditional banks typically charge monthly fees unless a minimum balance is maintained, while Wealthsimple charges no monthly fees regardless of balance. Major banks often charge fees for Interac e-Transfers, ATM use outside their network, and foreign transactions, all of which are free or reimbursed with Wealthsimple. However, traditional banks offer physical branches for in-person service, a wider range of credit products like loans and mortgages, and often have longer-established reputations. Wealthsimple provides a hybrid model where the account earns interest, a feature usually reserved for separate savings accounts at traditional institutions. The CDIC protection for Wealthsimple deposits is indirect through partner institutions, whereas deposits at a chartered bank are directly insured by the CDIC.
Frequently asked questions
Is Wealthsimple a real bank?
Wealthsimple is not a chartered bank. It is a FINTRAC-registered money services business that offers financial products like the Chequing Account. It does not have physical branches and does not offer traditional bank services like loans. However, client funds in the Chequing Account are held in trust with CDIC member institutions for protection.
Are my savings safe with Wealthsimple?
Eligible deposits in the Wealthsimple Chequing Account are protected. The funds are held in trust for you with members of the Canada Deposit Insurance Corporation, a federal Crown corporation. This means deposits are covered by CDIC insurance in case of a member institution’s failure. It is important to note that Wealthsimple itself is not a bank or a CDIC member, but it partners with member institutions to provide this protection. This safety measure is as solid as that offered by any bank, robo advisor, or brokerage in Canada.
How do I get the 2.25% interest rate?
To unlock the highest interest rate of 2.25% on the Wealthsimple Chequing Account, you need to have at least $500,000 in total assets with Wealthsimple. This is a tiered system, so customers with lower balances receive a different, lower interest rate. The interest is an annualized rate calculated daily and paid out monthly. Wealthsimple states these rates have no set end date, but they are variable and subject to change if the Bank of Canada alters its rates.
Does the Wealthsimple Visa card affect my credit score?
No, the Visa Platinum card provided with the Wealthsimple Chequing Account does not affect your credit score. This is because it is a prepaid card and not a credit card. The card does not require a credit check or any other qualifications for use. Since it is not a credit product, your activity with this card will not be reported to credit bureaus and therefore has no impact on your credit rating, positive or negative.
Can I have a joint chequing account with Wealthsimple?
Yes, you can open a joint chequing account with Wealthsimple. In fact, the platform allows you to open up to eight individual accounts and up to eight joint accounts to help organize your money. However, there is a specific limitation: joint accounts do not come with the Visa Platinum Prepaid card that is available with individual accounts. All other account features and management capabilities are accessible through the Wealthsimple mobile application.
How can I deposit cash into my Wealthsimple account?
You can deposit cash into your Wealthsimple Chequing Account at over 5,300 Canada Post locations across Canada. This service provides a physical method to add funds to your digital account. Additionally, Wealthsimple offers other deposit options such as linking an external bank account, sending an Interac eTransfer, or depositing a cheque by taking a photo in the mobile app. This network helps bridge a common gap for online only financial services.
Sources and further reading
- Canada's most powerful chequing account | Wealthsimple wealthsimple.com
- Wealthsimple Review 2026 - Pros, Cons, Fees & Promo milliondollarjourney.com
- Wealthsimple Chequing Account review finder.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.