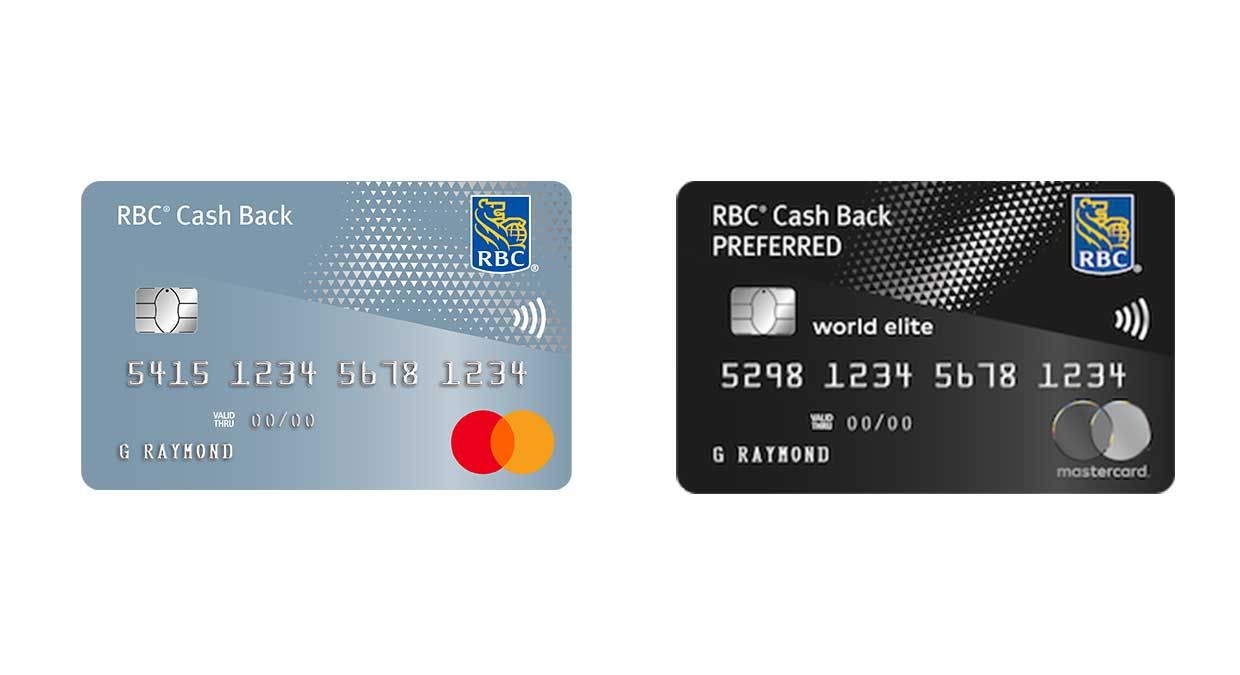
The RBC Cash Back Mastercard is a no annual fee credit card that offers unlimited cash back on all purchases. It is designed to give you rewards on everyday purchases, with a focus on earning cash back on groceries. The card provides an accessible and affordable cash back option, especially for groceries, without an annual fee. It is considered a solid no fee option for those looking to earn cash back on groceries and save on gas at Petro Canada.
How the RBC Cash Back Mastercard Earns Rewards
The RBC Cash Back Mastercard provides unlimited cash back on all eligible net purchases with no maximum limit on the total amount that can be earned. The earn rates are structured around specific purchase categories, which are common in Canadian daily spending. You earn 2% cash back on grocery purchases, but this higher rate applies only to the first $6,000 spent annually in this category. After that threshold is reached within a calendar year, the earn rate on further grocery spending drops to 1%. For purchases related to fuel, electric vehicle charging, rideshare services, and public transit, the card offers a flat 1% cash back rate. All other everyday purchases not falling into these defined categories earn a base rate of 0.5% cash back. This tiered structure means the effective cash back percentage varies depending on a cardholder's spending mix and volume. The card does not have a monthly cap on earnings like some competitors, but the annual cap on the grocery category is a key structural feature.
Rules for Redeeming Your Cash Back
Redeeming the cash back earned with the RBC Cash Back Mastercard involves specific rules and a minimum threshold. You must accumulate at least $25 in cash back rewards before you can initiate a redemption. The primary method for manual redemption is by calling the bank directly, as there is no online or automated redemption option for amounts below the annual auto-redemption. Alternatively, RBC provides an annual auto-redemption feature where your accumulated cash back is automatically credited to your account balance in January, with the transaction appearing on your February monthly statement. This automatic process can be convenient for those who prefer not to manage redemptions manually. You can check your current cash back balance at any time on your monthly credit card statement or by contacting RBC. The $25 minimum for manual redemption is lower than some competitor cards that require $50 and issue a cheque, providing a slight advantage in accessibility.
Additional Benefits and Protections
Beyond cash back, the RBC Cash Back Mastercard includes several standard credit card benefits and insurance coverages. All cardholders receive Purchase Security and Extended Warranty Insurance on eligible items bought with the card. The card also provides access to optional, fee-based services that can be added, such as balance protection insurance, optional travel insurance, identity protection, and roadside assistance. Furthermore, cardholders can access several third-party loyalty program tie-ins. These include earning Triangle Rewards on qualifying purchases at Canadian Tire, Sport Chek, and Mark's, receiving an instant 3 cents per litre discount and 20% more Petro-Points on fuel at Petro-Canada, getting a complimentary DashPass subscription for food delivery for six months with $0 delivery fees on eligible orders, and earning 50 Be Well points on every $1 spent at Rexall pharmacies when the card is linked. These partner offers provide additional value beyond the core cash back program.
Eligibility and Application Process
To apply for an RBC Cash Back Mastercard, you must meet standard Canadian credit card eligibility criteria, which typically involve being of the age of majority in your province, having a Canadian residential address, and meeting RBC's creditworthiness requirements. The application process is conducted online and requires you to provide personal and financial information. You will need to complete the application form, review the card details and associated terms, and submit it for a decision. Approval is not guaranteed and is subject to the bank's assessment of your application. The card is positioned as an accessible product from a major Canadian bank, with the no annual fee making it a candidate for those new to credit cards or those seeking a simple secondary card. The application is designed to be completed quickly online, with a decision potentially available within a short timeframe.
Common Considerations for Cardholders
Prospective and current cardholders should be aware of several key details regarding the RBC Cash Back Mastercard's structure. The 2% cash back rate on groceries is capped, reverting to 1% after $6,000 in annual spending in that category, which is a crucial limit for households with significant grocery budgets. The base earn rate of 0.5% on all other purchases is lower than the flat 1% offered by some competing no-fee cards. The $25 minimum redemption threshold is lower than some competitors that require $50, but redemptions are not instantaneous via online banking and require a phone call for manual processing. The card does not charge an annual fee for the primary cardholder or for additional cardholders, which helps preserve the net value of the cash back earned. The card lacks premium travel benefits, concierge services, and other features found on cards with annual fees, focusing instead on core cash back and basic protections.
Key details to remember include the specific cash back earn rates on different purchase categories. You earn 2 percent cash back on grocery purchases, but this is limited to the first six thousand dollars in annual spending. You earn 1 percent cash back on gas, EV charging, rideshare, and transit purchases. You earn 0.5 percent cash back on all other purchases, and there is no limit on earnings at this standard rate.
- The 2% grocery cash back applies only to the first $6,000 spent per year.
- The earn rate on all other purchases is 0.5%.
- The minimum redemption amount is $25.
- Manual redemption is only available by calling RBC.
- Auto-redemption occurs annually in January.
- There is no annual fee for the primary or additional cardholders.
- Standard insurances include Purchase Security and Extended Warranty.
- The card includes PayPass contactless payment technology.
Comparing Cash Back Rates and Limits
The value of the RBC Cash Back Mastercard can be understood by examining its earn rates and limits. The card offers 2 percent cash back on groceries up to a six thousand dollar annual spending limit, after which the rate drops to 1 percent. For other spending, the base rate is 0.5 percent cash back. This structure means the effective cash back rate can be higher than a flat 1 percent card depending on your spending mix.
For spending outside the bonus categories, the flat 0.5% rate applies regardless of volume. When combined with the 1% rate on gas and transit, the card's overall cash back return depends heavily on a user's spending distribution across these categories. A cardholder spending $500 monthly on groceries and $500 monthly on other categories would earn $120 from groceries at 2% and $30 from other spending at 0.5% over a year, resulting in an effective rate of 1.25% on the total $12,000 annual spend. This demonstrates how the card can outperform a flat 1% no-tier card for consumers with significant grocery expenses.
Position in the Canadian Credit Card Market
The RBC Cash Back Mastercard is positioned as a no-fee cash back card from one of Canada's major banks. It is often compared to other no-fee offerings, such as the Scotiabank Moneyback Visa or the MBNA Smart Cash card. The card's 2% rate on groceries up to a cap is a distinguishing feature not always present in other big bank no-fee products. Some competitor cards may offer a flat 1% cash back on all purchases without tiers, while others may have similar category bonuses with different caps or redemption rules. The card is considered a solid offer from a Big 5 bank, particularly for consumers who prioritize grocery spending and want to avoid an annual fee. It does not include travel insurance or concierge services, which are typical of premium cards with annual fees, focusing its value proposition on straightforward cash back accumulation. The card is seen as part of a trend where major banks are improving their no-fee cash back offerings to be more competitive in the Canadian market.
Frequently asked questions
What is the annual fee for the RBC Cash Back Mastercard?
The RBC Cash Back Mastercard has no annual fee. This applies to the primary cardholder and there are also no annual fees for any additional cardholders added to the account. This makes it an accessible and affordable cash back option that saves on fees. The absence of an annual fee is a key feature highlighted in reviews and promotional materials for this card.
How much cash back do I get on groceries?
You earn 2% cash back on grocery purchases. This higher rate applies only to the first $6,000 you spend annually in this category. After exceeding that $6,000 annual spending limit on groceries, the earn rate on any further grocery purchases drops to 1%. This card is often noted as a good option for those who do groceries, providing a competitive return in that specific category.
How do I redeem my cash back rewards?
You can redeem your cash back once you have accumulated at least $25. The primary method for manual redemption is to call RBC. Alternatively, RBC provides an annual auto-redemption feature where your accumulated cash back is automatically credited to your account balance every January, with the transaction appearing on your February statement. This offers flexibility and ease for cardholders.
What are the cash back rates for the RBC Cash Back Mastercard?
The RBC Cash Back Mastercard offers 2% cash back on groceries, 1% cash back on gas, EV charging, rideshare, and transit purchases, and 0.5% cash back on all other purchases. This structure makes it a strong no fee card for grocery spending. However, the 2% grocery rate applies only to the first $6000 in annual spending, after which it drops to 1%. The card provides unlimited cash back on all purchases with no overall maximum limit on earnings.
What are the main benefits and insurance features of this card?
Key benefits include no annual fee, unlimited cash back, and specific insurance coverage. The card comes with Purchase Security and Extended Warranty Insurance for added peace of mind. Additional perks involve saving 3 cents per litre and earning 20% more Petro Points at Petro Canada stations. Cardholders also have access to optional paid services like balance protection insurance, travel insurance, identity protection, and roadside assistance.
How does the RBC Cash Back Mastercard compare to other no fee cards?
The RBC card is considered one of the better no fee offers from a Big 5 bank, particularly for its 2% cash back on groceries. Some reviews note it is not as strong as the MBNA Smart Cash card, which may be discontinued. It outperforms some competitors like Scotiabank's no fee Momentum card, which offers lower rates. For a user spending $500 monthly on groceries and $500 on other categories, the effective cash back rate can be around 1.25%, which is favourable compared to flat 1% no tier cards.
Sources and further reading
- RBC Cash Back Mastercard Credit Card, No Annual Fee rbcroyalbank.com
- RBC Cash Back MasterCard | Credit card reward programs highinterestsavings.ca
- RBC Cash Back Mastercard Review 2026: Pros & Cons finder.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.