CIBC cash back credit cards allow Canadian cardholders to earn a percentage of their spending back as cash rewards. These cards are designed to reward everyday purchases in categories like groceries, gas, and transportation. The cash back earned has no limit and does not expire, providing a straightforward way to save on regular spending. Understanding how these cards work, their different tiers, and the redemption process is key for Canadians looking to maximize these financial tools.
How CIBC Cash Back Credit Cards Function
CIBC cash back credit cards operate by returning a percentage of the amount spent on eligible purchases to the cardholder. The specific cash back percentage earned varies depending on the particular card product, the category of the purchase, and sometimes the merchant. For example, purchases in categories like gas and groceries often earn a higher cash back rate compared to other everyday spending. The cash back accumulates automatically in the cardholder's account as they make purchases with their card. There is no cap on the total amount of cash back that can be earned over time, allowing for unlimited rewards potential.
Cardholders can check their accumulating cash back balance at any time through CIBC Online Banking or the CIBC Mobile Banking App. The balance is also displayed on the monthly credit card statement. It is important for users to review their card's specific benefits document to understand the full eligibility details for cash back earnings. The system is designed to be passive. Cardholders do not need to activate the rewards for each transaction. However, ensuring purchases are made at eligible merchants and fall within the defined categories is necessary to earn the advertised rates.
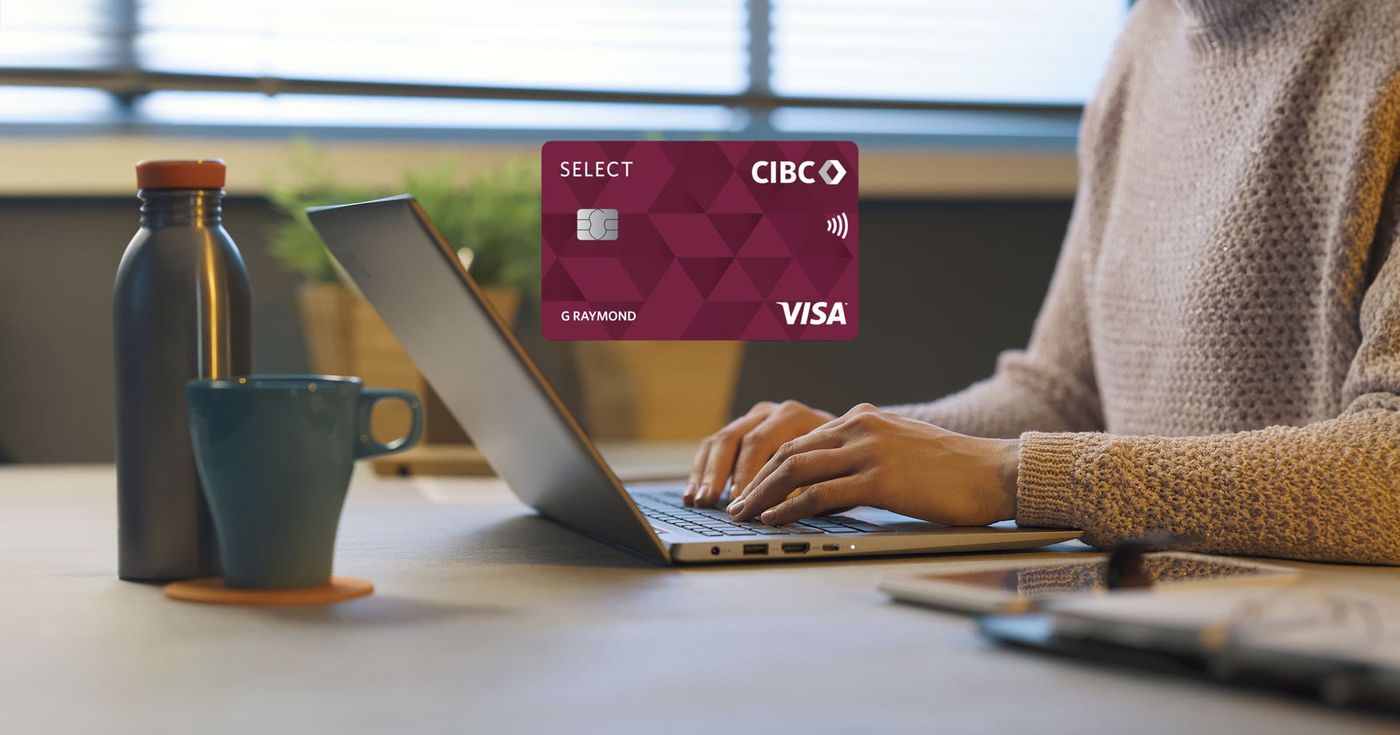
Redeeming Your CIBC Cash Back Rewards
The process for redeeming cash back differs slightly between CIBC's standard Dividend cards and the co-branded CIBC Costco Mastercard. For CIBC Dividend credit cards, once the cash back balance reaches a minimum of $10, the cardholder can redeem the full amount at any time. Redemption can be completed through CIBC Online Banking, the CIBC Mobile Banking App, or by calling the customer service line. The redeemed amount is typically credited directly to the cardholder's credit card account, effectively reducing their outstanding balance.
For the CIBC Costco Mastercard, cash back is distributed as an annual gift certificate. To be eligible, the cardholder must have an account in Good Standing and an active Costco membership as of December 31 of the previous year. The cash back gift certificate is issued every January and can be accessed digitally through the CIBC Mobile Banking App for use in Canadian Costco warehouses, printed via CIBC Online Banking, or received as part of the January statement. If the account is not eligible, the cash back earned in the previous year is forfeited.
- CIBC Dividend Cards: Redeem any time balance reaches $10.
- CIBC Dividend Redemption Channels: Online Banking, Mobile App, phone.
- CIBC Costco Mastercard: Annual gift certificate issued in January.
- Costco Redemption Eligibility: Account in Good Standing and active membership as of December 31.
Comparing CIBC Cash Back Card Tiers and Features
CIBC offers a range of cash back credit cards, from no-annual-fee options to premium cards with higher reward rates and additional benefits. Cards without an annual fee, such as the basic CIBC Dividend Visa, provide a simple entry point for earning cash back on daily purchases. These cards typically offer a flat cash back rate on all spending or tiered rates on specific categories. The trade-off for the lack of an annual fee is often a lower cash back percentage compared to premium cards.
Premium cash back cards, like the CIBC Dividend Visa Infinite, usually carry an annual fee but offer significantly higher cash back rates on targeted spending categories. For instance, this card may offer 4% cash back on eligible gas and grocery purchases and 2% on other categories. These cards may also come with additional perks such as travel insurance, extended warranty protection, and access to CIBC Pace It Installment Plans. The value proposition hinges on whether the increased cash back and benefits outweigh the cost of the annual fee for the cardholder's specific spending patterns.
| Card Type | Common Feature | Consideration |
|---|---|---|
| No Annual Fee Cards | Simple daily rewards | Lower cash back rates |
| Premium Annual Fee Cards | Higher cash back percentages | Annual fee cost |
| All Cash Back Cards | Unlimited earnings, no expiry | Spending category eligibility |
Eligibility and Account Management Details
To earn and redeem cash back with a CIBC card, the primary account must be maintained in Good Standing. This generally means making at least the minimum payment by the due date each month. For the CIBC Costco Mastercard, maintaining an active Costco membership is an additional, non-negotiable requirement for receiving the annual cash back certificate. Cardholders can add additional users to their account, and all purchases made by these additional cardholders will earn cash back for the primary account. The rewards from all cards on the account are pooled together, which can help the primary cardholder reach the redemption threshold faster.
Cardholders are responsible for understanding the terms and conditions associated with their specific card, including any spending caps or limits that may apply to bonus cash back categories. The advertised cash back rates, such as 4% on gas or 2% on dining, apply only to purchases that CIBC defines as eligible within those categories. Transactions at merchants that are not classified under these categories will earn the standard, lower cash back rate. Regularly monitoring statements and the online banking portal is the best way to track earnings and ensure they align with expectations.
Strategic Use of Cash Back Cards for Canadian Spend
Maximizing cash back from a CIBC card involves aligning the card's reward structure with personal or household spending habits. The most effective strategy is to select a card that offers higher cash back rates in the categories where you spend the most money each month. For a household with significant grocery and fuel expenses, a card offering 3% or 4% cash back on those categories would be a logical match. Using the card for all eligible purchases in those high-rate categories ensures the highest possible return.
It is financially critical to pay the credit card balance in full each month to avoid interest charges. Interest fees can quickly negate the value of any cash back earned. Cash back should be viewed as a reward for planned spending, not as an incentive to spend beyond one's means. For those who carry a balance, a low-interest credit card may be a more suitable financial product than a rewards card. Furthermore, comparing the card's annual fee against the projected annual cash back earnings is a necessary calculation to determine if the card provides net value.
- Align card choice with highest personal spending categories.
- Use the card for all eligible purchases in high-rate categories.
- Pay the statement balance in full monthly to avoid interest.
- Calculate if projected annual cash back exceeds the annual fee.
Common Considerations and Potential Mistakes
A common oversight is not reviewing the specific eligibility rules for bonus cash back categories. For example, a grocery store may house a pharmacy, bakery, or prepared food counter that codes as a different merchant category, resulting in a lower cash back rate for those specific transactions. Another mistake is carrying a balance and incurring interest, which typically far exceeds the value of cash back earned. Cardholders should treat cash back as a secondary benefit to responsible credit use, not a primary financial goal.
For CIBC Costco Mastercard holders, a significant risk is allowing the Costco membership to lapse or failing to meet the account standing requirements by the December 31 cutoff. This results in the forfeiture of all cash back earned in the entire previous year. Additionally, some cardholders may not redeem their cash back in a timely manner, although with CIBC Dividend cards, the lack of expiry makes this less urgent. However, allowing cash back to sit idle does not generate additional value, so regular redemption is a good practice.
Frequently asked questions
How do I redeem cash back from my CIBC Dividend credit card?
You can redeem your CIBC Dividend cash back once the balance reaches $10 or more. Redemption is available at any time through CIBC Online Banking and the CIBC Mobile Banking App. You can also call 1 800 465 4653 to request a redemption. The full amount will be credited directly to your credit card account. There is no limit to how much cash back you can earn and your rewards never expire. This process allows you to access your earned rewards conveniently whenever you choose.
When do I get my cash back from the CIBC Costco Mastercard?
You receive your cash back from the CIBC Costco Mastercard as an annual gift certificate every January. Eligibility requires your account to be in Good Standing and your Costco membership to be active as of December 31 of the previous year. You can access this certificate digitally in Canadian Costco warehouses using the CIBC Mobile Banking App or print it through CIBC Online Banking. It is also included in your January statement. If your account is not eligible, you will lose the cash back earned in the previous year.
Is there a limit to how much cash back I can earn with CIBC cards?
No, there is no limit to the total cash back you can earn with CIBC cash back credit cards. The amount you earn depends on your card type and spending habits. Your cash back rewards never expire, allowing for unlimited accumulation over time. The more you use your card, especially in higher earning categories, the more cash back you will accumulate. This feature ensures you are rewarded for all your eligible purchases without any cap on potential earnings.
Do additional cardholders on my account earn cash back?
Yes, all additional cardholders on your CIBC cash back credit card account earn cash back for you. Their purchase rewards are pooled into your single account. This pooling helps you accumulate cash back faster and reach the redemption threshold more quickly. As the primary cardholder, you manage the combined rewards from all cards. This feature maximizes the earning potential from household or family spending on a single account.
How can I check my CIBC cash back balance?
You can check your cash back balance anytime through CIBC Online Banking or the CIBC Mobile Banking App. Handle to your Credit Card Account Details to access this information. Your accumulating cash back rewards are also displayed on your monthly credit card statement. These methods provide convenient and current views of your earned rewards, allowing you to track your progress toward the $10 redemption threshold.
What happens if my CIBC Costco Mastercard account is not in Good Standing by December 31?
If your CIBC Costco Mastercard account is not in Good Standing or your Costco membership is not active as of December 31, you will not be eligible for that year's cash back gift certificate. Consequently, you will lose the cash back earned in the previous year. The gift certificate is issued annually in January only when both account and membership conditions are met. This policy underscores the importance of maintaining account standing for reward retention.
Sources and further reading
- Cash Back Credit Cards in Canada cibc.com
- Canada's best cash back credit cards 2026 ratehub.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.