Buying an apartment in Toronto typically means purchasing a condominium unit, which involves acquiring a private space and a share of the building's common elements. This process is governed by Ontario's Condominium Act, 1998, and requires careful financial planning and due diligence. The Toronto market in 2025 to 2026 presents a more approachable entry point, with median asking prices for condos at $638,000, down about 7% year-over-year. Understanding the full scope of ownership costs, legal obligations, and market conditions is essential for any prospective buyer in Canada's largest city.
Understanding Condominium Ownership in Ontario
When you purchase a condo apartment in Toronto, you are buying two things: the specific unit and a share of the common elements of the building. The common elements include all shared spaces such as hallways, elevators, lobbies, parking garages, and amenities like gyms or pools. This shared ownership model is managed by a condominium corporation, which every unit owner automatically becomes a member of. The corporation is run by a board of directors elected by the owners, and it is responsible for setting budgets, hiring property management, and enforcing the rules known as the declaration, bylaws, and rules. The legal framework for this entire system is established by the Condominium Act, 1998, which outlines the rights and responsibilities of both corporations and owners. This structure offers the benefit of shared amenities and reduced personal maintenance but requires owners to cede some control over their property and contribute to collectively determined costs.
Ontario law recognizes several types of condominiums, though most Toronto buyers will encounter standard residential condos. Other forms include phased condominiums, where a development is built in stages, vacant land condominiums, and common elements condominiums. The purchase process differs significantly between buying a resale unit from an existing owner and buying a preconstruction unit directly from a builder. A resale purchase allows you to inspect the actual unit and review the building's status certificate before committing, while a preconstruction purchase involves buying based on plans, often years before occupancy, which carries different risks and consumer protections.
Current Toronto Condo Market Conditions
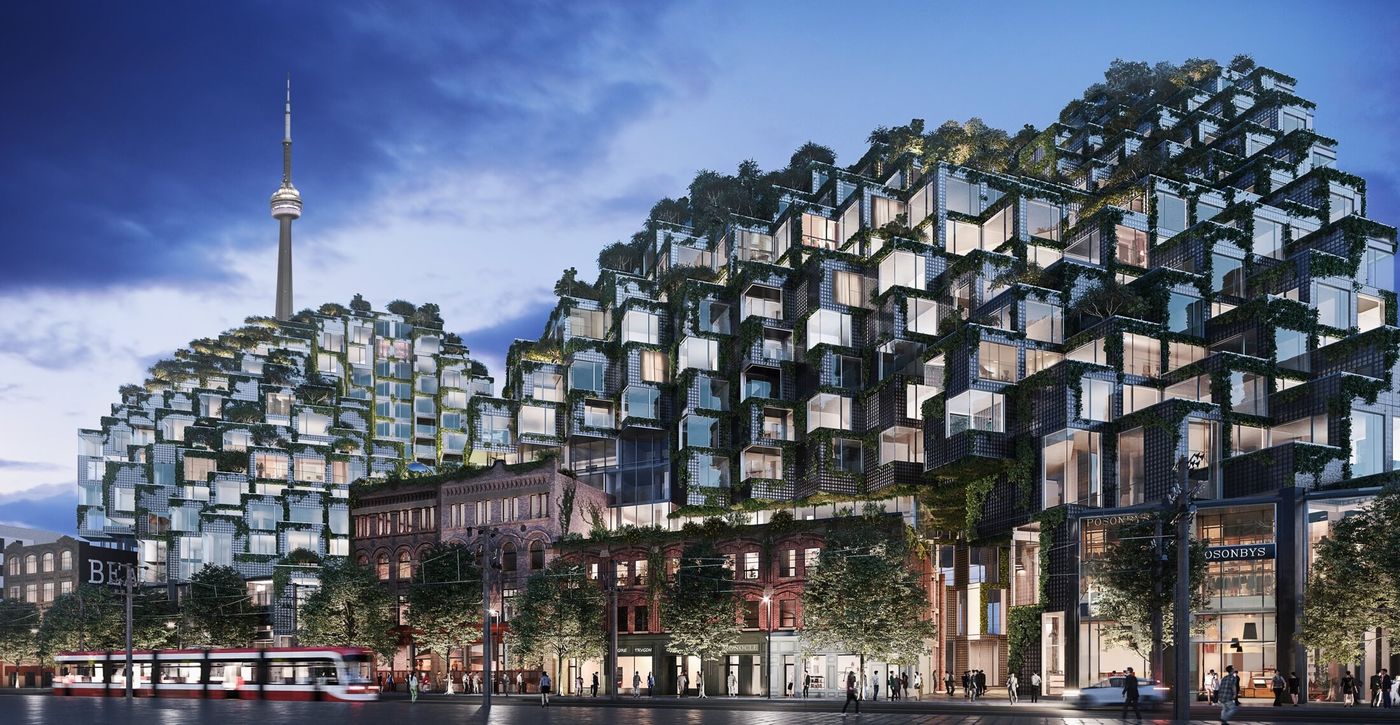
The Toronto condo market in 2025 and 2026 is characterized by increased affordability and selection for buyers. The median asking price for condos in Toronto is $638,000, which represents a decline of about 7 percent compared to the previous year. This softening in prices has created a more approachable entry point, particularly for first-time buyers and investors. Data from the Toronto Regional Real Estate Board showed the average Greater Toronto Area condo apartment price was near $653,000 in the fourth quarter of 2025, down approximately 5 percent year-over-year. By April 2026, the average price was around $636,000, still down roughly 6 percent from the same period a year earlier.
This market adjustment is most pronounced in the downtown core, where prices have fallen close to 20 to 30 percent from their early 2022 peak. With over 7,200 condos currently listed on the Toronto MLS®, buyers have a wider selection across the city's 143 neighbourhoods. This environment provides more negotiating room for purchasers with secure financing. However, softer resale values can also put financial pressure on a condominium corporation's reserve fund, making thorough due diligence on a building's financial health especially important during this period.
Key Financial Considerations and Closing Costs
The purchase price of a condo is only the starting point of your financial commitment. Buyers must budget for significant closing costs, which typically range from 1.5 to 4 percent of the purchase price. A major component is land transfer tax (LTT). In Ontario, a provincial land transfer tax applies to all property purchases. Additionally, the City of Toronto charges its own municipal land transfer tax, making Toronto the only municipality in Ontario where buyers pay two separate LTT charges. First-time home buyers are eligible for rebates on these taxes. The provincial government offers a refund of up to $4,000, and the City of Toronto offers a refund of up to $4,475, for a potential total rebate of $8,475 for eligible first-time buyers in Toronto.
To qualify for these first-time buyer rebates, you must be at least 18 years old, a Canadian citizen or permanent resident, occupy the home as your principal residence within nine months of purchase, and must never have owned a home anywhere in the world before. The application must be submitted within 18 months of the closing date, and your lawyer typically handles the claim during the registration process. For new construction condos purchased from a builder, Harmonized Sales Tax (HST) applies. Builders usually include the standard new housing rebate in the quoted price for owner-occupiers, while investors must claim it differently. New federal and provincial rebates introduced in 2026 can remove much of the HST for first-time buyers of new homes priced under $1 million, with partial relief available for units up to $1.5 million.
Ongoing Costs of Condo Ownership
After closing, condo owners face recurring monthly expenses. The most significant is the common element fee, also known as maintenance fees. This monthly charge covers the operating costs of the building, including upkeep of common areas, building insurance, staff salaries, utilities for shared spaces, and contributions to the reserve fund. Fees vary widely and generally increase with a building's age, the number and type of amenities (like pools or concierge services), and the overall size of the complex. Older buildings or those with expensive aging systems typically have higher fees. All owners are legally obligated to pay these fees, and the condominium corporation can place a lien on a unit for non-payment.
A critical financial risk for owners is the special assessment. This is a one-time charge levied by the condominium board when the reserve fund is insufficient to cover a major, unexpected repair, such as replacing elevators, repairing a parking garage, or fixing a building envelope. Special assessments can amount to thousands of dollars per unit. For buyers of preconstruction condos, an additional cost phase exists called interim occupancy. During this period, which can last several months, you may occupy the unit before the building is legally registered, and you pay an occupancy fee to the builder. This fee, sometimes called phantom rent, covers the builder's estimated property taxes, interest on the unpaid balance of the purchase price, and projected common expenses, but it does not contribute to building equity.
Essential Steps in the Buying Process
The process of buying a condo in Toronto involves several critical steps that extend beyond a typical home purchase. It begins with setting a realistic budget that accounts for your down payment, mortgage qualification, and all associated closing and ongoing costs. Obtaining a mortgage pre-approval is a crucial early step to understand your purchasing power. Once you begin viewing properties, it is vital to conduct thorough due diligence, especially for resale units. The most important document in a resale purchase is the status certificate, which provides a snapshot of the condominium corporation's financial and legal health. This document should be reviewed by a qualified real estate lawyer before you waive any related conditions in your offer.
- Set your budget, including savings, income, debts, and all projected ownership costs.
- Obtain a mortgage pre-approval or approval in principle from a lender.
- Search MLS® listings and view properties, considering neighbourhood, building amenities, and lifestyle fit.
- For resale condos, review the status certificate with a lawyer to check the reserve fund, legal issues, and upcoming special assessments.
- Make an offer, typically conditional on financing and status certificate review.
- Secure final mortgage approval and fulfill all other conditions.
- Work with a real estate lawyer to complete closing, register the deed, and handle land transfer tax rebates.
For preconstruction condo purchases, due diligence focuses on the builder's reputation and the terms of the purchase agreement. Buyers must also review the projected timeline for occupancy and final closing. Engaging a real estate lawyer experienced in Ontario condominium law is strongly recommended at an early stage. A lawyer can guide you through the specific legalities of a preconstruction purchase. This legal advice is important to protect your interests whether you are buying new or resale.
Common Pitfalls and How to Avoid Them
Several common mistakes can lead to financial strain or dissatisfaction for new condo buyers. A frequent error is underestimating the total cost of ownership by focusing solely on the purchase price and mortgage payment while neglecting closing costs, monthly common element fees, and potential special assessments. Buyers should carefully review the condominium's budget and reserve fund study, which is part of the status certificate, to assess the building's financial stability and likelihood of future fee increases or special levies. Another pitfall is failing to thoroughly understand the rules and restrictions outlined in the corporation's declaration, bylaws, and rules. These documents govern everything from pet ownership and balcony use to renovation policies and rental restrictions, which can significantly impact your intended use of the property.
For those considering preconstruction, risks include construction delays, changes to the final unit specifications, and the financial burden of the interim occupancy period where you pay fees without building equity. Investors must be particularly mindful of rental restrictions that some buildings impose, limiting the number of units that can be leased at any one time. Lastly, not using a qualified real estate lawyer who specializes in condominium transactions can leave a buyer exposed to unseen legal and financial liabilities within the complex corporate structure of condo ownership. A lawyer's review of the status certificate for a resale purchase or the purchase agreement for a new build is not a mere formality but a critical protective measure that can prevent costly surprises after closing.
Frequently asked questions
What is the average price of a condo in Toronto?
As of 2025, the median asking price for a condo apartment in Toronto is $638,000, which is down about 7% from the previous year. The average price in the Greater Toronto Area was approximately $653,000 in the fourth quarter of 2025. That average price declined to around $636,000 by April 2026. Prices in the downtown core have seen more significant decreases from their early 2022 peak.
What are the land transfer tax costs for first-time buyers in Toronto?
First-time home buyers in Toronto are eligible for rebates on both the provincial and municipal land transfer taxes. The provincial government offers a refund of up to $4,000, and the City of Toronto offers a refund of up to $4,475. This means an eligible first-time buyer can receive a total rebate of up to $8,475. To qualify, you must be 18 or older, a Canadian citizen or permanent resident, move in within 9 months, and have never owned a home anywhere.
What is a status certificate and why is it important?
A status certificate is a crucial document issued by the condominium corporation. It provides a detailed snapshot of the corporation's financial and legal health. The document includes information on the budget, reserve fund balance, and any planned special assessments. Reviewing this document with a lawyer before purchasing a resale condo is a standard conditional clause in an offer.
What are monthly common element fees?
Common element fees are monthly charges paid by all condo owners to the condominium corporation. These fees cover the operating costs of the building's shared areas like hallways and lobbies. They pay for cleaning, repairs, building insurance, staff salaries, and utilities for common spaces. The fees also include contributions to the reserve fund for future major repairs.
What is the difference between buying resale and preconstruction?
Buying a resale condo involves purchasing an existing unit from a current owner. You can physically inspect the unit, review the building's status certificate, and often take possession quickly. Buying preconstruction means purchasing a unit from a builder before or during construction, often based on plans. This path can involve lower initial deposits and the potential for price appreciation but carries risks like construction delays, interim occupancy fees, and uncertainty about the final product.
What is a special assessment?
A special assessment is a one-time charge levied by the condominium corporation on all unit owners. It occurs when the reserve fund is insufficient to pay for a major necessary repair or replacement project. Examples include replacing roofing, windows, or elevators. These assessments can be substantial and cost thousands of dollars per unit.
Sources and further reading
- 6911 Condos For Sale in Toronto condos.ca
- Apartments for sale in Toronto engelvoelkers.com
- Buying Condo in Toronto: Comprehensive Guide insightlawfirm.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.