BMO cash back credit cards offer Canadians a way to earn rewards on everyday purchases, with options ranging from no-fee cards to premium products. These cards provide higher cash back rates in specific spending categories like groceries, transit, and gas. The value of a card depends heavily on an individual's spending patterns and ability to meet any eligibility requirements. Understanding the specific earn rates, caps, fees, and welcome offers is essential for determining which, if any, BMO cash back card aligns with a personal budget.
Understanding BMO Cash Back Card Options
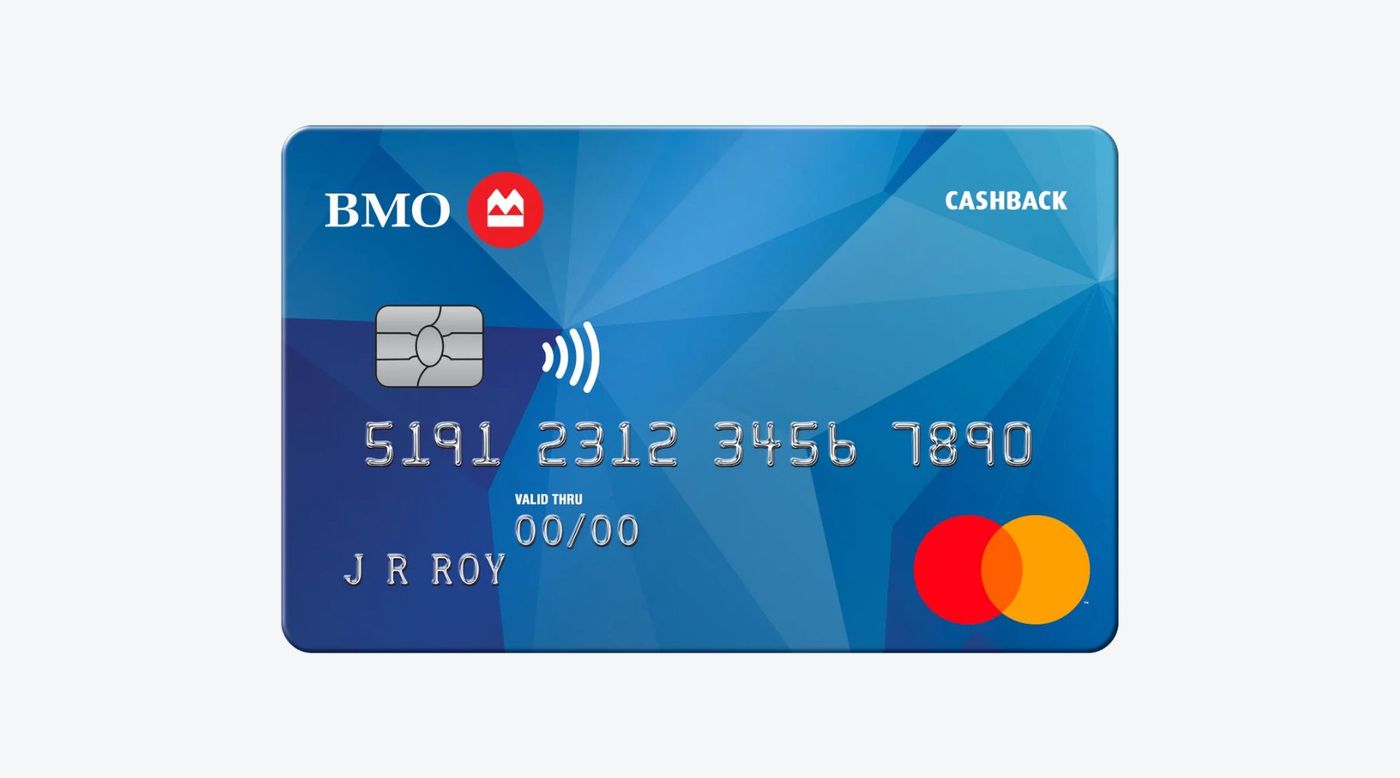
Bank of Montreal offers a selection of cash back credit cards catering to different financial needs and spending habits. The lineup includes the no-annual-fee BMO CashBack Mastercard and the premium BMO CashBack World Elite Mastercard, which carries a $139 annual fee. These cards are distinct from BMO's travel rewards and low-interest cards, such as the BMO Ascend World Elite Mastercard or the BMO Preferred Rate Mastercard. The primary appeal of the cash back cards is their straightforward reward structure, providing a percentage back on purchases without the complexity of points programs. Choosing between them involves weighing the higher earn rates and additional perks of the premium card against its annual fee and income requirements. BMO's portfolio is broad, but its rewards programs are not interchangeable, with cash back being the simplest option for direct monetary returns.
Detailed Earn Rates and Spending Caps
BMO cash back cards offer tiered earn rates that reward spending in specific categories more heavily. The BMO CashBack World Elite Mastercard provides 5% cash back on grocery purchases, 4% on transit including taxis, ride share and public transit, 3% on gas and electric vehicle charging, and 2% on recurring bills. All other purchases earn a flat 1% cash back. The no-fee BMO CashBack Mastercard offers 3% cash back on groceries, with other purchases earning 1%. These higher rates are subject to monthly spending caps. For the no-fee card, the 3% grocery rate applies only to the first $500 spent per billing cycle. The premium card's 5% grocery rate is also capped at $500 per billing cycle. The 4% cash back on transit and 3% on gas for the World Elite card are also subject to their own spending caps.
The caps are a defining feature that significantly impacts the card's value proposition. After exceeding the cap, spending in that category earns the base rate of 1%. This structure makes these cards most suitable for individuals or families whose spending in bonus categories aligns with or falls below these monthly limits. The flat 1% earn rate on all other purchases is a standard offering but is considered a poor base rate compared to some competing cards. For those who regularly spend more than the caps, a card without such limits or with a higher flat rate might yield more overall cash back. The BMO CashBack Mastercard's 3% rate on groceries is noted as the best standard rate for this category among no-fee cards in Canada, but the $500 monthly cap is a key limitation.
Fees, Interest Rates, and Welcome Offers
Annual fees and interest rates are key cost factors. The BMO CashBack Mastercard has a $0 annual fee, while the BMO CashBack World Elite Mastercard has a $139 annual fee, which is often waived for the first year as part of a welcome offer. The standard purchase interest rate for these cards can be as high as 23.99% after any promotional period ends. Both cards feature promotional balance transfer offers, which are a separate product feature from cash back earnings. The no-fee card offers a 0.99% introductory rate on balance transfers for the first 9 months with a 2% transfer fee, reverting to 23.99%. The premium card offers a 0.00% rate for the first 12 months with a 2% fee, then 23.99%.
Welcome offers are designed to attract new applicants and can add substantial initial value. A common offer for the BMO CashBack Mastercard is 5% cash back on all purchases for the first three months. For the BMO CashBack World Elite Mastercard, a welcome offer may include up to $480 in bonus cash back alongside the first-year annual fee waiver. Another advertised welcome offer for the World Elite card includes up to $650 in value with the annual fee waived. These offers are promotional and have specific terms and conditions. The higher earn rates during welcome periods are temporary, and the standard earn structure and fees apply thereafter. The BMO Preferred Rate Mastercard has a different welcome offer structure with a 0% introductory interest rate on Balance Transfers for 18 months with a 3% transfer fee and a waiver of its $29 annual fee for the first year.
Eligibility and Approval Considerations
Eligibility requirements differ markedly between BMO's cash back cards. The no-fee BMO CashBack Mastercard has no stated minimum personal income requirement, making it accessible to students, newcomers, or those with lower incomes seeking to build credit. The BMO CashBack World Elite Mastercard is a premium product with higher eligibility thresholds, typically requiring a substantial personal annual income. The BMO Ascend World Elite Mastercard also has high annual income criteria. Applicants must also meet BMO's creditworthiness standards, which involve an assessment of credit history and score. Approval is not guaranteed even if income thresholds are met, as the bank conducts a full credit review.
For those who may not qualify for the World Elite card, the no-fee version or other BMO products like the BMO Preferred Rate Mastercard could be alternatives. The BMO Preferred Rate Mastercard focuses on a lower ongoing interest rate of 15.99% after its promotional period, which may be more valuable than cash back for individuals who occasionally carry a balance. The card lineup also includes products like the BMO eclipse rise Visa Card for those seeking no annual fee, and the BMO Blue Rewards World Elite Mastercard for collectors in that partner ecosystem. The best BMO credit card depends less on the bank itself than on the kind of value you want, whether that is simple cash back, flexible points, partner rewards, or lower borrowing costs.
How to Redeem Cash Back Rewards
Redeeming cash back from BMO cards is designed to be flexible and straightforward. Cardholders can redeem their accumulated cash back rewards into an eligible BMO chequing or savings account. This direct deposit method provides immediate access to the funds, which can then be used for any purpose. The redemption process is typically managed through online banking or the BMO mobile app, allowing for convenient access to rewards. Cash back does not expire as long as the account remains open and in good standing. This eliminates the need to track expiry dates or worry about devaluation of points. The simplicity of cash back as a reward currency is a major selling point, as it has a clear and fixed dollar value. Cardholders should regularly review their cash back balance and redemption options within their BMO banking portal to ensure they are utilizing their earnings.
Comparing BMO Cash Back to Other BMO Cards
BMO's credit card portfolio extends beyond cash back to include travel rewards, partner-based points, and low-interest cards. The BMO Ascend World Elite Mastercard earns flexible BMO Rewards points, best suited for travel redemptions, and includes perks like airport lounge access and a NEXUS statement credit. It offers 5 BMO Rewards points per dollar spent on eligible travel purchases and 3 points per dollar on dining and entertainment. The BMO eclipse Visa Infinite card earns 5 points per dollar on groceries, restaurants, food delivery, gas, and transit. The BMO Blue Rewards World Elite Mastercard is integrated with the Blue Rewards partner ecosystem, earning points at participating partners. The BMO Preferred Rate Mastercard offers a low 15.99% interest rate on purchases after its promo period and a $29 annual fee. The table below outlines key differences between a primary cash back card and other notable BMO card types.
| Card Name | Primary Reward Type | Key Feature |
|---|---|---|
| BMO CashBack World Elite Mastercard | Cash Back | 5% back on groceries (capped) |
| BMO Ascend World Elite Mastercard | BMO Rewards Points | Travel insurance, lounge passes |
| BMO eclipse Visa Infinite | BMO Rewards Points | 5x points on food/transit |
| BMO Blue Rewards World Elite Mastercard | Blue Rewards Points | Partner offers, auto perks |
| BMO Preferred Rate Mastercard | Low Interest | 15.99% purchase rate |
The choice between these cards depends entirely on an individual's financial behaviour. A cash back card is optimal for simple, tangible rewards on daily spending. A travel points card is better for those who travel frequently and can utilize the specific perks. A low-interest card is a financial management tool for those concerned about carrying a balance. BMO's rewards programs are not interchangeable, so understanding the core utility of each is essential. The BMO CashBack World Elite Mastercard is considered the strongest BMO option for people who want straightforward rewards and spend enough in its bonus categories to justify the annual fee.
Common Mistakes and Considerations
Several common mistakes can diminish the value of a BMO cash back card. The most significant is overlooking the monthly spending caps on bonus categories. Another error is carrying a balance while focusing on cash back earnings. Given the high standard purchase interest rates of up to 23.99%, the finance charges incurred can quickly surpass any cash back earned, negating the card's benefit. Failing to redeem cash back rewards is an unnecessary loss, as the funds remain with the bank instead of in the cardholder's account.
Applying for a premium card without meeting the income or credit requirements can result in a declined application, which may temporarily impact one's credit score. Not accounting for the annual fee after the first-year waiver can lead to an unexpected cost. Cardholders should annually assess whether their earned cash back exceeds the fee to justify keeping the card. It is also prudent to review the card's insurance benefits, such as purchase protection or extended warranty, to understand the full scope of coverage. The BMO CashBack World Elite Mastercard is one of the few cards that offers free roadside assistance, which is a valuable perk for some users. For students or those with limited spending, the no-fee BMO CashBack Mastercard may be a sensible choice, but its rewards are capped monthly, so big spenders might find it less suitable.
Additional Features and Cardholder Perks
Beyond cash back earnings, some BMO cards come with additional features that can provide value. The BMO CashBack World Elite Mastercard includes free roadside assistance, which is not typical for cash back credit cards. It also offers Zero Dollar Liability protection against unauthorized purchases. The premium BMO Ascend World Elite Mastercard provides a full suite of travel insurance, complimentary Mastercard Travel Pass provided by DragonPass with four free annual airport lounge visits, and a NEXUS application fee credit. The BMO eclipse Visa Infinite Privilege card offers an annual $200 lifestyle credit that effectively reduces its high annual fee.
The BMO Blue Rewards World Elite Mastercard provides lounge access, free roadside assistance, and bonus earn rates on travel purchases through its partner ecosystem. The BMO Preferred Rate Mastercard comes with extended warranty and purchase protection. These ancillary benefits can tip the scales when comparing cards, especially if they align with a cardholder's lifestyle. However, they are often attached to cards with annual fees, so their utility must be weighed against that cost. For a cardholder who never travels, lounge access has no value, making a simpler cash back card a more logical choice.
Target Audience and Final Recommendations
The BMO CashBack Mastercard is targeted at individuals seeking a no-fee card with a strong grocery rewards rate, including students and those establishing credit. Its 3% cash back on groceries up to $500 per month is its standout feature. The BMO CashBack World Elite Mastercard is best for higher-income cardholders who want a simple, category-heavy cash back card and spend significantly on groceries, transit, and gas without exceeding the monthly caps. It is also suitable for those who value its added perks like roadside assistance.
The BMO Ascend World Elite Mastercard is aimed at travellers who want flexible points, modest lounge access, and insurance without tying themselves to one airline. The BMO Blue Rewards World Elite Mastercard makes the most sense for existing Blue Rewards collectors who will use partner offers and bonus categories. The BMO Preferred Rate Mastercard is a good option for those looking for a credit card with a low interest rate and additional benefits, particularly for managing debt. The best BMO credit card for any individual is the one whose reward structure, fees, and perks most closely match their spending personality and financial goals.
Frequently asked questions
What is the best BMO credit card for cash back?
BMO offers two primary cash back cards: the no-annual-fee BMO CashBack Mastercard and the premium BMO CashBack World Elite Mastercard. The 'best' card depends on your spending and financial situation. The no-fee card offers 3% cash back on groceries up to $500 monthly. The premium card offers 5% on groceries, 4% on transit, and 3% on gas, but has a $139 annual fee and higher income requirements.
Is there a limit on how much cash back I can earn with BMO cards?
Yes, the higher cash back rates on bonus categories have monthly spending caps. For both the no-fee and premium cash back cards, the higher grocery cash back rate applies only to the first $500 spent per billing cycle. Spending beyond that cap in the same category earns the base rate of 1%. There is no specified overall limit on total cash back earned.
How does the BMO CashBack card compare for grocery spending?
The BMO CashBack Mastercard's 3% rate on groceries is noted as one of the best standard rates among no-fee cards in Canada. The BMO CashBack World Elite Mastercard offers a market-leading 5% rate. Both rates are capped at $500 in monthly grocery spending. If your grocery spending consistently exceeds this cap, the effective reward rate decreases, which may make other cards without such caps more suitable.
Does the BMO CashBack Mastercard have an annual fee?
No, the standard BMO CashBack Mastercard has a $0 annual fee. The BMO CashBack World Elite Mastercard, which offers higher earn rates and additional features, has a $139 annual fee. This fee is often waived for the first year as part of a welcome offer for new cardholders. The entry level BMO CashBack Mastercard has no annual fee or income requirements, making it accessible for many cardholders. In contrast, the premium World Elite version includes extra features but comes with an annual cost after any promotional period.
Can I use BMO cash back to pay my credit card bill?
Yes, you can indirectly use BMO cash back to pay your credit card bill. The cash back rewards are typically redeemed by depositing them into an eligible BMO chequing or savings account. Once the funds are in your bank account, you can use them for any purpose, including making a payment toward your credit card balance. The BMO CashBack Mastercard specifically offers flexible redemption options, including redeeming your cash back into a BMO account. This process is managed through BMO's online or mobile banking platforms.
What is the welcome offer for BMO cash back cards?
Welcome offers for BMO cash back cards vary by specific card. For the BMO CashBack Mastercard, a common offer is 5% cash back on all purchases for the first three months. After that promotional period, you earn 3% cash back on grocery purchases. For the BMO CashBack World Elite Mastercard, a welcome offer may include up to $480 in bonus cash back and the $139 annual fee waived for the first year. Other offers for this card can include up to $650 in value with the annual fee waived and a 0% introductory interest rate on balance transfers.
Sources and further reading
- The best BMO credit cards in Canada 2026 ratehub.ca
- Best BMO Credit Cards in Canada nerdwallet.com
- The best BMO credit cards in Canada 2026 moneysense.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.