Premium travel credit cards in Canada are financial products designed for frequent travellers who can utilize high-end benefits like airport lounge access, comprehensive travel insurance, and flexible point redemption. These cards typically carry higher annual fees but offer a suite of luxury perks intended to enhance the travel experience. The value of such a card depends heavily on an individual's ability to regularly use its included benefits, which can range from hotel status upgrades to annual travel credits. For Canadians who travel extensively, these cards can provide significant convenience and potential savings on travel costs.
Defining Premium Travel Credit Cards
Premium travel credit cards in the Canadian market are distinguished by their robust set of travel-oriented benefits and higher annual fees, which often range from $399 to $799. These cards are engineered for consumers who travel frequently and seek to enhance their journeys with perks beyond simple point accumulation. The core value proposition extends beyond earning rates to include tangible travel improvements such as lounge access, hotel elite status, and substantial travel insurance packages. Cardholders typically gain access to a network of over 1,400 airport lounges worldwide, which is a standard feature among the most premium offerings. The insurance coverage provided with these cards is comprehensive, frequently including up to $2 million in emergency medical insurance alongside trip cancellation, interruption, flight delay, and baggage coverage.
The financial structure of these cards involves an annual fee that is offset by a combination of travel credits, insurance value, and the utility of the included perks. For example, some cards provide an annual travel and dining credit, such as $400, which effectively reduces the net cost of the card for users who would spend that amount regardless. The points earned are often flexible and transferable, allowing conversion to major airline loyalty programs like Aeroplan at a 1:1 ratio, which provides significant redemption flexibility. It is crucial for potential applicants to assess their typical travel patterns and spending habits to determine if the high annual fee is justified by their personal usage of the card's features. The decision hinges on a cost-benefit analysis where the card's benefits are weighed against its upfront cost.
Common Features and Benefits
Premium travel credit cards share several defining features that provide value to cardholders. Unlimited or complimentary airport lounge access is a primary benefit, offering a space to work or relax before flights, with some cards providing a set number of complimentary visits per year, such as six. Comprehensive travel insurance is another critical component, with coverage areas that routinely include emergency medical expenses, trip cancellation and interruption, flight delays, lost or delayed baggage, and even rental car collision damage waiver insurance. Many of these cards also offer the advantage of no foreign transaction fees, saving cardholders the standard 2.5% charge on purchases made in foreign currencies, which is a substantial benefit for international travellers.
Additional premium perks often include automatic elite status with major hotel loyalty programs such as Marriott Bonvoy and Hilton Honors, which can lead to room upgrades, late check-out, and bonus points. Some cards provide an annual travel credit, which is a statement credit applied against eligible travel or dining purchases, effectively reducing the card's effective annual fee. Cardholders also benefit from increased point earning rates on specific spending categories, particularly on travel bookings made through the card's designated travel portal or on everyday categories like groceries and dining. The combination of these features aims to deliver a superior travel experience, from the planning stage with boosted point earnings to the journey itself with lounge access and insurance protection.
Eligibility and Application Considerations
Eligibility for premium travel credit cards in Canada is generally based on an individual's creditworthiness and personal income, which issuers use to assess the ability to manage a high-limit credit product. Applicants typically need a strong credit history and a higher personal income to qualify for cards with annual fees of $399 or more. The application process is conducted online through the financial institution's website, where prospective cardholders must provide personal and financial details for a credit assessment. Approval decisions are often provided quickly, sometimes within minutes of application submission, assuming all necessary information is supplied.
It is important for applicants to review the specific terms and conditions of the card, including interest rates on purchases and cash advances, which can be as high as 21.99% for some products. Understanding the card's fee structure beyond the annual fee is also crucial, as some premium cards are charge cards that require the balance to be paid in full each month to avoid penalties. Potential cardholders should verify that their typical spending aligns with the card's reward structure to maximize point accumulation. Finally, applicants must ensure they meet the residency requirements, as some offers are not available to residents of Quebec, who may be eligible for separate, provincially compliant offers.
Key Cards in the Canadian Market
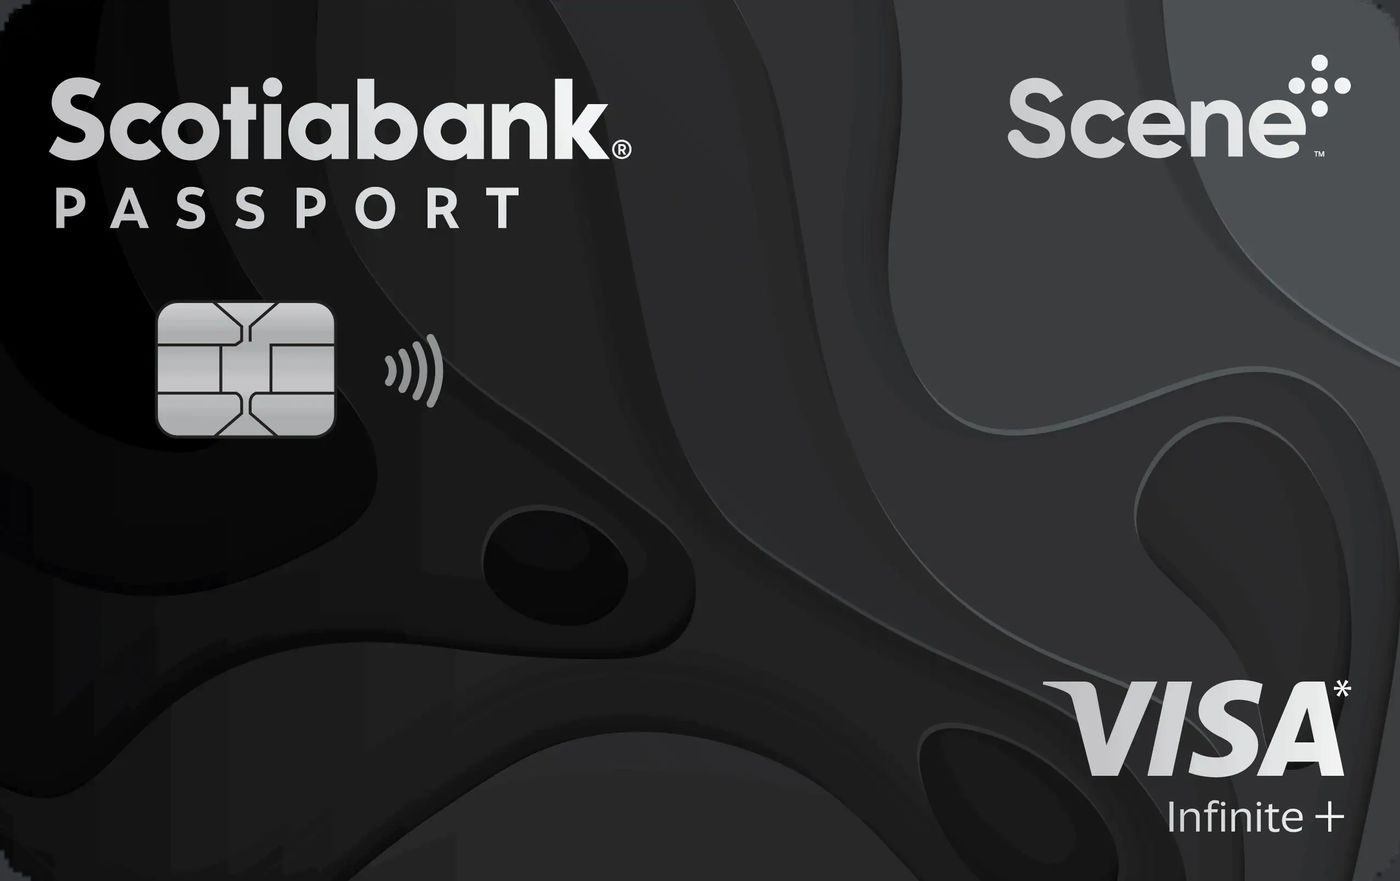
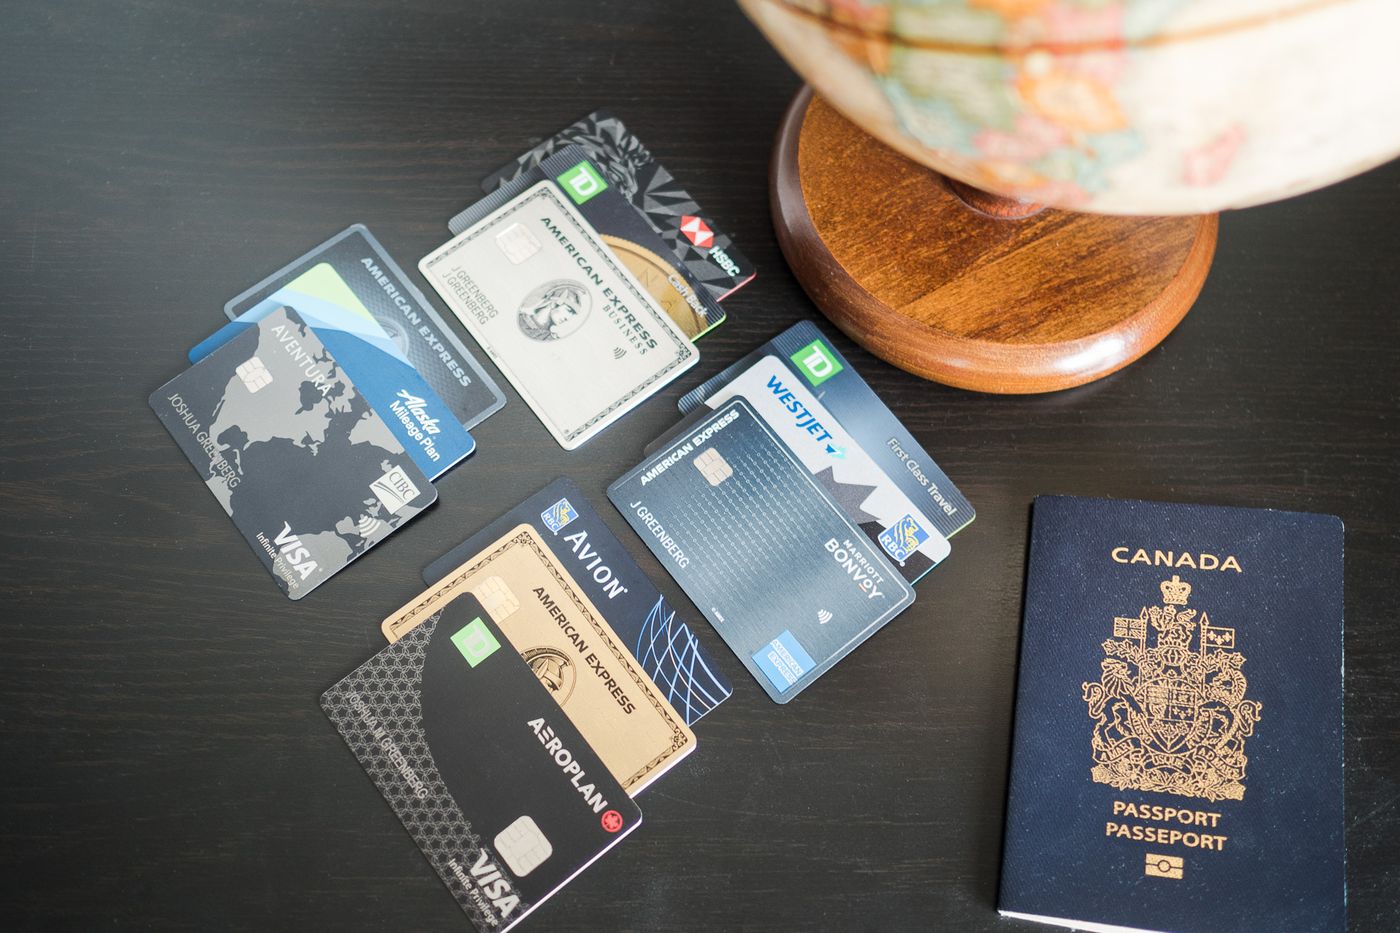
The Canadian premium travel credit card landscape includes several prominent options from major issuers, each with a distinct mix of fees, benefits, and reward structures. The American Express Platinum Card is positioned as a top-tier option with a $799 annual fee, offering unlimited airport lounge access, hotel status, $400 in annual travel and dining credits, and transferable Membership Rewards points. The Scotiabank Passport Visa Infinite+ card features a lower annual fee and provides six complimentary airport lounge visits per year, no foreign transaction fees, and up to $2 million in emergency medical insurance. The RBC Avion Visa Infinite Privilege card is another premium offering that includes travel insurance, lounge access, and the ability to convert Avion points to various airline loyalty programs.
The Scotiabank Gold American Express Card is one of the best overall travel credit cards in Canada. It offers high Scene+ earn rates and has no foreign transaction fees. You can earn up to 6 Scene+ points per dollar spent and 5 points per dollar on eligible groceries, dining, food delivery and entertainment. The card also includes extensive travel insurance coverage.
The American Express Cobalt Card is one of the best travel credit cards in Canada for earning flexible travel points. It offers a high earn rate on everyday spending, with 5 Membership Rewards points per dollar on eligible groceries, restaurants, and food delivery in Canada. These points can be transferred to Aeroplan and other airline loyalty programs. The card also provides strong travel insurance and a generous welcome offer.
The TD Aeroplan Visa Infinite Privilege card is tailored for Aeroplan collectors. It offers enhanced earn rates on Air Canada purchases and provides Aeroplan benefits. This card is designed for travellers who are loyal to the Air Canada Aeroplan program. It is part of the category of cards that are strongest for travellers who want travel points they can use for different kinds of trips. Each of these cards serves a different traveller profile. The right card depends on whether you seek maximum luxury, flexible point earnings on everyday spending, or loyalty to a specific airline program. Travel credit cards offer different kinds of value, from earning points and airline perks to lounge access and insurance.
Comparing Costs and Potential Value
The annual fees for premium travel credit cards represent a significant upfront cost, and understanding the potential return is essential. Cards like the American Express Platinum have a $799 fee but counterbalance it with $400 in annual credits and a suite of high-use perks. The Scotiabank Platinum American Express card carries a $399 annual fee and offers a flat earn rate of 2 Scene+ points per dollar spent. To assess value, cardholders must calculate whether the benefits they will actually use, such as lounge visits, insurance coverage, and point redemptions, exceed the card's cost. For infrequent travellers, the math may not favour a premium card, but for those who travel several times a year, the benefits can easily surpass the annual fee.
Beyond the annual fee, other costs to consider include interest charges on carried balances and potential foreign transaction fees, though many premium cards waive the latter. The value of points earned also varies. For instance, Membership Rewards points that transfer to Aeroplan can be worth more than fixed-value points depending on redemption strategy. Some cards offer first-year annual fee rebates as part of welcome bonuses, which can enhance initial value. Ultimately, the net value is highly personal and depends on individual travel frequency, spending patterns, and how actively one engages with the card's entire ecosystem of benefits.
Steps for Choosing a Premium Travel Card
Selecting the most suitable premium travel credit card involves a methodical evaluation of personal needs against card features. The first step is to identify your primary travel goals, such as accumulating points for specific airlines, accessing lounges, or obtaining robust travel insurance. Next, analyze your monthly spending habits to see which card's bonus categories align with where you spend the most money, such as groceries, dining, or direct travel purchases. The third step is to review the card's full benefit package, including insurance details, lounge access policies, and any companion benefits, to ensure they match your travel style. Finally, perform a cost-benefit analysis by estimating the monetary value you would derive from the card's perks and credits over a year and comparing it to the annual fee.
- Identify your main travel objectives and desired card benefits.
- Analyze your monthly spending to match card bonus categories.
- Review the complete benefit package, including insurance and lounge access.
- Estimate the annual value of perks and credits you will use.
- Compare the estimated value against the card's annual fee.
- Check eligibility requirements, including income and credit score.
- Apply online through the issuer's official website.
After narrowing down choices, applicants should verify their eligibility by checking the issuer's stated income and credit score requirements. The application itself is completed online, requiring personal, financial, and employment information. Once approved, cardholders should actively use the card's benefits, such as enrolling in lounge programs and using travel credits, to realize the card's full value. Regularly reviewing your card's fit with your lifestyle is also recommended, as travel habits and financial situations can change over time.
Common Mistakes to Avoid
One common mistake is applying for a premium card primarily for its welcome bonus without a plan to use its ongoing benefits, which can lead to paying a high annual fee for limited value. Another error is underestimating the importance of the card's insurance exclusions and limitations, assuming coverage is all-encompassing when it often has specific conditions and maximums. Cardholders sometimes neglect to activate or use the card's annual credits or companion passes, leaving tangible value on the table. Focusing solely on the point earn rate while ignoring other card features, such as foreign transaction fees or lack of lounge access, can also be a misstep, especially for international travellers.
Failing to pay the balance in full on charge card products like the American Express Platinum can result in steep interest charges and penalties, negating any rewards earned. Overlooking the requirement to book travel through a specific portal to earn bonus points or to use insurance benefits is another frequent oversight. Finally, not comparing the redemption value of points across different programs can lead to suboptimal use of accumulated rewards. Avoiding these pitfalls requires careful reading of the cardholder agreement, proactive management of card benefits, and a clear understanding of how the card integrates with one's travel and spending patterns.
Frequently asked questions
What is the best premium travel credit card in Canada?
The American Express Platinum Card is considered the best premium travel credit card in Canada for frequent travellers who can make regular use of high-end travel benefits. It offers unlimited airport lounge access, hotel status, and annual travel credits. The Scotiabank Passport Visa Infinite+ Card is noted as the best travel credit card in Canada with no foreign transaction fees. The right card ultimately depends on your individual travel habits and which benefits you will actually use.
Are premium travel credit cards worth the high annual fee?
A premium travel card can be worth its annual fee if you regularly use the benefits it provides. Value comes from actively using features like airport lounge access, annual travel credits, comprehensive travel insurance, and high point earn rates on your spending. For infrequent travellers who would not use these perks, the fee may not be justified. A personal cost-benefit analysis is necessary to determine if the card's value exceeds its cost.
Do premium travel cards offer travel insurance?
Yes, premium travel credit cards in Canada typically include extensive travel insurance packages. For example, the Scotiabank Passport Visa Infinite+ Card offers up to $2 million in emergency medical insurance. Common coverage includes trip cancellation, interruption, flight delay, and baggage insurance. It is essential to read the cardholder agreement for specific terms and conditions as coverage varies by card.
Can I get airport lounge access with these cards?
Most premium travel credit cards offer some form of airport lounge access. The American Express Platinum Card provides unlimited access to more than 1,400 airport lounges. The Scotiabank Passport Visa Infinite+ Card includes six complimentary airport lounge visits each year. Access is typically provided through a membership in a program like Priority Pass or directly through the card issuer's network.
How do I redeem points from premium travel cards?
Points from premium travel cards can be redeemed for travel expenses like flights and hotels through the card's travel booking portal. Many cards allow you to transfer points to partner airline loyalty programs, such as Aeroplan, at a 1:1 ratio. For example, American Express Membership Rewards points can be transferred to Aeroplan. Some cards also offer fixed-value redemptions where points equal a dollar value off travel purchases.
What are the eligibility requirements for a premium travel card?
Eligibility for premium travel cards generally requires a strong credit history and a higher personal income. Applicants must be Canadian residents. The application process involves a credit check. Approval is based on the issuer's assessment of creditworthiness and ability to manage the account. Some offers may not be available in Quebec.
Sources and further reading
- The best travel credit cards in Canada for 2026 ratehub.ca
- Best Travel Credit Cards in Canada nerdwallet.com
- Travel Rewards Credit Cards, Apply Online | RBC ... rbcroyalbank.com
- Credit Card Comparison, Ultra Premium Travel ... rewardscanada.ca
- Travel Rewards Credit Cards in Canada td.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.