Online brokerage platforms in Canada are digital services that enable self-directed investors to buy and sell investments like stocks, ETFs, and mutual funds. These platforms empower Canadians to manage their own portfolios, offering a cost-effective alternative to traditional full-service brokers. The landscape is highly competitive, with numerous firms differentiating themselves through fees, trading tools, research, and investor education. Choosing a suitable platform involves comparing key attributes such as commission structures, account types, available securities, and the quality of the trading platform itself.
Understanding Online Brokerage Platforms
An online brokerage platform is the website or mobile application investors use to place trades, monitor portfolios, and manage their investment accounts. These platforms, offered by discount brokerages, have grown in popularity as they provide investors with direct control over their financial decisions. The core function of these platforms is to facilitate the buying and selling of a wide variety of securities. For new investors, a platform should be intuitive and easy to use, while more advanced traders may require sophisticated tools for research, real-time data, and complex order types. The quality and functionality of the trading platform are central to the investor experience, impacting everything from the ease of executing a trade to the depth of market analysis available.
The Canadian online brokerage market includes both domestic financial institutions and independent or globally-owned firms. Platforms are typically evaluated across several key pillars, including the digital experience, investor resources, customer service, and the overall cost of investing. While many platforms now promote commission-free trading, the differences between them extend far beyond pricing. Investors must consider how well a platform's tools and resources align with their experience level and investment strategy. A robust platform will offer features like watchlists, price alerts, screening tools, and charting capabilities to support informed decision-making. The competitive market means firms continuously improve their digital platforms and investor experiences to attract and retain clients.
Key Factors for Comparing Brokerages
When evaluating online brokerage platforms, investors should systematically compare several critical attributes. The first is the pricing structure, which includes trading commissions, account maintenance fees, inactivity fees, and any minimum balance requirements. Some platforms offer commission-free trading on certain securities like ETFs or stocks, while others use a flat-fee or volume-based commission model. It is essential to align the fee structure with your trading frequency and budget, as fees can significantly impact returns, especially for those making small or frequent trades. Another vital factor is the range of securities offered. Most platforms provide access to Canadian and U.S. stocks, ETFs, and mutual funds, but access to bonds, options, or international markets varies widely.
The types of investment accounts supported are another crucial consideration. Most brokerages offer registered accounts like Tax-Free Savings Accounts (TFSAs), Registered Retirement Savings Plans (RRSPs), First Home Savings Accounts (FHSAs), and Registered Education Savings Plans (RESPs), each with specific contribution limits and tax implications. Non-registered or cash accounts are also available for general investing without contribution limits. Furthermore, the quality and accessibility of investor education and customer support can be decisive, particularly for those new to self-directed investing. Resources range from static articles and videos to interactive modules, webinars, and direct telephone support. The following list outlines the primary categories for comparison.
- Pricing & Fees: Trading commissions, account minimums, and inactivity fees.
- Securities & Markets: Access to stocks, ETFs, mutual funds, bonds, options, and international exchanges.
- Account Types: Availability of registered (TFSA, RRSP, FHSA, RESP) and non-registered accounts.
- Trading Platform: Usability, tools, research, real-time data, and mobile app functionality.
- Investor Education: Guides, articles, videos, webinars, and learning modules.
- Customer Support: Availability of online help centres, FAQs, and telephone support.
Finally, the regulatory environment and investor protections are fundamental. All online brokerages operating in Canada are regulated by the Canadian Investment Regulatory Organization. Client assets are protected up to certain limits by the Canadian Investor Protection Fund, which provides coverage in the event of a member firm's insolvency. This protection is a key safety feature for investors using these platforms.
Commission Structures and Fees
Commission structures are a primary differentiator among online brokerage platforms. Many firms have moved toward commission-free trading models to attract clients, particularly for Canadian and U.S. stocks and ETFs. However, the definition of 'free' can vary. Some platforms offer unlimited commission-free trades, while others provide a limited number of free trades annually before standard commissions apply. It is important to read the terms and conditions to understand any other potential costs. Beyond trading commissions, investors should be aware of account maintenance fees, which some brokerages charge if an account balance falls below a specified minimum. Inactivity fees may also apply if no trades are executed within a certain period.
Foreign exchange fees are another significant cost for investors trading securities in a currency different from their account's base currency. Some platforms charge a percentage-based fee for currency conversion, while others offer more competitive rates or the ability to hold multi-currency accounts to mitigate these costs. For active traders, some brokerages offer tiered pricing, where commission rates decrease as the number of trades per quarter increases. The table below illustrates examples of different fee structures from various platforms, highlighting the importance of matching a pricing model to your trading habits.
| Platform | Stock/ETF Commission (CAD) | Key Fee Notes |
|---|---|---|
| Wealthsimple Trade | $0 | Commission-free on all stocks and ETFs. No account minimums. |
| Questrade | $0 | Commission-free equity trading. Charges may apply for other order types. |
| RBC Direct Investing | $9.95 (Standard) | $6.95 per trade for clients with 150+ trades per quarter. |
| CIBC Investor's Edge | $6.95 | Standard online equity trade commission. |
| Interactive Brokers Canada | CA$1.49 / US$1.99 | Tiered pricing for Canadian and U.S. stocks and ETFs. |
When assessing fees, investors should also consider any costs associated with transferring accounts, withdrawing funds, or accessing premium research and data. A platform with low or zero trading commissions might have higher costs in other areas. For example, some platforms require you to keep a minimum amount in your account and charge you if you fall below that amount. A holistic view of all potential charges is necessary for an accurate comparison. Understanding the complete fee schedule is essential for managing the total cost of investing through any given platform.
Account Types and Tax Considerations
Online brokerage platforms in Canada offer both registered and non-registered investment accounts. Registered accounts provide tax advantages and are designed for specific long-term goals. The most common registered accounts include the Tax-Free Savings Account (TFSA), where investment growth and withdrawals are tax-free. The Registered Retirement Savings Plan (RRSP), where contributions are tax-deductible and growth is tax-deferred. The First Home Savings Account (FHSA), which combines RRSP and TFSA benefits for first-time home buyers. And the Registered Education Savings Plan (RESP) for saving for a child's post-secondary education. Each of these account types has annual contribution limits set by the federal government, and it is the investor's responsibility to ensure they do not exceed their personal limit across all accounts held at any institution.
Non-registered investment accounts, also known as cash or margin accounts, do not have contribution limits and offer more flexibility for short and long-term goals. Investment income within non-registered accounts, such as dividends, interest, and capital gains, is taxable in the year it is earned. Some platforms also offer non-registered U.S. dollar accounts, which allow investors to hold U.S. funds directly, potentially reducing foreign exchange fees on U.S. security trades. When choosing a platform, investors should verify which specific account types are supported. Most major brokerages offer a full suite of registered accounts, but some newer or specialized platforms may have a more limited selection. The choice between registered and non-registered accounts directly affects an investor's tax situation and long-term financial planning.
Securities and Market Access
The range of securities and markets accessible through an online brokerage platform defines an investor's opportunity set. Most platforms provide access to Canadian and U.S. equities (stocks), exchange-traded funds (ETFs), and mutual funds. ETFs are particularly popular among self-directed investors due to their low cost and diversification benefits. Beyond these core securities, availability diverges. Some brokerages offer access to bonds, Guaranteed Investment Certificates (GICs), and options for more advanced strategies. A smaller subset of platforms provides direct access to international markets beyond North America, such as exchanges in Europe, Asia, or emerging markets.
It is crucial to distinguish between platforms that allow for direct investment in securities and those designed for speculative trading using contracts for difference (CFDs) or forex. Direct investment brokerages, which include all major Canadian bank-owned platforms and firms like Questrade and Interactive Brokers Canada, enable investors to own the underlying assets. These are the only platforms that support registered, tax-sheltered accounts. In contrast, CFD and forex platforms are designed for high-leverage trading on price movements without owning the asset. These accounts are strictly non-registered and carry significantly higher risk. Canadian regulations cap leverage for retail clients on these platforms, typically between 1:20 and 1:33 for major forex pairs, to provide investor protection. This distinction is fundamental when selecting a platform aligned with your investment objectives and risk tolerance.
Trading Platforms and Investor Tools
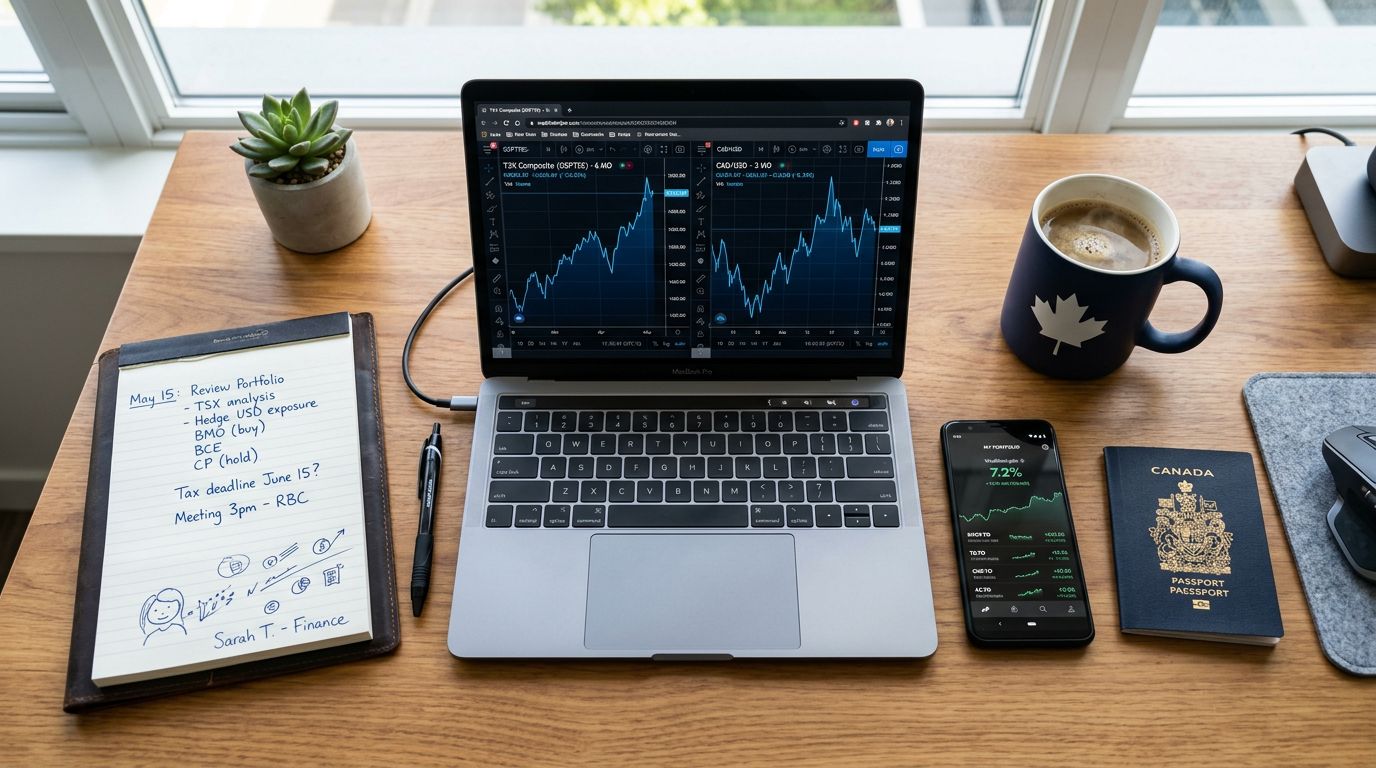
The trading platform is the primary interface through which investors execute their strategy. Platforms vary in complexity, from simple, streamlined apps designed for beginners to powerful desktop software packed with advanced features for active traders. Key tools to evaluate include real-time streaming quotes, advanced charting packages with technical indicators, screening tools to filter securities based on custom criteria, and robust portfolio analytics. Many platforms also offer practice or demo accounts, allowing users to familiarize themselves with the interface and test strategies without risking real capital. Mobile app functionality is increasingly important, providing investors with the ability to monitor markets and trade on the go.
For active traders, some brokerages offer dedicated advanced platforms or programs. For example, TD Direct Investing offers its Active Trader platform, which provides enhanced tools for options trading and access to extended hours trading. RBC Direct Investing has an active trader program with similar advanced features. The availability of quality research is another differentiator. Some platforms integrate third-party research from firms like Morningstar, offering analyst reports, ratings, and market commentary. Educational resources are also a core component, especially for novice investors. These can include investing academies, tutorial videos, articles, and webinars that cover topics from basic concepts to advanced trading techniques. The strength of these tools and resources can significantly influence an investor's ability to make informed decisions and manage their portfolio effectively.
Regulation and Investor Protection
All online brokerage platforms operating in Canada are subject to regulation by the Canadian Investment Regulatory Organization (CIRO), which oversees investment dealers and trading activity. This regulatory framework ensures that firms adhere to rules regarding client account handling, trade execution, and financial reporting. A critical aspect of investor protection is the Canadian Investor Protection Fund (CIPF), which safeguards client assets held by CIRO member firms in the event of a firm's insolvency. The CIPF provides protection up to $1 million for general accounts, which include cash, margin, TFSA, and FHSA accounts. Separate coverage of up to $1 million is provided for registered retirement accounts (like RRSPs and RRIFs), and another $1 million for Registered Education Savings Plans (RESPs).
It is important for investors to confirm that their chosen platform is a member of CIPF. While the CIPF protects against the loss of securities and cash due to a member firm's failure, it does not protect against market losses from investment decisions. For platforms that offer trading in contracts for difference (CFDs) or forex, different regulatory standards and investor protections may apply, and leverage is strictly capped for retail clients under Canadian rules. Investors should always review the regulatory disclosures and terms of service provided by a brokerage to fully understand the protections in place for their accounts and assets. This due diligence is a fundamental step in selecting a secure and trustworthy online brokerage platform.
Frequently asked questions
What is the difference between an online brokerage and a robo-advisor?
An online brokerage provides a platform for self directed investors to choose and trade their own investments, such as stocks and ETFs. A robo advisor is a digital service that creates and manages a diversified portfolio for you based on your risk tolerance and goals, typically using ETFs, for a management fee. Online brokerages require you to make all investment decisions, while robo advisors handle the investing on your behalf. Online brokers are ideal for investors who want to select or build their own portfolio.
What does commission-free trading actually mean?
Commission free trading means you pay no commission fees to buy or sell stocks or other investment products like ETFs. However, there may be other costs such as account fees that are charged if you do not keep a minimum balance. There can also be foreign exchange fees if you buy foreign stocks using the platform. It is important to read the terms and conditions to understand what else you might be paying for.
How do I transfer an existing investment account to a new brokerage?
To transfer an account, you typically open a new account at the desired brokerage and initiate a transfer request through their platform. The new brokerage will coordinate with your old institution to transfer the assets. Many brokerages offer to cover transfer fees charged by the outgoing firm up to a certain amount. This is often provided a minimum transfer value is met.
What should a beginner look for in an online brokerage platform?
Beginners should prioritize platforms with intuitive, user friendly interfaces and strong educational resources. These resources can include videos, articles, webinars, and interactive learning modules. Responsive customer support is also critical, ranging from online FAQs to telephone support. Low or zero account minimums and commission free trading on basic securities like ETFs can reduce barriers to starting.
Are online brokerage platforms safe and regulated in Canada?
Yes, online brokerage platforms in Canada are safe and regulated. They are regulated by the Canadian Investment Regulatory Organization. Furthermore, the Canadian Investor Protection Fund provides protection for investors' assets in the event of broker insolvency. This coverage extends up to one million dollars for general accounts, which include cash, margin, TFSA, and FHSA accounts. An additional one million dollars of coverage is provided for registered retirement accounts. RESPs are also covered for up to one million dollars. This regulatory framework ensures a secure environment for self directed investors using these platforms.
Can I hold U.S. stocks in my Canadian TFSA through an online broker?
Yes, you can hold U.S. stocks in your Canadian TFSA through an online broker. Most Canadian online brokerage platforms permit the holding of U.S. listed stocks and ETFs within a Tax Free Savings Account. It is important to understand the tax implications, however. While capital gains and dividends earned within the TFSA are tax free in Canada, U.S. dividends are subject to a non resident withholding tax. This tax is typically withheld at source by the U.S. Internal Revenue Service before the dividend payment reaches your account.
Sources and further reading
- Best Online Trading Platform in Canada td.com
- Best online brokers in Canada for 2026 moneysense.ca
- The best online brokerages in Canada 2026 ratehub.ca
- Online Investing and Trading Platform in Canada rbcdirectinvesting.com
- Comparing Best Trading Platforms in Canada wowa.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.