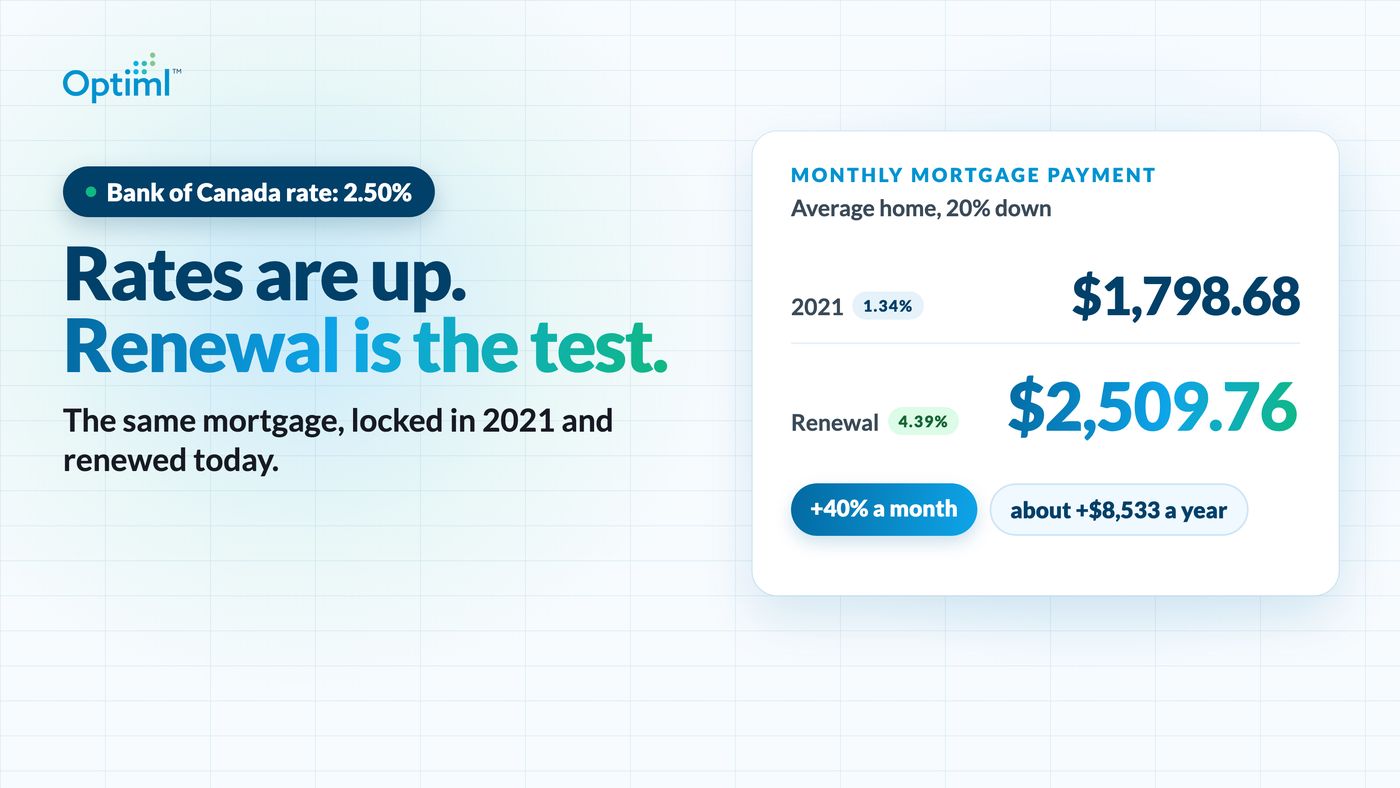
The Bank of Canada raised its policy rate on Oct. 28 for the first time since 2023, nudging it up a quarter point to 2.5 percent.
The move has translated into higher returns for savers, with the best standard savings account rate now at 3.25 percent, up from 3 percent six weeks ago.
Over the same stretch, the top one-year guaranteed investment certificate rate climbed to 4.05 percent from 3.80 percent.
Longer terms moved less, with the best five-year GIC paying 4.55 percent, up from 4.45, and the three-year inching up to 4.40 percent from 4.35.
Smaller financial institutions did most of the running, with WealthONE now topping every category except promotional savings rates, where Simplii’s 5 percent five-month offer still leads, and Oaken Financial is close behind on three- and five-year GICs.
The shift comes as the central bank acts on inflation risks, with firms in its latest Business Outlook Survey saying they plan to pass more of their higher costs on to customers.
Households told the bank’s consumer survey they expect faster inflation.
“Neither group was predicting the future so much as announcing it,” the analysis said. “That risk, more than the price of gasoline, is what pushed the bank to act.”
Two developments have since softened the case for more hikes.
Early Statistics Canada data put third-quarter growth at roughly 1.3 percent annualized, well short of the 2 percent the bank had projected only days earlier.
Then on Tuesday, Democrats swept the U.S. midterms, taking both chambers of Congress.
U.S. President Donald Trump will likely try to govern through vetoes and executive orders, but a hostile Congress should limit his inflationary agenda for his last two years in office.
By Tuesday, before anyone knew how the U.S. vote had gone, a December rate hike looked like a coin toss and the expected path had flattened, with 3.5 percent pushed out to 2028.
The election may cool those bets further.
“Still, a slower climb is not a retreat,” the analysis said. “Until Iran is resolved, the risk that energy costs seep into wages and prices remains, and the bank has made clear it won’t sit and wait to find out.”
The shape of GIC rates tells you what lenders expect.
Six weeks ago, the best five-year GIC paid 65 basis points more than the best one-year. Today the gap is 50.
Shorter-term rates have risen faster, narrowing the extra annual return available for a five-year commitment.
That leaves savers guessing what central bankers will do next.
If hikes continue, a one- or two-year GIC lets you reinvest at higher rates before long.
If you’d rather guard against a peace deal pulling rates down, a five-year GIC locks in 4.55 percent, though the bonus for tying up your money that long is now slim.
Cash you may need soon belongs in a savings account.
The best standard rate sits 0.8 percentage points below the top one-year GIC, and could rise if the Bank of Canada hikes again.
For savers who also have a mortgage, the numbers raise another question: whether to save or pay down debt.
The top three-year GIC pays 4.40 percent, slightly above the lowest three-year fixed mortgage rate of 4.29 percent. The lowest five-year variable mortgage rate is 3.60 percent.
But advertised rates are only a starting point: Compare your own mortgage rate, account for any tax on the interest and check your mortgage’s prepayment limits.
Interest rates are provided by WOWA.ca, which gathers, aggregates and freely disseminates data on mortgage rates, savings accounts, and GIC rates from 50-plus Canadian financial institutions.
This story was written by the e2gold.ca newsroom from reporting by The Globe and Mail and Rich Picks Daily. Quotes are checked word for word against that reporting.