Third party liability car insurance is a mandatory coverage in Canada that protects you financially if you are found responsible for injuring another person or damaging their property while driving. It covers costs such as medical bills, property repairs, and legal fees for the affected third party. Every province and territory sets its own minimum required coverage limit, which drivers must purchase to legally operate a vehicle. Understanding this coverage is essential for all Canadian drivers, as being underinsured can leave you personally liable for catastrophic costs following an at-fault accident.
What Third Party Liability Insurance Is and How It Works
Third party liability insurance is a fundamental component of auto insurance designed to provide financial protection if you are legally responsible for causing harm to others while operating your vehicle. The structure of the policy involves three parties: you are the first party, your insurance company is the second party, and anyone else you might injure or whose property you might damage is the third party. This coverage is not optional anywhere in Canada, as it is a legal prerequisite for registering and driving a vehicle on public roads. The core purpose is to ensure that victims of at-fault accidents can be compensated without bankrupting the responsible driver, which upholds a key principle of financial responsibility within the transportation system. When you cause an accident, your insurer will handle claims from affected third parties up to the dollar limit specified in your policy, protecting your personal assets from being seized to pay for damages.
The coverage activates in situations where you are deemed at fault for a collision or incident. It responds to claims made against you by other drivers, passengers, pedestrians, cyclists, or property owners. For example, if you fail to stop at a red light and collide with another vehicle, the other driver's injuries and vehicle damage would be covered by your third party liability insurance. The insurance company will investigate the claim, manage the settlement process, and provide legal defence if you are sued. It is crucial to understand that this coverage is for the benefit of others you harm, not for your own injuries or vehicle repairs, which are addressed by other parts of your auto insurance policy like accident benefits and collision coverage.
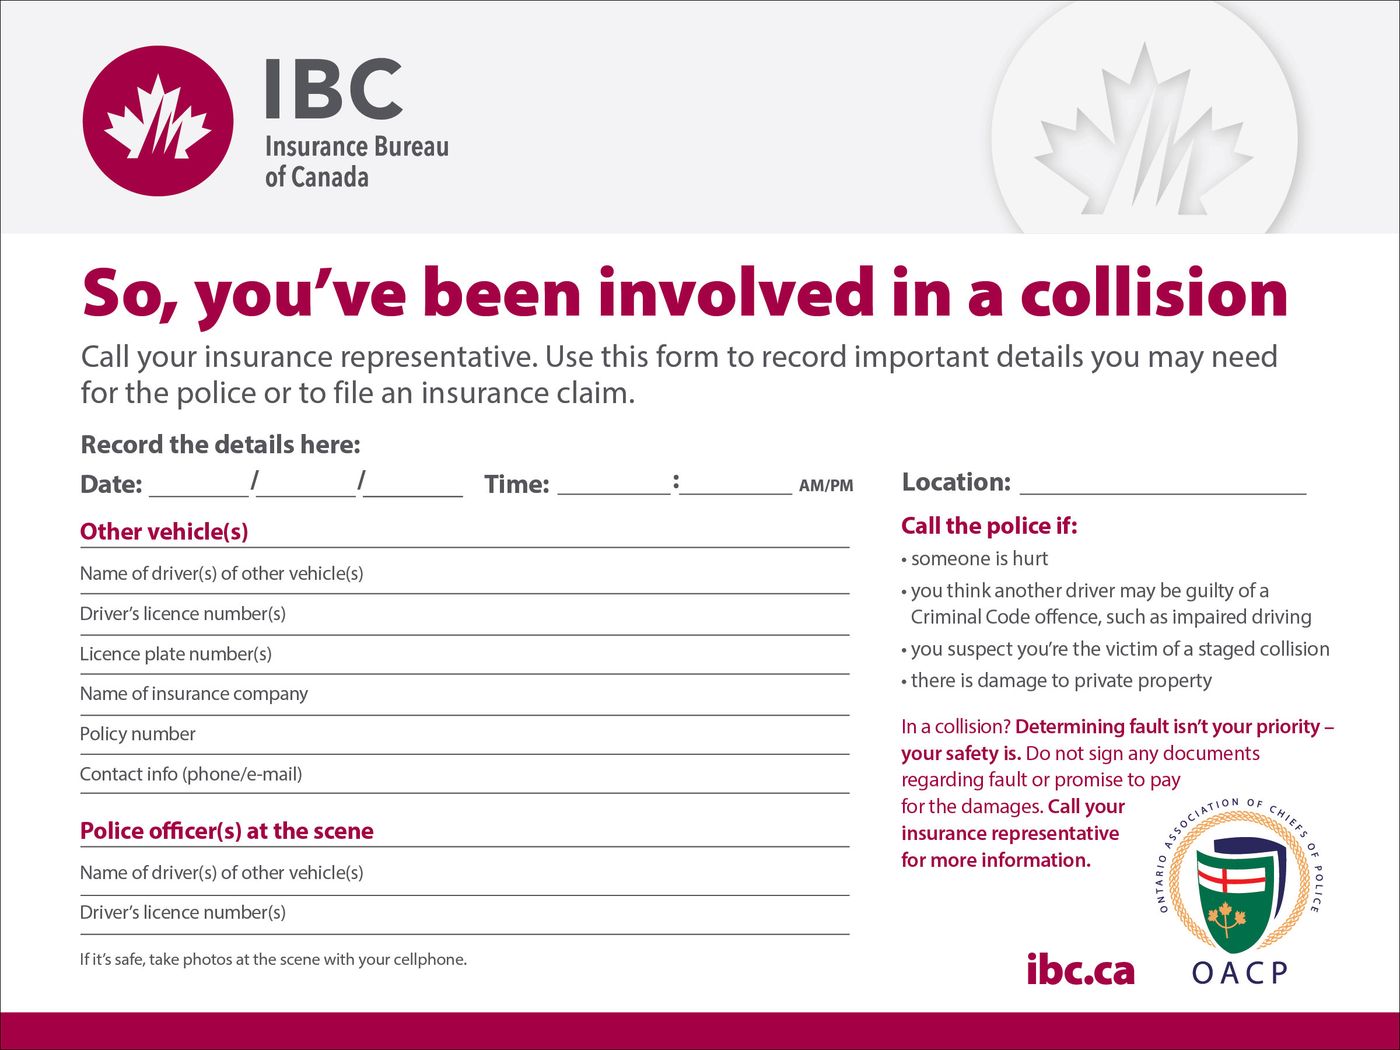
What Third Party Liability Insurance Covers
Third party liability insurance provides coverage for two primary categories of loss: bodily injury to other people and damage to property belonging to others. Bodily injury coverage handles the costs associated with injuries you cause to another person in an accident. This includes immediate medical expenses like ambulance fees, emergency room treatment, surgery, and hospital stays. It also extends to long-term care needs such as physiotherapy, rehabilitation, and home care required for recovery. Furthermore, this coverage can compensate for lost income if the injured person is unable to work, and for non-economic damages like pain and suffering awarded in a lawsuit. In tragic cases involving fatal accidents, it may also cover funeral expenses and provide death benefits to the family of the deceased.
Property damage coverage pays for the repair or replacement of physical property that you damage with your vehicle. This most commonly applies to other vehicles, but it also includes stationary objects like buildings, fences, mailboxes, and public infrastructure such as guardrails, traffic lights, and utility poles. For instance, if you skid on an icy road and crash into a storefront, your liability insurance would cover the cost to repair the building. A significant and often overlooked component of this coverage is the provision for legal defence. If you are sued as a result of an accident, your insurer will appoint and pay for a lawyer to defend you in court. The policy will also pay for any court-ordered judgment or out-of-court settlement, up to your policy's limit, which protects your savings, investments, and future earnings from being garnished.
Mandatory Minimum Coverage Limits by Province
The minimum amount of third party liability insurance you must carry is not uniform across Canada. Each province and territory establishes its own legal requirement. These minimums represent the absolute least coverage you can legally purchase, but they may not be sufficient to protect you in a serious accident. It is vital for drivers to know the limit in their jurisdiction and seriously consider purchasing coverage well above the mandatory minimum. The financial consequences of a severe accident can easily exceed these base amounts, potentially leaving you responsible for paying the difference out of your own pocket, which could lead to personal bankruptcy or the loss of assets like your home or savings. The following table outlines the mandatory minimum third party liability insurance limits across Canada. These figures are set by provincial regulation and are a core requirement for vehicle registration.
| Province/Territory | Mandatory Minimum Coverage |
|---|---|
| Ontario | $200,000 |
| Alberta | $200,000 |
| British Columbia | $200,000 |
| New Brunswick | $200,000 |
| Newfoundland and Labrador | $200,000 |
| Prince Edward Island | $200,000 |
| Saskatchewan | $200,000 |
| Yukon | $200,000 |
| Northwest Territories | $200,000 |
| Nunavut | $200,000 |
| Nova Scotia | $500,000 |
| Manitoba | $500,000 |
| Quebec | $50,000 |
As the table shows, a $200,000 minimum is the standard in a majority of jurisdictions. Nova Scotia and Manitoba require a significantly higher minimum of $500,000. Quebec operates under a different system with a lower base requirement of $50,000 for damage to property other than vehicles, while bodily injury is covered through a public insurance plan. Drivers should consult their insurance provider or the Insurance Bureau of Canada for the most current regulations, as these limits can be subject to change.
Why Experts Recommend Coverage Above the Minimum
While purchasing only the mandatory minimum limit satisfies the law, most insurance experts strongly advise carrying substantially higher third party liability coverage. A common recommendation from insurers is to maintain a limit of at least $1 million. The rationale for this advice is rooted in the potentially astronomical costs associated with serious accidents. Medical care for catastrophic injuries, such as spinal cord or brain injuries, can span decades and cost millions of dollars. Legal judgments in severe bodily injury lawsuits regularly reach seven-figure amounts when accounting for lifelong care, lost earning capacity, and pain and suffering. The mandatory minimums, particularly $200,000, can be exhausted very quickly, leaving you personally liable for any amount over your policy limit. Increasing your liability limit is a critical step in asset protection. If a claim exceeds your coverage, the injured party can pursue your personal assets, including your house, savings, investments, and even a portion of your future income through wage garnishment. Higher coverage acts as a more robust financial shield. Furthermore, if you frequently drive in the United States, where lawsuit awards and medical costs are notoriously high, carrying a multi-million dollar liability limit is especially prudent. Importantly, increasing your limit from $200,000 to $1 or $2 million often results in a relatively modest increase in your insurance premium, providing a significant amount of extra protection for a reasonable additional cost. You should discuss your specific financial situation and risk exposure with your insurance advisor to determine an appropriate coverage level.
What Third Party Liability Insurance Does Not Cover
It is equally important to understand the limitations and exclusions of third party liability insurance. This coverage is specifically designed for the losses of others, not for your own. It will not pay for repairs to your own vehicle following an accident where you are at fault. To cover damage to your own car, you need to purchase optional collision coverage, which is often required if you lease or finance your vehicle. Similarly, it does not cover your own medical expenses if you are injured. Your personal medical bills, rehabilitation costs, and income replacement are covered under a separate mandatory part of your policy known as accident benefits. Third party liability insurance also typically excludes damage or injury that occurs while you are using your vehicle for commercial purposes unless you have a specific commercial auto insurance policy. This includes activities like ride-sharing for Uber or Lyft, delivering food, or using your personal vehicle for courier work. Using your vehicle for racing or in a speed test is another common exclusion. Intentional acts where you deliberately cause damage or injury are never covered by insurance. Finally, the coverage is subject to the specific limit you purchased. Any claim amount that exceeds that limit becomes your personal financial responsibility, which underscores why carrying adequate limits is so crucial.
Steps to Acquire and Manage Your Coverage
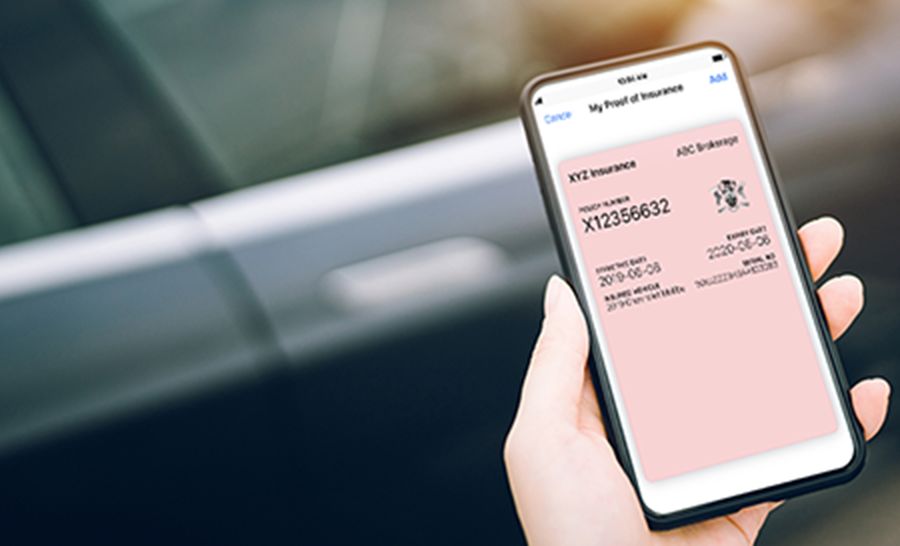
Obtaining third party liability insurance is an integral part of buying any auto insurance policy in Canada. Since it is mandatory, no insurer will issue a policy without it. The process begins when you contact an insurance company or broker to get a quote for insuring your vehicle. You will provide details about yourself, your driving history, and the vehicle to be insured. The insurer will then present you with a quote that includes the mandatory third party liability coverage at a certain limit, often starting at the provincial minimum. At this point, you must decide what coverage limit to purchase. You should carefully evaluate your personal assets, potential risks, and the expert recommendation for higher limits before accepting the minimum. Once your policy is active, you can review and adjust your liability limit at any time, typically at renewal or by contacting your insurer mid-term. If you wish to increase your coverage from $200,000 to $1 million, you would request this change from your provider, who will recalculate your premium. It is a responsible practice to periodically review your liability limits, especially after major life events like buying a home, receiving an inheritance, or a significant increase in income, as these assets need protection. Always ensure your insurance company has your current address and vehicle information on file, and keep proof of insurance in your vehicle at all times as required by law. Driving without valid insurance is a serious offence that can result in heavy fines, vehicle impoundment, and difficulty obtaining affordable insurance in the future.
Common Mistakes and Key Considerations for Canadian Drivers
One of the most frequent and severe mistakes drivers make is purchasing only the mandatory minimum liability limit without considering their personal financial exposure. Treating the minimum as a recommendation rather than a bare legal floor can be a costly error. Another common oversight is failing to inform your insurer if you start using your vehicle for commercial purposes, which could void your coverage when you need it most. Some drivers also mistakenly believe their liability insurance will cover their own injuries or vehicle repairs, leading to confusion and frustration after an accident. It is essential to read your policy documents to understand the distinctions between liability, accident benefits, and physical damage coverages. Drivers should also be aware of the implications of lending their vehicle. In most cases, your third party liability insurance follows the car, meaning if someone you permit to drive your vehicle causes an accident, your insurance policy will respond. This claim would go on your insurance record and could affect your future premiums. Furthermore, if you cause an accident in another province or in the United States, your Canadian liability insurance still provides coverage, but the limits may be inadequate for the higher costs in those jurisdictions, another reason to opt for higher limits. Finally, always report accidents to your insurer promptly, even for minor incidents where you may not intend to make a claim, as the other party could later pursue you for damages, and delayed reporting can complicate your defence.
Frequently asked questions
Is third party liability insurance mandatory in Canada?
Yes, third party liability insurance is mandatory for all drivers in every province and territory in Canada. It is a legal requirement to operate a vehicle on public roads. The minimum required coverage amount is set by each provincial or territorial government, and these mandatory limits vary across the country. For example, most provinces require a minimum of $200,000, while Nova Scotia and Manitoba require $500,000, and Quebec requires $50,000. Driving without this mandatory coverage is a serious offence and can result in high risk driver status, higher premiums, or refusal of insurance.
What is the difference between third party liability and collision insurance?
Third party liability insurance covers damages and injuries you cause to other people and their property. Collision insurance is an optional coverage that pays for damage to your own vehicle from an accident, regardless of fault. The key difference is that liability protects you from claims made by others, while collision protects your own vehicle. Third party liability is mandatory across Canada, whereas collision coverage is optional but often required if you lease or finance your vehicle. Liability coverage handles costs for others, such as medical bills and vehicle repairs, while collision handles the repair costs for your own car after a crash.
Can I increase my third party liability coverage above the minimum?
Yes, you can increase your third party liability coverage above the minimum required limits. It is generally recommended to carry a limit of at least $1 million or even $2 million to protect your personal assets from costly lawsuits. You can adjust your coverage amount when purchasing a policy or at renewal by consulting with your insurance provider. Higher limits provide greater financial security, as you would be personally responsible for any claim costs that exceed your policy limit. This is especially important when driving in the United States where lawsuits are more common and potentially more expensive.
Does third party liability insurance cover my own injuries?
No, third party liability insurance does not cover injuries to you, the policyholder, or your family members. Your own medical expenses are covered under a separate mandatory part of your auto insurance policy called accident benefits. Third party liability is specifically designed to cover bodily injury and property damage you cause to other people. It also covers associated legal fees if you are sued. For your personal protection after an accident, you must rely on your accident benefits coverage, not your liability coverage.
What happens if the cost of an accident exceeds my liability limit?
If the total cost of an at fault accident exceeds your third party liability policy limit, you are personally responsible for paying the remaining balance out of pocket. This could require you to use your savings, sell personal assets like your home, or have future wages garnished. Such financial exposure underscores why carrying liability limits higher than the provincial minimum is strongly advised. Without adequate coverage, a single serious accident could lead to significant personal debt or even bankruptcy, as you would be liable for all costs beyond your insurance limit.
What does third party liability insurance typically cover?
Third party liability insurance typically covers bodily injury costs for others, such as their medical expenses, rehabilitation, and lost income. It also covers property damage costs, including repairs to another person's vehicle, home, fence, or public infrastructure like guardrails. Furthermore, it covers your legal defence fees and any court ordered settlements or judgments if you are sued. This coverage applies when you, or anyone driving your car with permission, are found legally responsible for causing harm or damage to another party. It is a fundamental protection against the financial consequences of at fault accidents.
Sources and further reading
- Third-Party Liability Car Insurance: Coverage & Protection belairdirect.com
- What is Third Party Liability Insurance? tdinsurance.com
- What is Third-Party Liability Insurance for Drivers? rbcinsurance.com
- Types of Auto Coverage ibc.ca
- Third-Party Liability Car Insurance in Canada ratehub.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.