Getting a home insurance quote in Canada involves comparing coverage and premiums from multiple providers to find a policy that fits your needs and budget. While home insurance is not required by law, most mortgage lenders mandate it, and it provides essential financial protection for your property and belongings. The average annual cost is approximately $1,300, but premiums are rising due to factors like inflation and severe weather. Comparing quotes online is a practical way for Canadian homeowners to potentially save hundreds of dollars each year.
How Home Insurance Premiums Are Calculated
Insurers calculate your home insurance premium by assessing the level of risk associated with you and your property. Your home's location provides critical information, indicating risks for flooding, fire, break-ins, or vandalism. Factors like the distance to the nearest fire station are also considered. The age of your home is another key factor, as newer homes generally attract lower premiums due to a lower risk of issues like broken pipes or electrical faults. Policy-specific details you choose, such as your deductible amount, the type of coverage selected, and any optional add-ons, directly influence your final quote. Insurers also evaluate your claims history, and maintaining a claim-free record can lead to discounts. Other elements like your home's construction type and heating systems are factored into the personalized quote calculation to determine your annual premium.
The specific perils, or events, your policy covers also affect the premium calculation. Common covered perils include fire, wind, hail, and theft, while risks like flood, earthquake, wear and tear, and cyber incidents are typically excluded or require separate endorsements. Insurers use all this data to estimate the likelihood and potential cost of a claim, which forms the basis of your personalized premium. The final cost is a balance between the insurer's risk assessment and the coverage limits and deductibles you select when building your policy.
Core Components of a Standard Home Insurance Policy
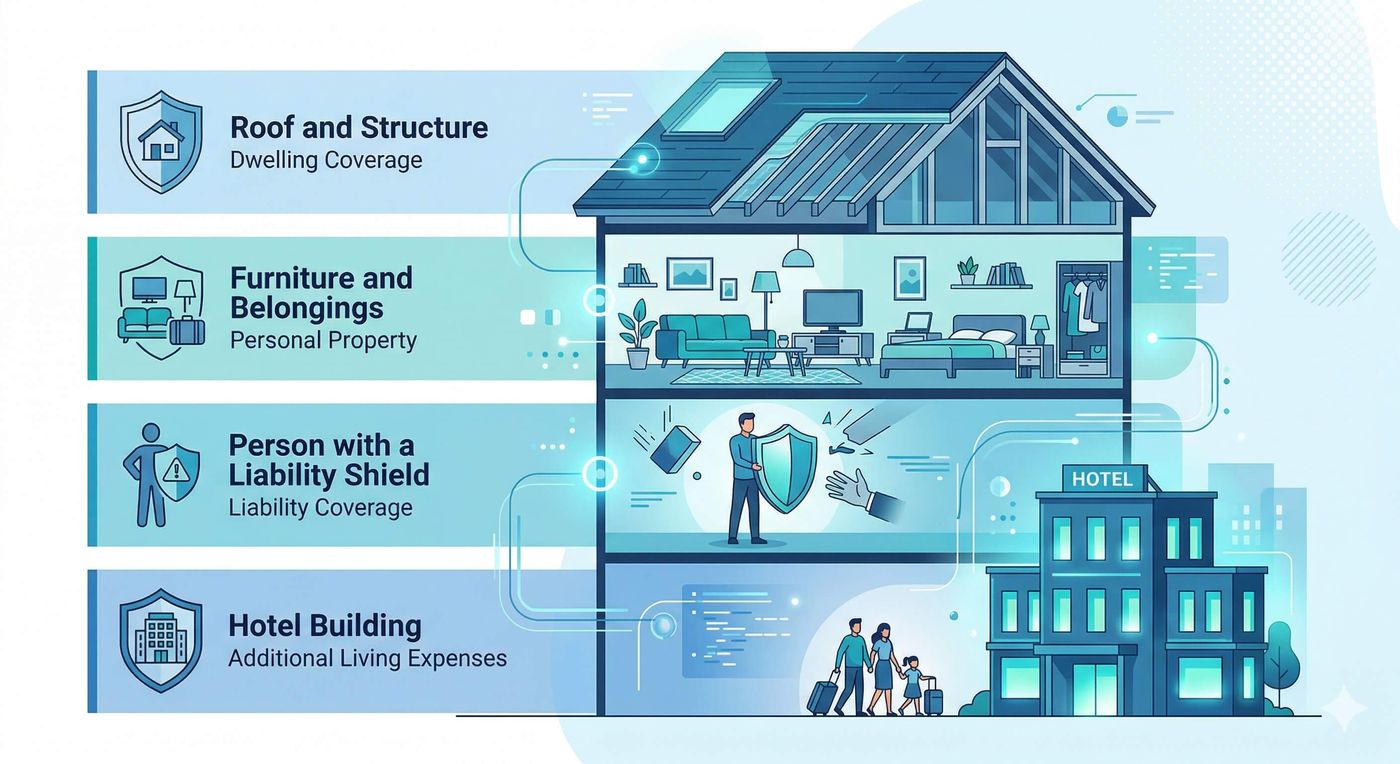
A home insurance policy is a contract where you pay regular premiums in exchange for the insurer covering specific financial risks. While terms differ by provider, standard plans typically include four main areas of coverage. Coverage for your building protects the physical structure of your home against damage from covered perils. Contents coverage applies to your personal belongings inside the home, such as furniture and electronics. Liability protection covers you if someone is injured on your property and you are found legally responsible. Additional living expenses coverage helps pay for temporary accommodation and higher day-to-day costs if your home becomes uninhabitable due to a covered event like a fire. It is important to understand that coverage is based on the replacement cost of your home and belongings, not their current market value. You should review your coverage amounts regularly, especially after major renovations or purchases.
Most policies operate on the principle that you pay a deductible, which is your out-of-pocket amount, before the insurer's coverage begins for a claim. The policy defines exactly what is and is not covered, and these details are contained in the official policy wording which governs the contract. Standard coverage is designed to protect against most common causes of loss or damage, but exclusions always apply. For comprehensive protection, many Canadians opt for a comprehensive policy, which offers the broadest coverage, as opposed to a more limited named perils policy that only covers specifically listed events.
Types of Home Insurance Policies and Optional Coverages
Beyond a standard policy, insurers offer different types of plans and endorsements to match various living situations. The main policy types are homeowner's insurance for detached houses, condo insurance for condo unit owners, tenant insurance for renters, and seasonal property insurance. While a comprehensive policy offering the most protection is the overwhelming choice for Canadians, named perils policies that cover only specific listed events are another option. Home insurance endorsements are optional coverages you can add to your policy for an additional cost. Popular endorsements include coverage for water that enters through the roof, walls, doors, or windows, which is often separate from standard water damage coverage. You can also add increased liability limits, identity theft recovery coverage, or specific protection for valuable items like jewellery. Many standard policies have lower coverage limits for valuables such as bicycles, artwork, sporting equipment, and collectibles, making endorsements necessary for full protection.
Some insurers offer unique policy features, such as the Million Dollar Solution, which provides one overall amount of coverage for your home, belongings, and additional living expenses to avoid gaps. Other customizable options include the choice to rebuild at a different location or buy different items rather than replace the exact ones you had. If you occasionally share your home as a short-term rental, specific endorsements may be available to cover that activity. It is crucial to speak with an insurance advisor to ensure you have the right endorsements for your specific situation, as coverage details and availability vary significantly between providers and provinces.
Common Factors Driving Premium Increases Across Canada
Home insurance premiums are rising across Canada due to several interconnected market factors. Inflation increases the cost of materials and labour for repairs and rebuilding, which insurers pass on to policyholders. A labour shortage in the trades industry means repairs take longer and cost more, further driving up claim costs and premiums. The increasing frequency and severity of natural disasters due to climate change have led to a high volume of costly claims. In 2025 alone, severe weather caused over $2.4 billion in insured damages from events like wildfires and flooding. These increases are not uniform across the country. Provincial variations exist, for example, as of the second quarter of 2026, Alberta's premiums increased by 11.9 percent year-over-year while Ontario's rose by 4.2 percent. All these factors combine to create upward pressure on the cost of home insurance for Canadian homeowners.
The high volume of claims from severe weather events directly pressures insurer profitability, leading to rate hikes to maintain financial stability. Rebuilding costs have escalated due to inflation in construction materials and the aforementioned labour shortages. As claims become more frequent and expensive, the risk model for entire regions changes, resulting in broader premium increases. Homeowners in areas newly deemed high-risk for flooding or wildfires may see particularly sharp premium adjustments. This trend underscores the importance of regularly comparing quotes to ensure you are still receiving a competitive rate for the coverage you need.
Steps to Get and Compare Accurate Insurance Quotes
Obtaining and comparing home insurance quotes is a straightforward process that can be completed online in just a few minutes. You begin by providing accurate information about your property and yourself through an online quote tool. It is crucial to be as honest and accurate as possible about all rating factors, as providing inaccurate information can lead to incorrect underwriting and potential policy cancellation later. The online system will use your details to generate a personalized quote from that provider. To compare effectively, you should repeat this process with multiple insurers or use a comparison service that provides quotes from several companies at once. When reviewing quotes, look beyond the premium price to compare the coverage details, deductibles, and any exclusions. Finally, you can purchase your chosen policy directly online or speak with an insurance advisor to finalize the details. You should always update your insurer about any changes to your living situation, such as new household members, pets, or renovations, to ensure continuous and accurate coverage.
Following a clear process ensures you get a realistic estimate and find suitable coverage. You should gather accurate information about your home and belongings before starting, and then use online quote tools from individual insurers or comparison sites. Providing the same information to each source allows for a fair comparison, and you must review the coverage details, limits, and exclusions in each quote carefully. Checking for applicable discounts you may qualify for, such as those for bundling or alarms, is a key step before selecting the policy that offers the best combination of coverage and value. You can then complete the purchase online or with an advisor, and remember to update your policy whenever your circumstances change to maintain proper protection.
- Gather accurate information about your home and belongings.
- Use online quote tools from individual insurers or comparison sites.
- Provide the same information to each source for a fair comparison.
- Review the coverage details, limits, and exclusions in each quote.
- Check for applicable discounts you may qualify for.
- Select the policy that offers the best combination of coverage and value.
- Complete the purchase online or with an advisor.
- Update your policy whenever your circumstances change.
Maintaining accuracy throughout this process prevents surprises when filing a claim and helps secure affordable coverage long-term. A cancellation on your record for misrepresentation can severely impact your future ability to get insurance. Once you purchase a policy, you can manage it through an online account or mobile app, where you can access proof of insurance, submit claims, and update your information. Some insurers also offer benefits like a three-year workmanship warranty for repairs if you use their network of vendors for a claim.
Available Discounts to Lower Your Home Insurance Premium
Many insurers offer discounts that can help reduce your home insurance premium while maintaining your coverage. One of the most common and significant savings comes from bundling your home and auto insurance with the same provider, with potential savings advertised up to 15 percent or an average of $960 annually. Installing protective devices like a centrally monitored alarm system for fire or theft, or a centrally monitored water alarm to help prevent water damage, can also qualify you for reduced rates. Insurers often provide discounts for newer homes, typically those five years old or less, as they are considered less risky. Maintaining a claim-free record can lead to substantial savings, with some companies offering an average discount of 25 percent for new claims-free customers. Membership in certain alumni associations, professional groups, or employer-sponsored plans can grant access to preferred group rates. Choosing a higher deductible, which is the amount you pay out of pocket on a claim, will lower your regular premium. Retirees may also enjoy specific discounts on their home insurance policies.
Additional savings opportunities exist, such as extra discounts for quoting and buying your policy online, which can save 10 percent off your first term. If your home is mortgage-free, some insurers provide exclusive savings on your policy. Insuring multiple properties with the same company can lead to further discounts. Some providers offer rewards or discounts for installing specific water leak detection systems. It is important to actively search for and ask about these discounts when getting quotes, as they are not always applied automatically. The specific savings percentages and eligibility criteria vary by insurer and province, so you should confirm details during the quote process.
Provincial Variations and Key Considerations for Quotes
Home insurance premiums and the factors influencing them can vary significantly across Canadian provinces. Your postal code is a primary rating factor because it indicates local risks such as the probability of flooding, wildfire, or crime. As noted, Alberta experienced an 11.9 percent year-over-year premium increase as of the second quarter of 2026, reflecting higher regional risks and claim costs. Ontario's increase for the same period was 4.2 percent. Provincial insurance regulations also differ, affecting available coverage options and policy wordings. For instance, optional coverages for risks like sewer backup or overland water may be more critical and priced differently depending on the province's typical weather patterns. When getting quotes, it is important to confirm that the policy meets any specific provincial requirements. The availability of certain discounts, like those for monitored alarm systems, is generally consistent, but the exact savings percentage can vary by provider and region. Always review the policy details to understand what perils are covered and excluded based on your location.
Insurers must adhere to the insurance laws and regulations of each province, which can influence standard policy forms and mandatory coverages. The legal liability environment in a province can also affect the cost of liability coverage within a home insurance policy. Some provinces have provincially administered insurance systems or unique rules that impact how private insurers operate. When comparing quotes, ensure you are comparing equivalent coverage levels, as the baseline protection can differ slightly from one region to another. For the most accurate provincial comparison, use online tools that allow you to filter quotes by province or territory to see localized averages and offers.
Important Mistakes to Avoid When Getting Quotes
Avoiding common mistakes during the quote and purchase process is essential for securing valid and affordable home insurance. The most significant error is providing inaccurate or dishonest information on your application to try to secure a lower rate. This misrepresentation can lead to incorrect underwriting and, if discovered, result in policy cancellation, which severely impacts your future insurability and cost. Another mistake is focusing solely on the premium price without comparing the actual coverage details, limits, deductibles, and exclusions between quotes. Failing to inquire about and apply all eligible discounts, such as those for bundling, alarms, or group memberships, can mean leaving money on the table. Neglecting to update your insurer about major changes, such as renovations, acquiring high-value items, or starting a home-based business, can leave you underinsured when a claim occurs.
Assuming all types of water damage are covered is a specific and costly misunderstanding, as standard policies typically exclude sewer backup and overland flooding. Not reviewing your policy annually to ensure your coverage limits still match the replacement cost of your home and belongings is another oversight, especially in times of high inflation. Finally, not shopping around and comparing quotes from multiple providers at renewal time can result in overpaying, as loyalty discounts are often less substantial than introductory rates from competitors. By being thorough, honest, and proactive, you can avoid these pitfalls and secure a policy that provides reliable protection.
Frequently asked questions
Does home insurance cover water damage?
Coverage for water damage depends on the cause. Standard policies typically cover sudden and accidental water damage from internal sources, such as a burst pipe or an appliance failure. However, protection for losses like sewer backup or overland water flooding usually requires purchasing optional coverage or an endorsement. Damage from gradual leaks, seepage, or coastal flooding is generally not covered.
How do I get a home insurance quote?
You can get a home insurance quote quickly and easily online. Most major insurers and brokerage websites offer online quote tools where you answer questions about your property and coverage needs. The process is confidential and usually takes just a few minutes to generate a personalized premium estimate. You can also speak with an insurance advisor or broker over the phone to get a quote.
What happens if I provide wrong information on a quote?
Providing inaccurate information when getting a quote can lead to incorrect underwriting. If discovered, this misrepresentation could result in your policy being cancelled later. A cancellation on your record for this reason can severely impact your ability to secure affordable home insurance in the future. It is essential to be honest and update your insurer about any changes to ensure you are properly covered.
Is home insurance mandatory in Canada?
Home insurance is not legally required in Canada. However, it is a smart and often non-negotiable financial decision. Most mortgage lenders require it as a stipulation in the mortgage agreement before approving the loan. Even if you own your home without a mortgage, insurance is strongly recommended to protect your large investment from significant financial risks such as fire, theft, and liability. As a homeowner, having this coverage is crucial for safeguarding your property and finances against unexpected damage.
What does home insurance typically cover?
A standard home insurance policy typically includes coverage for four main areas. It covers the building itself, your personal belongings or contents, liability protection, and additional living expenses if you cannot stay in your home after a covered loss. Covered events, known as perils, often include fire, wind, hail, and theft. Policies are contracts where you pay regular premiums, and the insurer agrees to cover these financial risks. The specific terms and covered perils can differ depending on the provider and the type of policy you select.
How can I save money on my home insurance?
You can save money on home insurance through several methods. Bundling your home and auto insurance with the same provider can save you up to 15 percent or an average of $1050. Installing centrally monitored alarm systems for theft, fire, or water leaks can also lead to discounts. Choosing a higher deductible will lower your premium. Other savings include maintaining a claims free record, which can save an average of 25 percent for new customers, and accessing preferred rates through eligible alumni, professional associations, or employer groups. Regularly reviewing your policy ensures you have the right coverage.
Sources and further reading
- Compare Home Insurance Quotes Online & Start Saving ratehub.ca
- Home Insurance Quotes in Canada, Save Up to 15% rbcinsurance.com
- Get A Home Insurance Quote tdinsurance.com
- Intact Insurance: Canada's Largest P&C Insurer | Car & Home ... intact.ca
- Get a Home Insurance Quote Today allstate.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.