Cheap home insurance in Canada refers to securing adequate property coverage at a lower cost, which is increasingly important as premiums rise across the country. The average annual home insurance cost is approximately $1,300, but this varies significantly by province, property type, and individual risk factors. Home insurance is not legally required, but it is a standard condition for obtaining a mortgage from a lender. Canadians can lower their premiums through strategies like bundling policies, installing protective devices, and maintaining a claims-free record.
What Determines Your Home Insurance Premium
Your home insurance premium is calculated based on the level of risk you and your property present to the insurer. The location of your home provides critical information on potential risks like flooding, fire, or break-ins, which directly influences your rate. Insurers also consider the age and construction type of your home, with newer homes generally qualifying for lower premiums due to a lower risk of issues like broken pipes or electrical failures. Other factors include your claims history, the coverage limits and deductible you choose, and specific features like your home's heating systems. Market-wide factors such as inflation, rising rebuilding costs, labour shortages in the trades industry, and the increasing frequency of severe weather events also drive premium increases across Canada. In the second quarter of 2026, the national average premium increased by 5.8 percent year-over-year, with Alberta experiencing an 11.9 percent increase and Ontario a 4.2 percent increase.
Standard Coverage and Common Policy Types
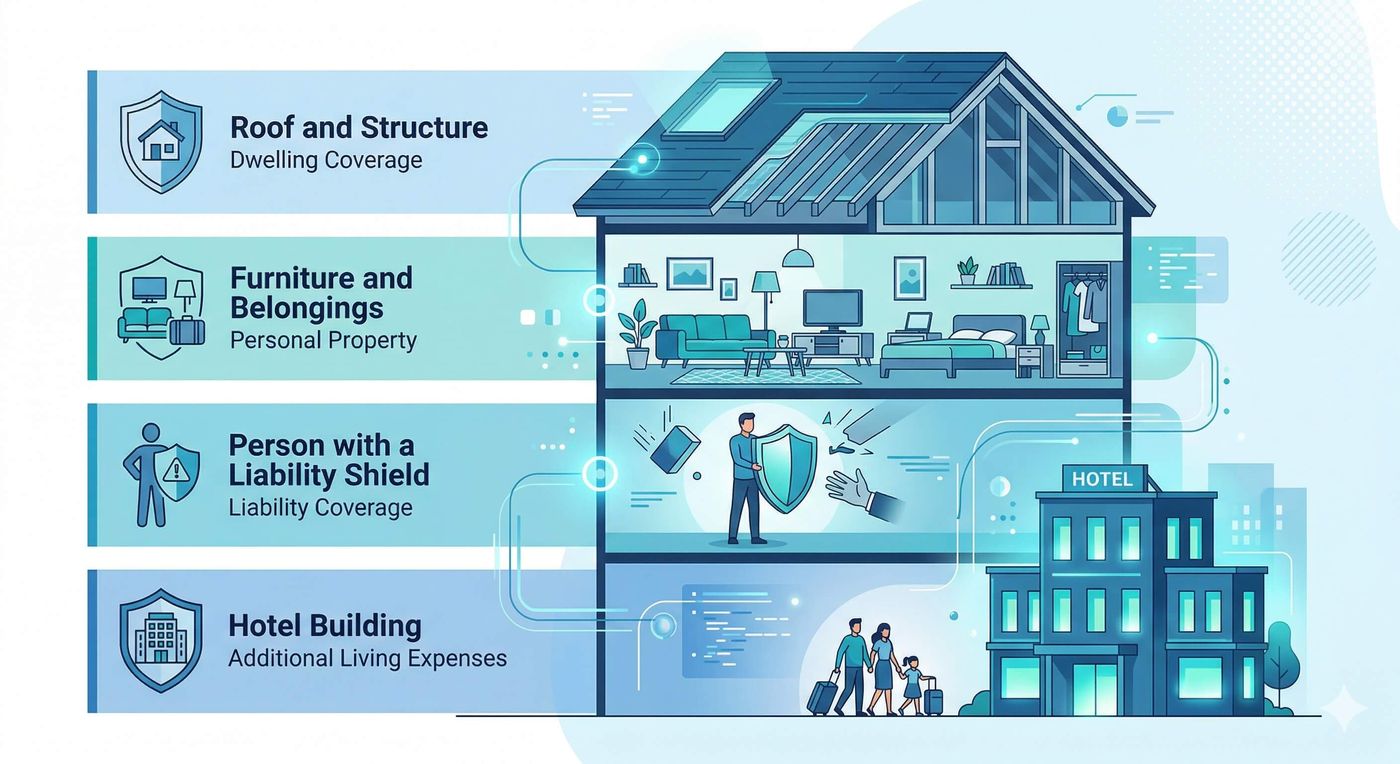
A home insurance policy is a contract where you pay regular premiums in exchange for the insurer's agreement to cover financial risks associated with your property. While terms differ by provider, standard plans typically include four core areas of coverage. Coverage for your dwelling helps pay to repair or rebuild your home's structure after a covered event like fire or wind damage. Liability protection covers you if someone is injured on your property and you are found legally responsible. Contents coverage applies to your personal belongings inside the home against perils like theft. Additional living expenses coverage helps pay for temporary accommodation and living costs if your home becomes uninhabitable after a covered loss. Home insurance in Canada is primarily offered through several policy types tailored to different living situations.
The most common policy types available in Canada are designed for specific property ownership models. A comprehensive homeowner's insurance policy is the most common choice for owners of detached houses, semi-detached houses, or townhouses, as it offers the broadest protection. Condo insurance is specifically for owners of a condominium unit, covering the interior of the unit, personal liability, and belongings, while the building's exterior and common areas are typically covered by the condo corporation's master policy. Tenant insurance, also known as renter's insurance, provides coverage for a renter's personal belongings and liability within a rented dwelling. Landlord insurance is designed for property owners who rent out their homes to tenants, covering the building and providing liability protection, and it can include coverage for lost rental income.
Proven Strategies to Lower Your Insurance Costs
There are several effective methods to reduce your home insurance premium while maintaining necessary coverage. One of the most significant savings comes from bundling your home and auto insurance policies with the same provider, which can save you up to 15 percent on your home insurance. Increasing your deductible, which is the amount you pay out of pocket on a claim, will lower your regular premium payments. Installing protective devices can also lead to discounts. For example, a centrally monitored water alarm system can help prevent water damage and may reduce your rate, and a centrally monitored security alarm system for fire or theft can similarly lower premiums. Maintaining a claim-free record over time is another way to qualify for reduced rates, as it demonstrates lower risk to the insurer.
Other discounts and considerations can contribute to a more affordable premium. Some insurers offer reduced rates for members of organizations that sponsor a group home and auto insurance plan. If your home is mortgage-free, you may be eligible for exclusive savings on your policy with certain providers. Retirees may also enjoy specific discounts on their home insurance. Choosing to get a quote and purchase your policy online can sometimes result in additional savings compared to other purchasing methods. It is crucial to review your policy regularly to ensure your coverage amounts are accurate and to update your insurer about any changes, such as renovations or major purchases, which can affect your rate and coverage needs.
- Bundle home and auto insurance to save up to 15%.
- Increase your deductible to lower your premium.
- Install a centrally monitored water alarm system.
- Install a centrally monitored security alarm system.
- Maintain a claim-free record.
- Qualify for group discounts through affiliated organizations.
- Receive a discount for a mortgage-free home.
- Get a discount for being a retiree.
Understanding Covered and Excluded Perils
In home insurance, a peril is an event that causes loss or damage to your property. Standard policies typically cover a range of sudden and accidental events. Commonly covered perils include fire, wind, hail, and theft. Sudden and accidental water damage from a burst pipe or an appliance failure is also generally covered. If your home becomes uninhabitable due to a covered event, your policy's additional living expenses coverage can help pay for hotel stays and other temporary costs. However, many significant risks require additional, optional coverage or are explicitly excluded from standard policies.
Damage from gradual leaks, seepage, or coastal flooding is not covered under a standard home insurance policy. Protection for losses such as sewer backup or overland water often requires the purchase of optional endorsements for an additional cost. Other common exclusions include earthquake damage and general wear and tear. It is essential to review your policy details carefully or speak with an insurance advisor to understand exactly what is and is not covered, as optional add-ons like enhanced water damage coverage or limited sewer backup coverage have specific eligibility criteria, limits, and conditions.
- Covered: Fire, wind, and hail damage.
- Covered: Theft of personal belongings.
- Covered: Sudden and accidental water damage (e.g., burst pipe).
- Covered: Additional living expenses after a covered loss.
- Excluded: Damage from gradual leaks or seepage.
- Excluded: Coastal flooding.
- Often Excluded: Sewer backup (requires endorsement).
- Often Excluded: Overland water (requires endorsement).
Optional Endorsements and Added Protections
A home insurance endorsement is an optional coverage you can add to your policy for an additional premium. These add-ons allow you to customize your protection against specific risks that are excluded from your base policy. The types of endorsements offered vary by provider, but several are commonly available across the Canadian market. Adding these coverages increases your overall premium but can provide critical financial protection against expensive perils. It is important to note that endorsements have their own limits, deductibles, and eligibility conditions, which should be reviewed in the policy wording.
Popular endorsements include enhanced water damage coverage, which may protect against sewer backup, overland water, flood, surface water, and rapid groundwater accumulation, subject to property location and mitigation measures. Limited sewer backup coverage is a specific endorsement protecting against damage from water escaping from a sewer, drain, sump pit, or septic tank. Climate loss mitigation coverage is available from some insurers, providing up to $2,500 for reasonable expenses to safeguard property when an evacuation alert or order is issued due to climate or wildfire risk. Other common endorsements increase protection for special belongings like jewellery, watches, artwork, bicycles, sporting equipment, technology, wine, and collectibles, as standard policies often have lower default limits for these items.
The Process of Getting and Comparing Quotes
Obtaining and comparing home insurance quotes is a straightforward process that can be completed online in minutes. You can start a quote directly on an insurer's website or through a comparison platform that aggregates quotes from multiple top Canadian providers. The online tools will ask a series of questions about your property, its location, construction details, and the desired coverage to generate a personalized premium estimate. It is vital to be as honest and accurate as possible during this process, as providing inaccurate information can lead to incorrect underwriting and potential policy cancellation later. Being upfront ensures you receive a realistic estimate and prevents complications when filing a claim.
When comparing quotes, you should look beyond just the premium cost. Evaluate the coverage limits, deductibles, and specific exclusions in each policy. Check what optional endorsements are available and their cost, such as those for valuable items like jewellery, art, or bicycles, which often have lower default coverage limits. Consider the insurer's reputation for customer service and claims handling, including whether they offer 24-hour emergency claims service. Remember that having a policy cancelled for misrepresentation can severely impact your ability to secure affordable insurance in the future, so transparency from the start is crucial for long-term financial protection.
- Use an online quote tool on an insurer or comparison website.
- Answer all questions about your property and needs honestly and accurately.
- Compare the premium, coverage limits, and deductibles from multiple providers.
- Review the list of covered and excluded perils in each policy.
- Check the availability and cost of optional endorsements.
- Consider the insurer's claims service and customer support reputation.
- Select a policy that offers the right balance of coverage and cost.
- Update your insurer regularly about any changes to your home or situation.
Provincial Variations and Market Trends
Home insurance costs and trends are not uniform across Canada and are influenced heavily by provincial and regional risk factors. As of the second quarter of 2026, Alberta experienced the highest year-over-year premium increase at 11.9 percent, while Ontario's increase was 4.2 percent. These variations reflect differences in local risks, such as the frequency of severe weather events, wildfire exposure, and regional construction costs. The increasing frequency and severity of natural disasters due to climate change are major drivers of national premium increases, with severe weather causing over $2.4 billion in insured damages in 2025 alone. Insurers pass these higher claim costs on to policyholders through rate adjustments.
Other national market factors consistently pressure premiums upward across all provinces. Inflation affects the cost of materials and labour for home repairs and rebuilding. A labour shortage in the trades industry means repairs take longer and cost more, further increasing claim expenses. These combined factors mean that shopping for competitive rates and implementing cost-saving measures is an ongoing consideration for Canadian homeowners. The availability of certain coverages, like overland water protection, can also vary significantly by province and even by postal code based on local flood risk assessments.
Key Considerations for Policy Management
Effectively managing your home insurance policy is essential for maintaining adequate coverage and controlling costs over time. You should review your policy regularly, especially after major life events or changes to your property, to ensure your coverage limits still reflect the cost to rebuild your home and replace your belongings. Coverage is based on replacement cost, not the market value of your home, so this distinction is important. After renovations or major purchases, you must inform your insurer, as these changes can affect your home's replacement value and risk profile. Failure to update your policy could result in being underinsured when you need to make a claim.
You can cancel your home insurance policy at any time, but cancellation fees may apply depending on the insurer and the timing. If you switch providers, it is critical to avoid any gap in coverage, as a lapse can be viewed negatively by future insurers. Many insurers offer online account management portals or mobile apps where you can access policy documents, submit claims, make payments, and update information. Some providers offer specific guarantees, like a home replacement cost guarantee, which requires you to insure your dwelling to 100 percent of its replacement cost and accept annual coverage adjustments. Always refer to your actual policy wording for the governing terms and conditions.
Frequently asked questions
How can I get the cheapest home insurance rate?
To find a lower premium, compare quotes from multiple insurers online. Bundling your home and auto insurance with one company can save up to 15 percent. Choosing a higher deductible, installing monitored alarm or water leak detection systems, and maintaining a claim-free record can also reduce your costs. Always provide accurate information when getting quotes to ensure your rate is valid.
What factors make home insurance more expensive?
Key factors that increase premiums include living in an area with high risks for flooding, wildfires, or crime. Having an older home. Filing previous claims. And choosing lower deductibles. National trends like inflation, rising rebuilding costs, and increased severe weather claims also drive up costs for all policyholders.
Is home insurance mandatory in Canada?
Home insurance is not legally required in Canada, but most mortgage lenders require it before approving a mortgage. Even if you own your home without a mortgage, having coverage is a smart financial decision to protect your large investment. It helps safeguard your home, belongings, and finances from major covered losses like fire, theft, and liability. As a homeowner, you face significant financial risk, so insurance provides essential protection. While not a legal mandate, it is often a non-negotiable condition for securing financing.
What is the average cost of home insurance in Canada?
The average annual cost of home insurance in Canada is about $1,300, but this can vary significantly. Costs depend on factors like your province, property location, home type, construction, coverage limits, and claims history. Premiums are rising across the country, with a national average increase of 5.8 percent year over year as of the second quarter of 2026. Market factors such as inflation, rising rebuilding costs, and increased severe weather claims contribute to these rising costs. The easiest way to get an accurate idea of your cost is to use an online quote tool or speak with an insurance advisor.
Does home insurance cover water damage?
Standard home insurance typically covers sudden and accidental water damage, such as from a burst pipe or an appliance failure. However, protection for losses like sewer backup or overland water usually requires purchasing optional coverage for an additional cost. Damage from gradual leaks, seepage, or coastal flooding is generally not covered. It is crucial to review your policy details carefully to understand what is included. You should speak with an insurance advisor to ensure you have the right water damage coverage for your specific situation.
What should I do if my home insurance premium increases?
If your premium increases, you should shop around and compare quotes from multiple providers to find a competitive rate. You can also ask your current insurer about discounts you may qualify for, such as bundling home and auto insurance for savings of up to 15 percent. Installing protective devices like a centrally monitored water alarm or security system can also help lower premiums. Another option is to choose a higher deductible, which is the amount you pay out of pocket on a claim, to reduce your premium costs. Regularly reviewing your policy ensures you have the right coverage at the best available price.
Sources and further reading
- Home Insurance Quotes in Canada, Save Up to 15% rbcinsurance.com
- Compare Home Insurance Quotes Online & Start Saving ratehub.ca
- Sonnet Insurance | Insurance Made Simple with Online Quotes sonnet.ca
- Get a Home Insurance Quote Today allstate.ca
- Intact Insurance: Canada's Largest P&C Insurer | Car & Home ... intact.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.