The Disability Tax Credit (DTC) is a non-refundable federal income tax credit for Canadians with severe and prolonged impairments. It reduces the amount of income tax an eligible person or their supporting family member may owe. The application process involves submitting Form T2201, the Disability Tax Credit Certificate, which must be certified by a medical practitioner. Approval for the DTC can also provide access to other disability-related benefits and programs.
Understanding the Disability Tax Credit
The Disability Tax Credit is a federal program designed to offset some of the extra costs associated with living with a disability by reducing income tax liability. It is a non-refundable credit, meaning it can reduce tax owed to zero but will not result in a refund if the credit amount exceeds the tax payable. For 2026, the federal base amount is $10,341. An individual under the age of 18 may also be eligible for an additional supplement of up to $6,032 per year. The DTC is not a monthly payment but is claimed when filing an annual income tax return. Approval for the DTC can serve as a gateway to other programs, such as the Registered Disability Savings Plan, the Canada Workers Benefit Disability Supplement, and the Child Disability Benefit.
Eligibility Requirements for the DTC
Eligibility for the Disability Tax Credit is based on the functional impact of an impairment, not on a specific medical diagnosis alone. To qualify, an individual must have a severe and prolonged impairment in physical or mental functions. The impairment must have lasted, or be expected to last, for a continuous period of at least 12 months. The Canada Revenue Agency assesses eligibility primarily through three possible pathways. The first is a marked restriction in at least one basic activity of daily living, which means being significantly limited all or almost all the time. The second pathway is having significant limitations in two or more basic activities of daily living. The third pathway is requiring life-sustaining therapy, such as dialysis or insulin therapy, which must generally be needed at least twice a week for an average of 14 hours per week.
The activities of daily living considered by the Canada Revenue Agency include walking, feeding, dressing, eliminating, hearing, speaking, vision, and mental functions necessary for everyday life. Mental functions specifically encompass adaptive functioning, attention, concentration, goal setting, judgement, memory, perception of reality, problem solving, regulation of behaviour and emotions, and verbal and non verbal comprehension. To have a marked restriction, the CRA generally requires that an individual's ability to perform an activity is restricted all or almost all the time. This means it takes at least three times longer than someone of a similar age without a disability would take. Alternatively, a person may qualify if they require life sustaining therapy to support a vital function.
How to Apply for the Disability Tax Credit
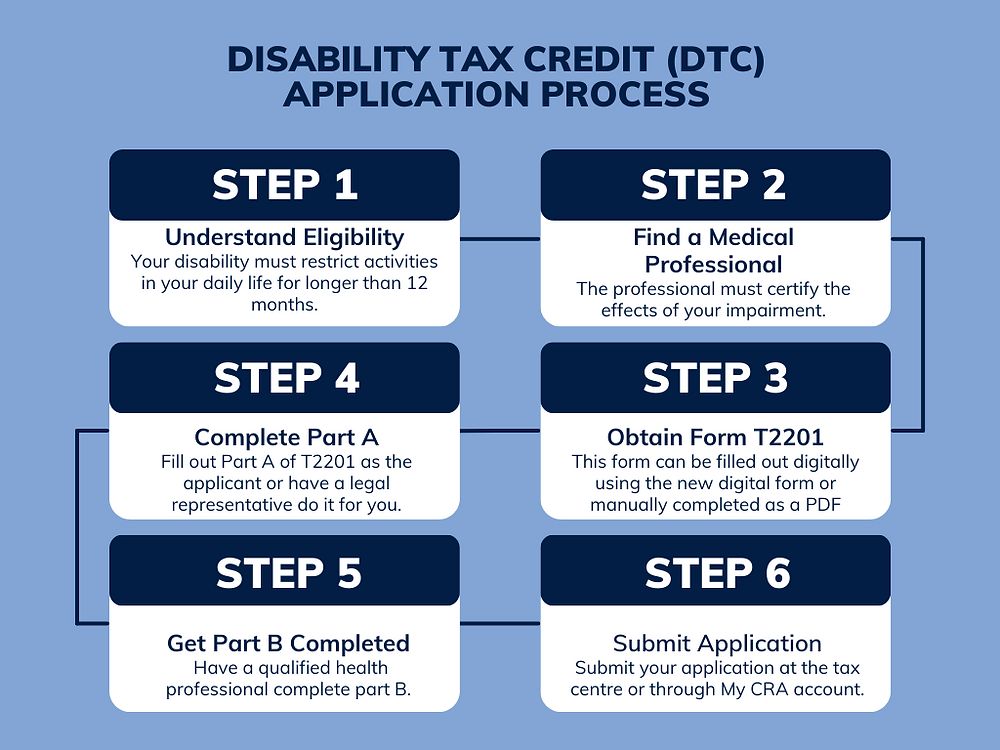
The application for the Disability Tax Credit is Form T2201, the Disability Tax Credit Certificate. The form is divided into two parts that must be completed. Part A is for the applicant, who is the person with the disability or their legal representative. This section collects personal information and authorizes the CRA to process the application. Part B must be completed by a qualified medical practitioner to certify the nature, duration, and severity of the impairment. Once both parts are complete, the form must be submitted to the CRA for review. There are several methods to submit the application, and the CRA offers multiple channels to accommodate different needs.
You can apply online through your CRA My Account. After signing in, you select your Individual account, go to Benefits and credits, and select the Apply for DTC button to open the digital form. Completing Part A online will generate a reference number for your medical practitioner to use when they complete Part B digitally. As of July 14, 2026, you cannot submit additional documents with an online application unless the CRA specifically requests them. You can also apply by phone by calling a CRA agent at 1-800-959-8281 or using the automated service at 1-800-463-4421. The agent will submit Part A on your behalf and provide a reference number for your practitioner.
For a paper application, you must download and print the latest version of Form T2201 from the CRA website. As of September 8, 2026, the CRA will no longer accept T2201 forms issued before 2023. You complete and sign Part A yourself, and your medical practitioner completes Part B on the paper form. The completed form is then mailed to the appropriate CRA tax centre, with addresses listed on the form's last page. A medical practitioner can also submit the application on your behalf by mailing in a hard copy they have completed.
Completing Form T2201 with a Medical Practitioner
The medical certification in Part B of Form T2201 is a critical component of the application. The practitioner must be appropriately licensed and qualified to assess the impairment in question. A medical doctor or psychiatrist can certify any category of impairment. An optometrist can certify impairments related to vision, an audiologist for hearing, an occupational therapist for walking, feeding, or dressing, a psychologist for mental functions, a speech-language pathologist for speaking, and a physiotherapist for walking. If you do not have a regular medical practitioner, you can explore options such as provincial primary care registries, asking within your network, contacting local clinics directly, or using virtual care services, though some may charge a fee.
Medical practitioners may charge a fee for completing Form T2201, typically ranging from $100 to $250. This fee is an eligible medical expense that can be claimed on your income tax return. Starting September 1, 2026, individuals approved for the Canada Disability Benefit will automatically receive a one-time, lump sum payment of $150 to partially offset this cost. It is advisable to prepare for the appointment by reviewing the form and your restrictions thoroughly to help your practitioner provide accurate and comprehensive information. If you are visiting a new medical practitioner, bringing any relevant medical history or documentation can be very helpful for the assessment.
What Happens After You Apply
After submitting Form T2201, the CRA will review your application. The standard processing time is approximately 8 weeks, though this can vary. Once the review is complete, the CRA will send you a Notice of Determination letter informing you of their decision. If approved, the letter will specify the years for which you are eligible. The DTC can be claimed retroactively for up to 10 previous tax years, provided the impairment was present during those years. You do not need to reapply every year once approved. You simply claim the credit on your annual tax return until the CRA asks you to reapply or your approval period expires.
If your application is denied, you have the right to file an official objection within 90 days of the date on the Notice of Determination. The objection process involves submitting a formal request for a review, following the instructions provided by the CRA. It is important to provide any additional information or clarification that may support your case during this review. The CRA's decision on the objection will be communicated in writing, and further appeals may be possible through the courts.
Common Mistakes and Where to Get Help
Several common issues can delay or derail a DTC application. Using an outdated version of Form T2201 is a frequent error. Applicants must ensure they use the current form, especially as forms issued before 2023 will not be accepted after September 8, 2026. Incomplete forms, particularly missing signatures in Part A, will not be processed. Another mistake is focusing solely on a medical diagnosis rather than clearly describing the functional limitations and their severe and prolonged impact on daily living. Not providing enough detail for the medical practitioner to complete Part B accurately can also lead to a denial. When applying, you can indicate you have more than one disability, which may improve your chances of qualifying even though it does not change the credit amount.
Many individuals may need assistance with the application process. Several non-profit organizations offer free help, such as the Mood Disorders Society of Canada's Pathway to Benefits project or disability-specific groups like the Canadian Association of the Deaf. Inclusion Canada's Barriers-Free Benefits program provides free, one-on-one help with disability benefits through navigators. While private companies also offer application assistance, they often charge a fee or take a percentage of the credit, so exploring free options first is generally advisable. For general questions, you can contact the CRA directly at 1-800-959-8281. The CRA can also provide information on eligibility and help start an application over the phone.
Federal and Provincial Credit Amounts
The Disability Tax Credit consists of a federal amount and a corresponding provincial or territorial amount. The federal base amount for the 2026 tax year is $10,341. This amount is used to calculate the federal tax credit, which reduces federal income tax payable. Each province and territory adds its own supplement, which reduces provincial or territorial income tax. The combined value of the credit therefore depends on where you live. For example, the Ontario disability amount for 2026 is also a significant figure that aligns with the federal structure. The total credit value is not a direct payment but a reduction of taxes owed, and its benefit depends on the individual's or supporting family member's income tax liability.
| Jurisdiction | Credit Component |
|---|---|
| Federal | Base amount of $10,341 (2026) |
| Provincial/Territorial | Varies by province/territory |
| Child Supplement (Under 18) | Up to $6,032 additional federal amount |
The additional supplement for individuals under 18 is a federal amount of up to $6,032 per year. This supplement is designed to recognize the extra costs of caring for a child with a disability. It is important to note that the DTC amounts are subject to annual indexation, so they may change slightly each year based on inflation. The exact provincial amounts can be found on the respective provincial revenue agency websites or within the CRA's tax guides. If a family member qualifies for the DTC, an unused portion of the credit may be transferred to an eligible supporting relative, such as a spouse or dependant, on their tax return.
Frequently asked questions
What is the Disability Tax Credit?
The Disability Tax Credit is a non refundable federal income tax credit for Canadians with severe and prolonged impairments. It reduces the amount of income tax that an eligible person or their supporting family member might have to pay. The credit is meant to help cover some of the extra costs related to a disability. Approval for the DTC can also help you get access to other federal, provincial, or territorial programs.
How do I apply for the Disability Tax Credit?
You apply for the Disability Tax Credit by submitting Form T2201, which is the Disability Tax Credit Certificate. You can apply by paper form or by online form through your CRA My Account. Part A of the form must be filled out by the person with a disability or their legal representative. Part B must be completed and certified by a qualified medical practitioner.
Who is eligible for the Disability Tax Credit?
To be eligible for the Disability Tax Credit, you must have a severe and prolonged impairment in physical or mental functions. A medical practitioner must certify that you have a marked restriction in at least one basic activity of daily living. Your impairment must have lasted or be expected to last for a continuous period of at least twelve months. You must also live in Canada for tax purposes and have a valid Social Insurance Number.
Can I claim the DTC for past years?
Yes, the Disability Tax Credit can be claimed retroactively for up to ten previous tax years. This means if you have been living with a severe and prolonged impairment for years before applying, the Canada Revenue Agency may reassess your past returns upon approval. The DTC is a non refundable tax credit that reduces income tax payable. Being approved for past years can provide significant financial relief by adjusting taxes owed in those years. It is important to apply even if you did not work in the past, as a successful application unlocks this retroactive claim option.
What if my DTC application is denied?
If your Disability Tax Credit application is denied by the Canada Revenue Agency, you have the right to file an official objection. You must submit this objection within 90 days of the date on the denial letter, which is called a Notice of Determination. The process for filing an objection is outlined on the CRA website. It is important to act promptly within this timeframe to dispute the decision. You can seek free help with this process from organizations like Inclusion Canada's Barriers Free Benefits program, which offers navigation support.
Do I need to reapply for the DTC every year?
No, you do not have to reapply for the Disability Tax Credit every year once approved. After receiving approval from the Canada Revenue Agency, you simply claim the credit on your subsequent annual income tax returns. You continue to claim it each year until the CRA asks you to reapply or your approval period expires. The DTC is a non refundable tax credit claimed on line 31800 or 32600 of your return. This ongoing claim process applies unless your condition improves or the CRA requests a new Form T2201 to reconfirm eligibility.
Sources and further reading
- Disability Tax Credit (DTC) inclusioncanada.ca
- The Disability Tax Credit Application Guide disabilitycreditcanada.com
- A Guide to the Canada Disability Tax Credit disabilityawards.ca
- Applying for the DTC, Canada Disability Benefit canadadisabilitybenefit.ca
- Form T2201, Disability Tax Credit (DTC) explained wealthsimple.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.