Financial planning services in Canada are professional offerings designed to help individuals and families create comprehensive strategies to achieve their long-term financial goals. These services typically involve an advisor or planner who examines a client's entire financial picture, including investments, taxes, retirement, and estate planning. The landscape includes a range of providers from large financial institutions to independent firms and certified professionals. For Canadians, engaging with these services can provide structured guidance to handle complex financial decisions and adapt plans through life's changes.
What Financial Planners and Advisors Do
A financial planner is a type of financial advisor who specializes in creating a holistic plan to reach long-term financial goals. These professionals look at every aspect of a Canadian's financial picture, which includes investments, retirement income sources like CPP and RRSPs, tax efficiency, debt repayment strategies, and estate planning. The process often begins with an initial conversation where the planner seeks to understand the client's values, concerns, and specific objectives. From there, they develop a strategy that may incorporate insurance to maintain a family's lifestyle, optimize savings, and provide advice on maximizing donations in tax-efficient ways. The goal is to build a plan that is unique to the individual client and can be proactively adapted as life circumstances change.
Financial planning goes beyond simple investment management to include risk reduction and strategic planning for major expenditures. For business owners, advisors can recommend strategic and tax-efficient ways to finance business growth. A comprehensive plan, such as the IG Living Plan, calculates total retirement income from all potential sources and can incorporate a savings schedule for future goals. The relationship is intended to be lifelong, with the advisor getting to know a client's family to help keep them on track through various life stages. This collaborative approach uses digital tools and ongoing conversations to refine strategies and ensure they remain aligned with the client's evolving priorities.
Types of Service Providers and Their Structures
The Canadian financial planning landscape is served by several types of organizations, each with different structures and service models. Major financial institutions like TD Wealth offer financial planning and private wealth management solutions, with services divided into tiers based on asset levels. Independent firms also play a significant role, with companies like Raymond James Ltd. noting they are Canada's largest independent financial services firm. Furthermore, holistic, full-service wealth management firms like PWL Capital aim to simplify wealth for Canadians by cutting through complexity to focus on core financial goals.
Service models can vary in how clients interact with their planners. For example, TD Wealth offers two distinct pathways within its financial planning division: working with a dedicated planner or connecting remotely with the TD Wealth Financial Planning Direct team, which provides more flexible hours. IG Wealth Management emphasizes a personalized approach where advisors cultivate relationships to understand family goals. The minimum investment requirements to access these services differ, with standard financial planning services at one major bank requiring a minimum of $100,000 in investable assets, while private wealth management services at the same institution require a minimum of $1,000,000.
- Full-Service Wealth Management Firms (e.g., IG Wealth Management, PWL Capital)
- Major Bank Wealth Divisions (e.g., TD Wealth Financial Planning)
- Independent Financial Services Firms (e.g., Raymond James Ltd.)
- Certified Professionals (QAFP, CFP) found via tools like FP Canada's 'Find Your Planner'
- Professional Membership Associations (e.g., Advocis)
Professional Designations and Industry Standards
In Canada, FP Canada is a central body that certifies financial planning professionals. It equips individuals with the qualifications to become a Qualified Associate Financial Planner (QAFP) professional or a Certified Financial Planner (CFP) professional. These designations signify that an individual has met specific education, examination, experience, and ethics requirements. Consumers can use FP Canada's 'Find Your Planner' tool to locate a QAFP or CFP professional near them who meets their unique needs. This provides a level of assurance regarding the planner's competency and commitment to a professional standard.
The industry also includes voluntary professional associations, the largest of which is Advocis, The Financial Advisors Association of Canada. Advocis represents over 7,400 financial advisors and has 26 chapters across the country. A key advocacy issue for this association, as of recent statements, is the call for a national framework for financial advisor and planner title protection. This push highlights an ongoing concern within the industry about consumers potentially receiving advice from unqualified individuals, which Advocis has framed as a risk to Canada's financial future. The association also operates three National Schools and has committees, such as an Emerging Leaders Committee, to help shape its future direction.
The Financial Planning Process and Key Tools
The financial planning process typically starts with a detailed discovery phase where the advisor seeks to understand what is important to the client. This includes discussing values, concerns, and specific goals such as funding a child's education, buying a home, or planning for retirement. Advisors use this information to build a customized plan. Firms like IG Wealth Management utilize proprietary tools like the IG Living Plan, which is designed to incorporate all major expenditures and provide a structured savings schedule. This tool calculates retirement income by aggregating all potential sources, including government benefits, registered accounts, and pensions.
The resulting plan addresses multiple financial areas in an integrated manner. It includes strategies for tax efficiency, aiming to ensure clients do not overpay taxes by missing available credits and deductions. Estate planning components provide advice on the transfer of wealth. For investment management, advisors often select from a range of investment solutions, which may include curated asset managers from around the world. The plan is not static. Advisors emphasize the need to update it as life changes, citing occasions like changes in family structure or wealth as triggers to review one's will and overall strategy. The process is collaborative, often supported by digital experiences that allow clients to engage with their plan and advisor.
Considerations for Choosing a Financial Planner
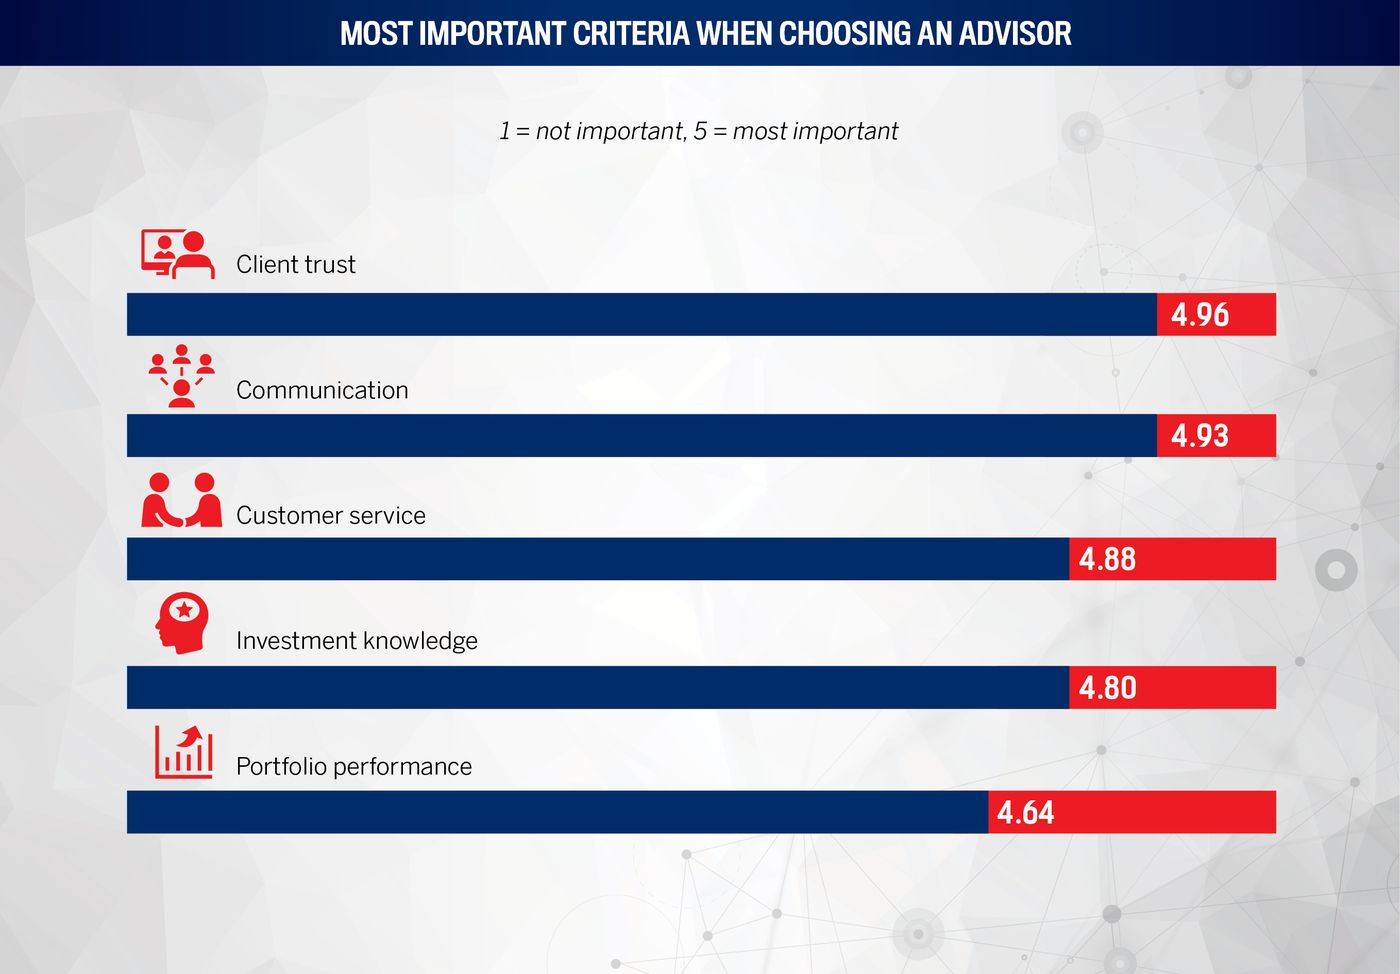
Choosing a financial planner is a significant decision that requires careful consideration. Canadians are advised to ask potential planners specific questions to determine if working with them is the right fit. It is important to understand the planner's approach, how they are compensated, and the scope of services they provide. Consumers should verify the planner's credentials, such as whether they hold a QAFP or CFP certification from FP Canada. Checking if the advisor is a member of a professional association like Advocis can also provide insight into their commitment to ongoing education and ethical standards.
Another key consideration is whether the planner's service model aligns with the client's preferences for interaction, be it in-person, remotely, or through a hybrid approach. Clients should inquire about the types of clients the planner typically works with, as some firms or advisors specialize in serving specific groups such as business owners, healthcare professionals, or the 2SLGBTQ+ community. Understanding any minimum asset requirements is crucial, as these thresholds can determine eligibility for certain service tiers. Finally, the initial conversation should clarify how the planning relationship will work, how often reviews will occur, and how the plan will be adapted over time in response to life events and economic changes.
- Verify professional designations (QAFP, CFP).
- Ask about their approach to financial planning and fee structure.
- Check membership in professional associations (e.g., Advocis).
- Confirm minimum asset requirements for service.
- Discuss their typical client profile and any specializations.
- Understand their service model (dedicated planner vs. team-based, remote vs. in-person).
- Clarify the frequency of plan reviews and update processes.
Common Financial Challenges Addressed by Planning
Financial planners in Canada commonly address a series of widespread challenges faced by individuals and families. One prevalent issue is financial anxiety stemming from economic uncertainty, which can be compounded by limited emergency savings and budgeting difficulties. Planners work to create structured budgets and savings plans to build financial resilience. Another significant area is retirement planning, where advisors help clients explore new approaches to traditional retirement ideas that may no longer be relevant, ensuring their income strategy is robust and accounts for all potential sources.
Tax efficiency is a major focus, given the estimation that Canadians collectively overpay taxes by millions of dollars annually due to unclaimed credits and deductions. Planners develop strategies to help reduce income tax. For major purchases like a home, planners provide guidance on the options available, especially as an increasing number of young Canadians rely on parental support for their first home. They also assist with complex needs like business succession, estate planning, and optimizing debt repayment. The overarching aim is to bring clarity to complex decisions by reframing them around the client's personal values and what matters most to them, helping to build actionable plans that inspire confidence.
The Regulatory and Advocacy Landscape
The financial planning industry in Canada operates within a specific regulatory and advocacy context. A prominent issue, as championed by Advocis, is the lack of a national framework for financial advisor and planner title protection. This means that, in many jurisdictions, the titles "financial advisor" or "financial planner" are not legally protected, potentially allowing individuals without specific qualifications to use them. Advocis continues to call for such a framework to protect consumers from unqualified advisors, arguing that the next economic crisis could involve bad advice.
Associations like Advocis also engage with provincial regulators on specific rules that impact the industry. For instance, Advocis and CALU (the Conference for Advanced Life Underwriting) have filed formal submissions regarding Ontario's proposed Managing General Agency (MGA) rule, expressing concerns that it could impact small advisors and risk driving up the cost and reducing the accessibility of advice for consumers. This advocacy work highlights the ongoing dialogue between professional bodies and regulators to shape an environment that balances consumer protection with a viable market for financial advice. The industry's evolution is influenced by these efforts to establish clearer standards and accountability.
Frequently asked questions
What are the typical costs or minimums for financial planning services?
Cost structures and minimums vary by provider. Some firms, like TD Wealth, have specific asset minimums. Their Financial Planning services require a minimum of $100,000 in investable assets, while their Private Wealth Management services require $1,000,000 or more. Costs can be fee-based (a percentage of assets), commission-based, or a flat fee for a plan. It is essential to ask any potential planner for a clear explanation of how they are compensated.
What is the difference between a financial planner and a financial advisor?
A financial planner is a type of financial advisor who helps you create a plan to reach your long term financial goals. This distinction is important because not all advisors provide holistic planning. Financial planners, such as those certified by FP Canada, look at every aspect of a client's financial picture to build integrated strategies. Their work goes beyond investments to include tax efficient strategies, risk reduction, and estate planning. Services like those from IG Wealth Management or TD Wealth are designed to create a comprehensive plan unique to each client. Ultimately, a financial planner provides a structured, long term roadmap for your entire financial life.
How do I find a qualified financial planner in Canada?
You can find a qualified financial planner by using the Find Your Planner tool to locate a QAFP professional or CFP professional near you who meets your unique needs. These certifications are offered by FP Canada, which equips financial planning professionals. Checking for membership in professional associations like Advocis, the largest voluntary professional membership association of financial advisors in Canada, is also advisable. Many firms, such as TD Wealth, allow you to answer a few questions online to help find an advisor or request a call from a representative. It is recommended to verify a planner's qualifications directly, as title protection frameworks are still being advocated for nationally.
What does a financial plan actually include?
A comprehensive financial plan includes an analysis of your current financial situation and goals for the future. For example, an IG Living Plan can incorporate all major expenditures and provide a savings schedule while calculating your total retirement income from all sources like CPP, TFSAs, RRSPs, and pensions. It also involves developing strategies to optimize debt repayment and savings goals. Plans incorporate tax and estate planning advice on maximizing donations in tax efficient ways and include insurance recommendations to maintain your family's lifestyle. The plan is built through collaboration with an advisor who gets to know your family's goals to keep you on track through life's changes.
Are financial planner titles protected by law in Canada?
Currently, there is no national framework for financial advisor and planner title protection in Canada. Advocis, The Financial Advisors Association of Canada, continues its call for such a framework to protect consumers. This lack of uniform regulation means titles are not always legally restricted to individuals with specific qualifications. This situation highlights the importance of consumers verifying a planner's certifications, such as the CFP or QAFP designations from FP Canada. The concern is that without title protection, Canadians could be at risk from unqualified advisors, especially during times of economic uncertainty when sound advice is critical.
Who do financial planning services typically cater to?
Financial planning services cater to a wide range of Canadians, from individuals and families to high net worth clients. Many firms have tiered services based on asset levels for instance, TD Wealth Financial Planning requires a minimum investment of 100000 dollars, while its Private Wealth Management services require one million dollars or more. Specialized teams exist for specific groups, such as business owners, healthcare professionals, and the 2SLGBTQ community. Services also support young Canadians and their parents, such as with guides on buying a first home. Ultimately, these services aim to help all clients feel confident about their financial future through personalized guidance.
Sources and further reading
- IG Wealth Management: Financial Planning & Advisor Services ig.ca
- Advocis | The Financial Advisors Association of Canada advocis.ca
- Wealth Management & Financial Planning td.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.