Travel rewards credit cards in Canada allow cardholders to earn points or miles on everyday purchases, which can be redeemed for flights, hotels, and other travel expenses. These cards often include additional benefits such as travel insurance, airport lounge access, and savings on foreign transaction fees. The value of a card depends on its annual fee, earn rates on specific spending categories, and the travel perks that align with an individual's habits. For Canadian travellers, understanding these features is key to selecting a card that can help manage travel costs and provide useful protections.
How Travel Rewards Credit Cards Function
Travel rewards credit cards operate by converting a percentage of your spending into redeemable points or miles. Cards typically offer accelerated earn rates in specific purchase categories such as groceries, dining, or travel bookings. For example, some cards provide up to 6 points per dollar spent on select purchases, while others offer a flat rate of 1 point per dollar on all spending. The points accumulated are stored in the card's associated rewards program, such as Scene+, Avion, Aventura, or Membership Rewards. Cardholders can later redeem these points through the program's travel portal, by transferring them to airline partners, or for other rewards like merchandise. The fundamental value proposition is using regular spending to subsidize future travel costs, provided the card's annual fee and interest rates are managed responsibly. It is important to note that points are earned on eligible purchases, and definitions of eligible categories like 'groceries' or 'travel' can vary significantly between different card issuers and their specific terms and conditions. A travel credit card is a great choice if you are a frequent traveler or if you are planning a trip in the future, as you can earn points on everyday purchases and use them towards your next trip, big or small.
Core Benefits and Travel Protections
Beyond earning points, many travel credit cards include a suite of travel-related benefits designed for Canadian travellers. A primary benefit for international travel is the waiver of the standard 2.5 percent foreign transaction fee, which can lead to significant savings. Comprehensive travel insurance is a common feature, with coverage often including up to $2 million in emergency medical insurance for eligible trips, trip cancellation and interruption insurance, and coverage for flight delays or lost baggage. Some cards provide access to airport lounges, which may be offered as a set number of complimentary visits per year or unlimited access. Other potential perks include application fee rebates for the NEXUS trusted traveller program, annual travel credits, and discounts on car rentals or food delivery services. These benefits add tangible value and convenience, particularly for frequent travellers. The specific insurance coverage, including limits and eligibility criteria, is detailed in a benefit guide or certificate of insurance provided by the card issuer, which cardholders should review before travelling. With a travel credit card, you can earn points that can be redeemed for flights, hotels, car rentals, vacation packages and more, and some of these cards offer additional benefits such as travel insurances, complimentary airport lounge access and concierge services.
Comparing Earn Rates and Rewards Programs
The structure of a card's rewards program dictates how quickly points are earned and how flexibly they can be used. Programs generally fall into two categories: fixed-value and transferable points. Fixed-value programs, like Scene+ or Avion, allow points to be redeemed for travel at a predetermined rate, often making redemption straightforward for flights or hotels booked through the bank's portal. Transferable points programs, such as American Express Membership Rewards, allow points to be transferred at a 1:1 ratio to partner airline loyalty programs like Aeroplan, providing potentially greater value for premium flight redemptions. Earn rates vary significantly by spending category, with many cards offering the highest multipliers on groceries, dining, and direct travel purchases. It is important to review the specific definitions of bonus categories, as eligible merchants can differ between card issuers. For instance, a card may offer bonus points at 'eligible grocery stores,' which may include major chains like Sobeys and Safeway but exclude warehouse clubs or specialty stores.
Key factors when comparing earn structures include the card's earn rates on different spending categories. You should examine the points earned per dollar spent on categories like groceries, dining, travel, and everyday purchases. It is important to understand any spending caps or limits that may apply to bonus categories. The overall value of a card's earn structure depends on how well it matches your personal spending habits.
- The base earn rate on all purchases, often 1 point per dollar.
- Accelerated rates on bonus categories like groceries, dining, or travel.
- Any spending caps that limit the number of bonus points you can earn in a period.
- Whether bonus earnings are limited to bookings made through a specific travel portal.
- The ability to combine points with other loyalty programs for enhanced redemption options.
- The existence of promotional earn rates, such as additional points on hotel and car rental bookings made through the card issuer's travel service.
Analysing your own monthly spending patterns against these card features is the most effective way to estimate potential point accumulation. For example, a card that offers 5 points per dollar on eligible eats and drinks in Canada, including groceries and food delivery, would be highly valuable for someone with substantial spending in those categories. You must stay within any applicable monthly spend caps to maximize this value. If you want to earn points faster, choose a travel rewards card that gives you bonus points when you spend on certain categories like gas or groceries. You should ensure your top spending categories match the card's bonus reward categories to get the best return.
Annual Fees and Card Tiers
Travel rewards cards in Canada are available across a spectrum of annual fees, which generally correlate with the level of benefits provided. No-annual-fee cards offer a basic entry point, typically with lower earn rates and minimal travel insurance. Mid-tier cards, with annual fees commonly ranging from $120 to $150, provide better earn rates, more comprehensive insurance, and may include some lounge passes. Premium cards command annual fees of $399 or more, with the highest tier reaching $799. These premium cards justify their cost with benefits like unlimited airport lounge access, high-value annual travel credits, elite hotel status, and superior insurance limits. The following table outlines typical features associated with different fee levels, using examples from major Canadian issuers for context.
| Fee Tier | Typical Earn Rate | Common Benefits | Example Card Features |
|---|---|---|---|
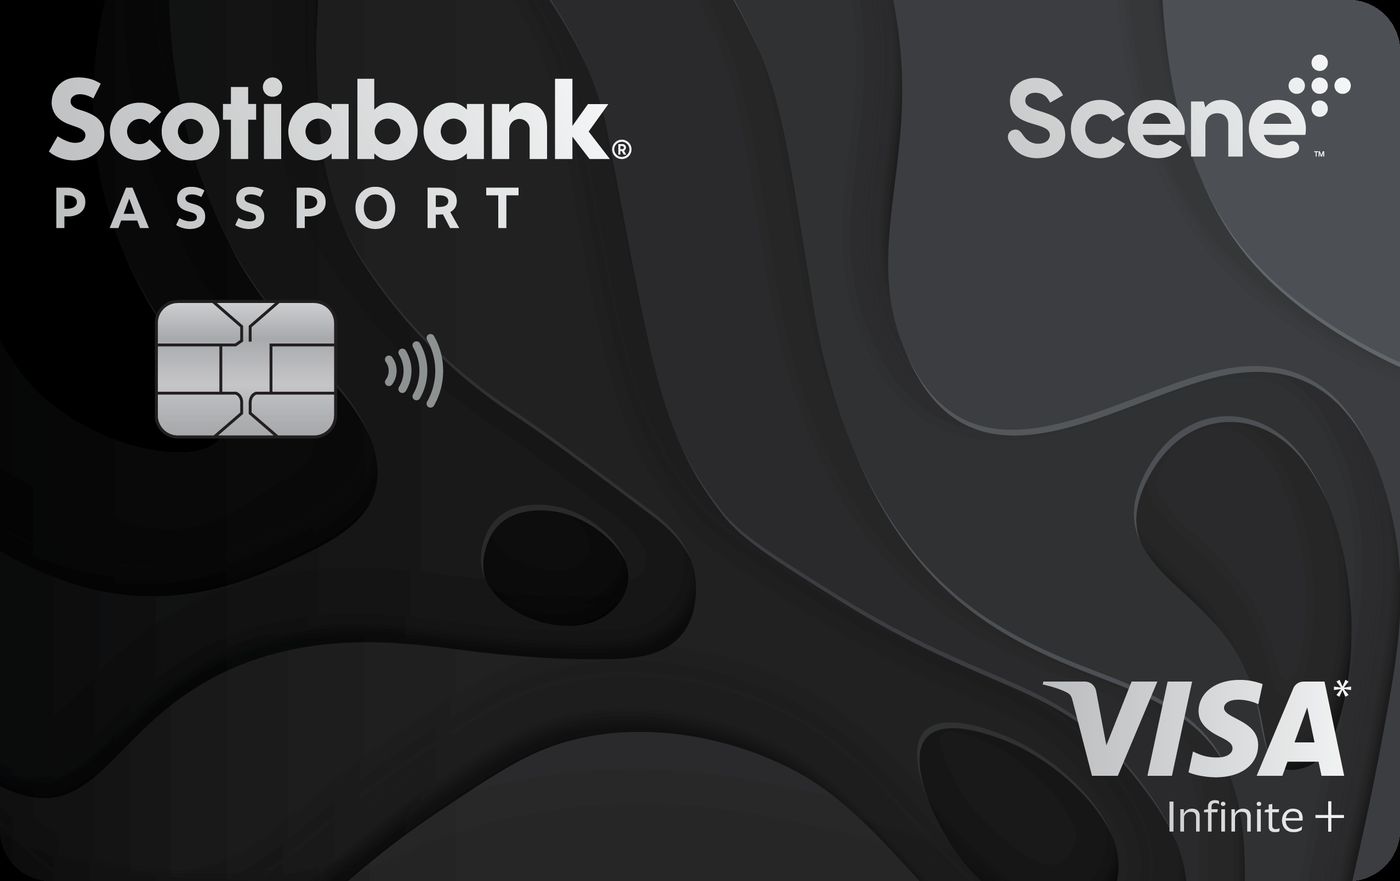
| Mid-Tier ($120-$192) | Up to 5x on bonus categories | Enhanced insurance, some lounge visits, no FX fees on some cards | American Express Cobalt Card ($192 fee, 5x on eats/drinks), Scotiabank Passport Visa Infinite+ (6 lounge visits, no FX fee) |
| Premium ($399-$799) | 2x flat or high multipliers | Lounge access, travel credits, hotel status, top-tier insurance | Scotiabank Platinum American Express ($399 fee, 2x Scene+ points), The Platinum Card from American Express ($799 fee, unlimited lounge access, $400 annual credit) |
Evaluating whether the benefits outweigh the annual fee requires an honest assessment of how often you will use the included perks. For infrequent travellers, a card with a lower fee may provide better net value. Premium cards often feature additional benefits like automatic Marriott Bonvoy Gold Elite status or Hilton Honors Gold status, which can provide room upgrades and late checkout, adding value for those who stay frequently with those hotel chains. Some travel rewards credit cards may have fees, including annual fees, balance transfer fees and foreign transaction fees, and it is important to compare these fees against the card's rewards and benefits to make sure it's a good fit for your needs.
Eligibility and Application Considerations
Most travel rewards credit cards, particularly those with higher benefits, have specific eligibility requirements set by the issuer. Applicants must also meet the age of majority in their province and have a Canadian credit history, with a good to excellent credit score typically needed for approval. Some banks offer application tools that provide a pre-qualification check without affecting your credit score. For newcomers to Canada within the past three years, some issuers may require an in-branch application rather than an online process. It is important to have your financial information, including income details and social insurance number, ready when applying. The application process itself is often conducted online and can provide a decision in less than a minute, though additional verification may be required. Approval rates can vary based on the card's tier and the issuer's current risk assessment criteria. You may want to consider travel credit card features like annual fees, redemption flexibility and travel insurance, and don't forget to check out the welcome offers too when assessing eligibility and value.
Steps for Choosing a Travel Rewards Card
Selecting a suitable travel rewards card involves a systematic review of your financial habits and travel goals. The first step is to identify the type of travel value you prioritize most, such as flexible points for any airline, premium airport perks, or straightforward cash-like value for travel. Next, analyse your monthly spending by category to see which card's bonus earn rates align with where you spend the most money. Then, compare the annual fees and interest rates against the card's welcome offer, ongoing benefits, and insurance coverage to calculate the potential net value. Finally, review the redemption process for the rewards program to ensure it offers the flexibility and availability you need for your travel plans. Many comparison tools suggest evaluating cards based on a specific monthly spending amount, such as $2,200 after accounting for the annual fee, to model potential rewards earnings.
A methodical approach to choosing a travel credit card includes several key steps. First, identify the kind of travel value you want most, such as flexible points or premium perks. Next, compare cards within that category based on their specific features and benefits. Then, review the annual fees and ensure the card's cost aligns with the benefits you will actually use. Finally, consider the welcome offers and the flexibility of the redemption options available.
- Define your primary travel goal (flexibility, airline loyalty, premium perks).
- Audit your monthly spending in categories like groceries, dining, and travel.
- Compare cards that match your spending and goal, focusing on earn rates and fees.
- Evaluate the strength of welcome offers and the long-term value of ongoing benefits.
- Read the terms for travel insurance coverage and redemption rules.
- Check your eligibility based on income and credit score before applying.
- Consider if you will use ancillary perks like lounge access, NEXUS rebates, or dining credits.
- Apply for the card that offers the best projected net value for your specific situation.
This process helps ensure the card you choose will be a useful financial tool rather than a cost. It is also advisable to review the methodology used by comparison sites. These sites often consider factors including annual fees, earn rates, ease of use, welcome offers, approval rates, eligibility, and redemption options when ranking cards. When choosing the right travel credit card, think about the features and benefits that best suit your lifestyle and spending habits. Consider factors such as how quickly you can earn points and how easily you can spend those points. Also evaluate extra travel benefits to get the most out of your travel rewards card.
Common Mistakes to Avoid
Several common errors can diminish the value of a travel rewards card or lead to unnecessary costs. A frequent mistake is choosing a card for its welcome bonus without considering whether the ongoing earn rates and annual fee make sense for your long-term spending. Another error is not understanding redemption rules, such as being required to book through a specific travel portal to use points or to access the best value, which can limit flight options. Carrying a balance on these cards is particularly costly, as purchase interest rates are typically between 20.99 and 21.99 percent, which can quickly negate any points earned. Overlooking the details of travel insurance, such as the number of days of coverage or eligibility requirements based on trip duration, can leave a traveller unprotected. Finally, not actively using the card's perks, like lounge passes or annual travel credits, means you are paying for benefits you do not receive. Other pitfalls include not maximizing bonus categories, misunderstanding points transfer ratios to airline partners, and applying for multiple cards in a short period, which can temporarily lower your credit score. Fly a lot? It may be worthwhile to get a travel card that lifts your travel experience with complimentary access to airport lounges so you can relax while you wait to board your plane, but only if you will actually use that access.
Redemption Flexibility and Partner Networks
The true utility of accumulated points is realized at the redemption stage, and flexibility varies widely between programs. Fixed-value programs like RBC's Avion points allow booking any available flight from over 500 participating airlines through their portal with fixed-points pricing, avoiding surge pricing and blackout dates. These points can also often be converted to leading loyalty programs like WestJet Rewards, British Airways Executive Club, and American Airlines AAdvantage at specified ratios. Transferable points programs, primarily from American Express, offer a 1:1 transfer to Aeroplan and several other airline and hotel partners, which can be advantageous for securing premium cabin awards. Some cards allow points to be redeemed for non-travel rewards like merchandise or gift cards, though this typically offers a lower value per point. It is crucial to understand any points expiration policies. While many bank-operated programs state points do not expire while the account is open, partner airline miles may have activity-based expiry rules. The redemption process is usually conducted online via the issuer's rewards centre or the partner airline's website, with customer service phone lines available for assistance. Redeeming points is easy and flexible with options for everyone, and you can enjoy all sorts of great rewards beyond flights. When you are ready to redeem your points, you can visit the issuer's online rewards centre or call the customer service number provided on your statement for guidance.
Frequently asked questions
Do points on travel rewards credit cards expire?
For most major Canadian travel rewards cards, points do not expire as long as the card account remains open and in good standing. However, it is essential to check the specific terms of the individual rewards program, as policies can vary. Some programs linked to airline partnerships may have different rules regarding point expiry based on account activity. Cardholders should review their cardholder agreement for the exact terms governing point validity and any conditions that could lead to forfeiture. Travel credit cards can be a fun way to prepare for your next adventure, and as long as your travel card is active and is in good standing, your points don't expire and you can use them whenever you're ready.
Can I use travel points for things other than flights?
Yes, many travel rewards programs offer flexible redemption options beyond flights. Points can often be used to book hotels, car rentals, vacation packages, or cruises through the issuer's travel portal. Additionally, many programs allow redemptions for non-travel items such as merchandise, gift cards, or statement credits, though the value per point may be lower compared to travel redemptions. Some cards also allow points to be used for experiential rewards or charitable donations, providing a wide range of uses for accumulated rewards. You can still redeem your travel rewards credit card points for local travel, and if your travel plans are on hold altogether, you have the flexibility to redeem your points for things like merchandise, gift cards and so much more.
What is a foreign transaction fee and how can I avoid it?
A foreign transaction fee is a charge, typically 2.5 percent of the purchase amount, applied when you make a purchase in a foreign currency or from a merchant located outside Canada. Some travel rewards cards specifically advertise no foreign transaction fees as a key benefit. Using such a card for spending while abroad or on foreign websites can lead to significant savings compared to standard credit cards. It is one of the most valued features for Canadians who travel internationally, as it makes the cost of purchases abroad more predictable and transparent. The Scotiabank Passport Visa Infinite+ Card is noted as the best travel credit card in Canada with no foreign transaction fees, making it a strong option for international travel.
What kind of travel insurance comes with these cards?
Coverage varies, but comprehensive cards often include emergency medical insurance, trip cancellation and interruption insurance, flight delay insurance, and lost or delayed baggage insurance. Emergency medical coverage can be as high as $2 million for eligible trips. It is crucial to review the certificate of insurance for each card to understand coverage limits, eligibility requirements, and the steps required to make a claim. Some cards also include rental car collision/loss damage insurance, hotel burglary insurance, and travel accident insurance, forming a broad safety net for travellers. Yes, different cards come with different insurance and travel protection options, and you should learn more about benefit guides and insurance certificates for different travel credit cards.
Are travel rewards cards worth the annual fee?
The value depends on your spending and travel habits. To assess worth, calculate the dollar value of the points you expect to earn annually, add the value of any used perks like lounge access or travel credits, and then subtract the annual fee. If the net value is positive and the card's benefits are things you will use, the fee can be justified. For low spenders or infrequent travellers, a no-fee card may offer better value. Premium cards with fees near $800 require frequent use of their high-end benefits, such as unlimited lounge visits and hotel status, to realize their full value. While the American Express Platinum card's annual fee is steep, the premium travel perks arguably outweigh the cost to use it for frequent travellers who can make regular use of high-end travel benefits.
How do I redeem points for travel?
Redemption is usually done through the card issuer's online rewards centre or travel booking portal. For fixed-value programs, you can often book travel directly and pay with points during checkout. For transferable points programs, you typically transfer points to an airline partner's loyalty account and then book award travel through that airline's website. Some cards also offer a 'pay yourself back' feature where travel purchases are credited to your statement using points. For specific guidance, cardholders can call the customer service number listed on their statement or visit the dedicated rewards website provided by their card issuer. When you're ready to redeem your Aventura Points, for example, you visit the CIBC Rewards Centre or call their dedicated phone number.
Sources and further reading
- The best travel credit cards in Canada for 2026 ratehub.ca
- Best Travel Credit Cards in Canada nerdwallet.com
- Travel rewards credit cards cibc.com
- Travel Rewards Credit Cards, Apply Online | RBC ... rbcroyalbank.com
- Credit Cards with Travel Rewards | Scotiabank Canada scotiabank.com
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.