CIBC offers several Tax-Free Savings Account (TFSA) products, each with its own interest rate structure. The CIBC TFSA Tax Advantage Savings Account offers a standard interest rate, while CIBC TFSA GICs, including Bonus Rate and cashable options, provide guaranteed returns at varying rates. These rates are specific to the product type, term length, and account balance, and are calculated on an annual basis. Understanding the different CIBC TFSA offerings helps Canadians make informed decisions about where to hold their tax-free savings.
Understanding CIBC TFSA Interest Rates
Interest rates on CIBC Tax-Free Savings Accounts are not uniform and depend entirely on the specific product you choose. The CIBC TFSA Tax Advantage Savings Account is a daily interest savings account where the rate is applied to your balance. For balances up to $24,999.99, the published rate is 0.250 percent. This account provides tax-free interest and allows access to your money at any time. In contrast, CIBC TFSA Guaranteed Investment Certificates (GICs) offer fixed or variable interest rates that are guaranteed for a set term.
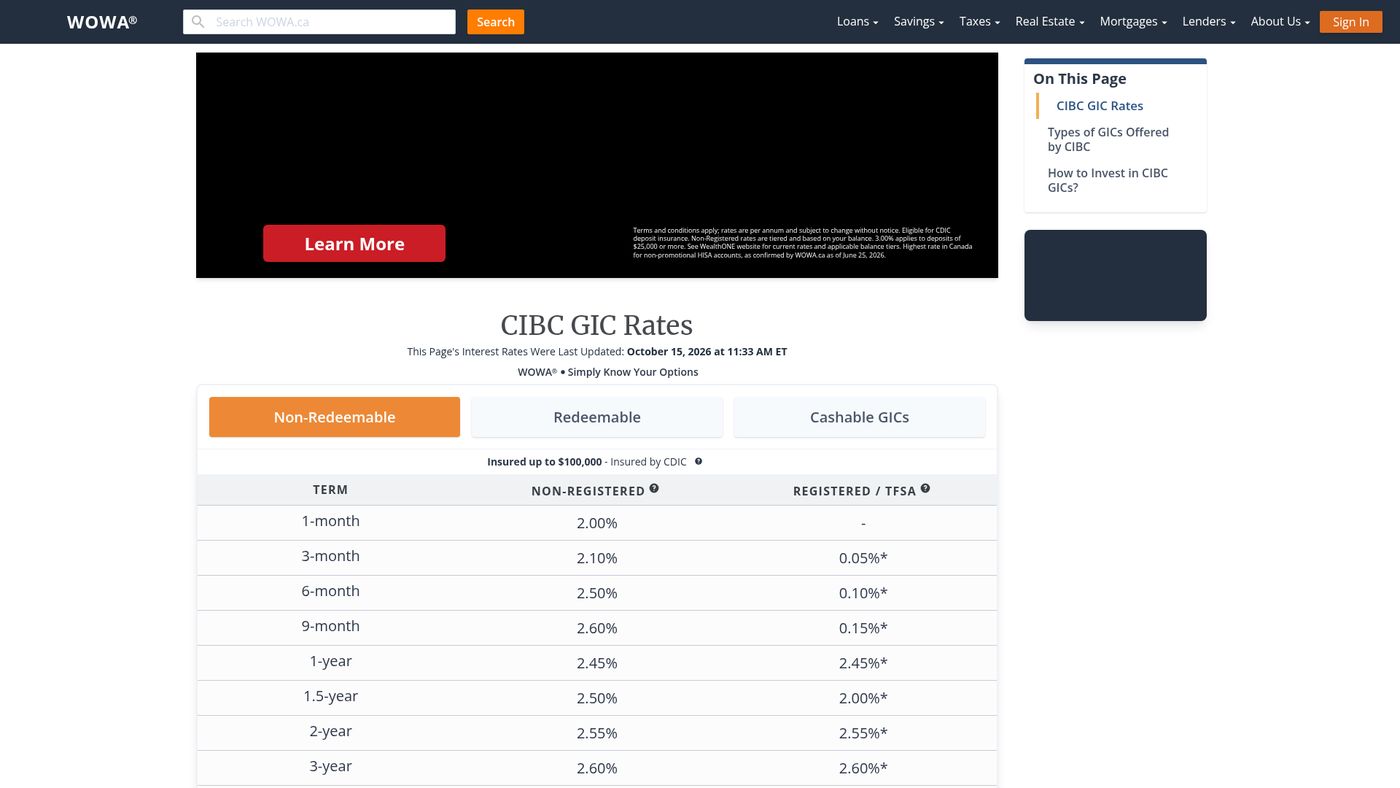
CIBC TFSA GICs come in several forms, each with a different rate structure. The CIBC TFSA GIC (Redeemable) offers rates ranging from 0.05 percent to 0.90 percent depending on the term selected, providing flexibility to cash out. For higher guaranteed rates, the CIBC Bonus Rate TFSA GIC offers a regular interest rate of 3.00 percent, with promotional rates sometimes reaching approximately 3.25 percent. These Bonus Rate GICs are available for terms like one year or two years and are a promotional product. All CIBC GIC rates are calculated on an annual basis and apply to the at-maturity interest payment option.
It is crucial to distinguish between regular and promotional rates. CIBC's regular GIC interest rates are typically lower than their Bonus Rate promotional offers. Financial institutions, including online banks and credit unions, often provide higher rates than traditional banks like CIBC for standard savings products. For example, as of October 2026, some online banks offered TFSA savings account rates around 1.50 percent. When evaluating rates, Canadians should consider the product type, term length, minimum investment, and whether the rate is promotional or standard.
Types of CIBC TFSA Accounts and GICs
CIBC provides a range of TFSA products designed for different savings goals and risk tolerances. The primary options include the TFSA Tax Advantage Savings Account and various TFSA GICs. The TFSA Tax Advantage Savings Account is a simple savings vehicle that earns daily interest at a competitive rate, with no term commitment. This makes it suitable for an emergency fund or short-term savings where immediate access is important. The interest earned in this account is tax-free, and there are no restrictions on withdrawals.
For those seeking guaranteed returns, CIBC offers multiple GIC products that can be held within a TFSA. The CIBC Bonus Rate TFSA GIC provides a guaranteed interest rate that does not change over the selected term, typically one to two years. CIBC cashable GICs for TFSAs offer lower rates but allow you to cash out at any time at specified early redemption rates. CIBC also offers market-linked GICs, which are tied to stock market index performance and have a minimum guaranteed total return, such as 6.90 percent over two years for a specific product.
Other specialized GIC products include the CIBC Easy Builder GIC, which uses a laddering strategy across five terms, and the CIBC Escalating Rate GIC, where the interest rate increases each year. There is also a CIBC Variable Rate GIC tied to the prime rate, which is cashable after 29 days. All these GIC types are eligible for registered accounts like TFSAs. The minimum investment for most CIBC GICs is $1,000, though some products like the Easy Builder GIC have a minimum of $2,500. These products are CDIC-insured, protecting the principal and interest.
TFSA Contribution Rules and Limits
To use any CIBC TFSA effectively, you must understand the federal contribution rules. The contribution room is the total amount you are allowed to deposit into all your TFSAs across all financial institutions. Contribution room accumulates each year for every Canadian resident who is at least 18 years old or the age of majority in their province. Unused room carries forward indefinitely. The annual contribution limit is set by the Canada Revenue Agency and changes periodically.
Exceeding your contribution limit results in a penalty tax of one percent per month on the excess amount. It is your responsibility to track your contributions and withdrawals. Withdrawals from a TFSA are tax-free and the amount withdrawn is added back to your contribution room at the beginning of the next calendar year. This means you can re-contribute the withdrawn amount in a future year without penalty. The maximum weekly contribution amount, as referenced by CIBC, is $134, which can help with budgeting regular savings.
Eligibility for a TFSA requires you to be a resident of Canada or a qualifying non-resident and be at least the age of majority in your province or territory. Before opening a CIBC TFSA, you should determine your available contribution room by checking your CRA My Account or the Notice of Assessment. Financial institutions report contributions and withdrawals to the CRA, but the official calculation of your room is managed by the CRA. Understanding these rules prevents costly mistakes and maximizes the tax-free benefits of the account.
Comparing CIBC TFSA Rates to Other Providers
When shopping for a TFSA, it is useful to compare CIBC's offerings with those from other financial institutions. As a major traditional bank, CIBC's standard TFSA savings account rates are often lower than those offered by online banks and some credit unions. For instance, as of 2026, online banks like EQ Bank offered TFSA savings account rates around 1.50 percent with no minimum balance, compared to CIBC's 0.25 percent for its Tax Advantage Savings Account. Many credit unions also offer competitive TFSA rates, though some are limited to residents of a single province.
Several providers offer high-interest TFSAs that are examined for their overall value based on criteria like annual percentage yields, minimum balances, and fees. Institutions such as Achieva Financial, Canadian Tire Financial, and Wealthsimple provide registered savings accounts with competitive rates. Some accounts, like those from ATB Financial or FirstOntario Credit Union, are restricted to residents of Alberta and Ontario respectively. National Bank of Canada and Meridian Credit Union also offer TFSA products available in multiple provinces.
| Financial Institution | Sample TFSA Product (2026) | Notable Rate/Feature |
|---|---|---|
| CIBC | TFSA Tax Advantage Savings Account | 0.25% rate |
| EQ Bank | TFSA Savings Account | 1.50% rate |
| Canadian Tire Financial | Tax Free High Interest Savings Account | Promotional rates may apply |
| Wealthsimple | Registered Savings Account (TFSA) | Part of a digital investment platform |
| Meridian Credit Union | TFSA High Interest Savings | Available in multiple provinces |
Evaluation methodologies for these accounts consider factors beyond just the interest rate. These include digital banking experience, access to other TFSA investment products like mutual funds or ETFs, and fee structures. Online banks typically provide better rates but may have fewer physical branches and a more limited range of investment products compared to major banks like CIBC. When selecting a provider, consider your need for in-person service, the variety of investment options you desire, and the overall ease of banking with that institution.
Steps to Open a CIBC TFSA
Opening a CIBC TFSA is a straightforward process similar to opening any other bank account, provided you meet the eligibility criteria. You must be a resident of Canada and be at least 18 years old or the age of majority in your province or territory. The first step is to decide which CIBC TFSA product aligns with your financial goals, whether it is the daily interest savings account or a specific type of GIC. You can review the current interest rates and terms for each product on the CIBC website or by visiting a branch.
Next, you will need to have your personal information ready, including your Social Insurance Number (SIN), which is required for all registered accounts. You can apply for a CIBC TFSA online through their banking portal, over the phone, or in person at a branch. During the application, you will specify the type of account you want to open and make your initial contribution. For GICs, you must meet the minimum investment requirement, which is typically $1,000 for most CIBC GICs but can be $500 for products like Escalating Rate GICs.
After your account is opened, you can manage it through CIBC online banking or their mobile app. You can set up automatic contributions to help you reach your savings goals, with the maximum weekly contribution being $134. It is important to monitor your contribution room to avoid over-contributing. CIBC will provide you with account statements and tax slips for any transactions, though investment growth within a TFSA is not reported on your income tax return. Keeping track of your deposits and withdrawals ensures you stay within the limits set by the CRA.
Common Mistakes and Considerations
Several common mistakes can reduce the benefits of a CIBC TFSA or lead to penalties. A frequent error is over-contribution, which occurs when you deposit more than your available contribution room across all your TFSAs. The Canada Revenue Agency charges a tax of one percent per month on the excess amount until it is withdrawn. Another mistake is assuming all TFSA withdrawals are permanent reductions in contribution room. In fact, the withdrawal amount is added back to your room on January 1 of the following year, allowing for re-contribution.
Choosing the wrong product for your timeline is another consideration. Using a TFSA savings account for long-term goals may mean earning a lower interest rate compared to a TFSA GIC with a fixed term. Conversely, locking funds into a long-term non-redeemable GIC within a TFSA could be problematic if you need the money for an emergency, as early redemption may result in lost interest or penalties. It is important to match the product's liquidity and term with your financial objectives.
- Over-contribution: Depositing more than your personal TFSA contribution limit.
- Ignoring Provincial Restrictions: Some financial institutions' high-rate TFSAs are only available to residents of specific provinces.
- Misunderstanding GIC Terms: Confusing cashable and non-redeemable GICs or not realizing market-linked GICs have capped returns.
- Neglecting Rate Types: Not distinguishing between a standard rate and a limited-time promotional rate.
- Using as a Daily Account: Frequent withdrawals or using the TFSA for day-to-day transactions, which contradicts its purpose as a savings vehicle.
- Not Tracking Room: Relying solely on financial institution records instead of your official CRA contribution room.
Finally, consider the broader context of your finances. A TFSA is one tool among many, including Registered Retirement Savings Plans (RRSPs) and non-registered high-interest savings accounts. Your choice should depend on your income level, tax situation, and savings goals. Always review the specific terms and conditions of any CIBC TFSA product, including fees, transaction limits, and minimum balance requirements for higher interest rates, to ensure it meets your needs.
Frequently asked questions
What is the current interest rate for a CIBC TFSA savings account?
The CIBC TFSA Tax Advantage Savings Account offers a rate of 0.250 percent for balances up to $24,999.99. This is a standard rate for the daily interest savings account product. Rates are calculated on an annual basis and are subject to change. You should check the CIBC website for the most up-to-date rates and any promotional offers.
What is the minimum amount to open a CIBC TFSA GIC?
The minimum investment for most CIBC GICs, including those held in a TFSA, is $1,000. Some specific products have different minimums. For example, the CIBC Easy Builder GIC requires a minimum of $2,500, and the CIBC Escalating Rate GIC has a $500 minimum. These minimums apply when you open the GIC or make a contribution to an existing one.
How do CIBC TFSA rates compare to other banks?
As a major traditional bank, CIBC's standard TFSA savings account rates are often lower than those offered by online banks and some credit unions. For example, in 2026, online banks offered rates around 1.50 percent for similar accounts. However, CIBC's Bonus Rate GICs can be competitive for specific terms. It is important to compare rates, fees, and product features across multiple institutions based on your savings goals.
Can I get a higher interest rate with a CIBC TFSA GIC?
Yes, you can get a higher guaranteed interest rate with a CIBC TFSA GIC compared to a standard TFSA savings account. The CIBC Bonus Rate TFSA GIC offers a regular interest rate of 3.00 percent, with promotional rates sometimes around 3.25 percent for one or two year terms. This product earns guaranteed interest at a great rate that will not change over your term. Other TFSA GIC options include cashable GICs with rates from 0.05 percent to 0.90 percent depending on the term. Market linked GICs are also available, offering returns tied to stock market performance with a minimum guaranteed return. It is important to compare these products as promotional Bonus Rate GICs typically offer higher rates than regular GIC interest rates.
Are CIBC TFSAs safe and insured?
Yes, CIBC TFSAs are safe and insured. All CIBC GICs are insured by the Canada Deposit Insurance Corporation (CDIC), which guarantees your principal and interest up to applicable limits in the unlikely event of a bank failure. This insurance applies to products like the CIBC TFSA GIC which guarantees your principal and interest. Funds held within a CIBC TFSA savings account, such as the Tax Advantage Savings Account, are also covered by CDIC insurance. CIBC is one of the major banks in Canada, and this deposit insurance provides protection for your savings across these registered accounts. This makes CIBC TFSAs a secure place for your investments and cash savings.
What happens if I need to withdraw money from a CIBC TFSA GIC early?
The ability to withdraw money early from a CIBC TFSA GIC depends on the specific product type. For a redeemable or cashable CIBC TFSA GIC, you have the option to cash out at any time, though this is at specified early redemption rates which may be lower. These cashable GICs offer the freedom to access your money but generally pay lower interest rates due to this convenience. For non redeemable CIBC GICs held within a TFSA, you generally cannot cash out before the term ends without incurring a penalty or losing out on interest. It is crucial to review the terms of the specific GIC product before investing to understand all redemption rules and potential costs associated with early access to your funds.
Sources and further reading
- Tax Free Savings Account (TFSA) rates cibc.com
- Best TFSA Interest Rates in Canada for 2026 nerdwallet.com
- The best CIBC GIC rates in Canada ratehub.ca
This article explains how things work and is not financial, tax or legal advice. Rules, limits and rates change, so check the current figures with the Canada Revenue Agency, your province or your financial institution before you act.